How to Pitch a Stock: A Step-by-Step Guide

What is a stock pitch?

A stock pitch is a structured presentation of an investment idea, regarding the shares of a publicly traded company. Its purpose is to convince an audience, such as a portfolio manager or an investment committee, to buy, hold, or sell a stock based on a well-supported financial analysis.

A stock pitch typically combines an analysis of the company and its industry, an assessment of its financial performance and prospects, a valuation of its shares, and an evaluation of the main risks and opportunities. The analysis leads to an investment recommendation (Buy, Hold, or Sell), supported by a clear investment thesis and a target price reflecting the estimated value of the stock over a specified investment horizon.

The objective of this article is to put yourself in the position of a financial analyst and prepare your own stock pitch. You will select a publicly traded company, analyze its business and financial performance, assess its stock valuation, and formulate a reasoned investment recommendation.

A successful company is not necessarily an attractive investment. Whatever its true value may be, what really matters is whether or not its price is above or under this value. As Warren Buffett once said, price is what you pay, value is what you get. Therefore, the true question lies in understanding if the current price correctly reflects the company’s value.

Through this exercise, you will develop your skills in financial analysis, equity valuation, critical thinking, and investment decision-making.

Why is mastering stock pitching useful for your career ?

In finance, you may be asked to prepare slide decks, and pitch any type of investment idea. Moreover, being able to structure and organize a presentation is a key skill that will be useful in whatever field you want to work in.

1. An important tool in finance

Whether you aspire to work in Equity Research, Asset Management, Hedge Funds, or Private Equity, pitching stocks is something you may be asked to do:

  • Buy-Side (Mutual Funds, Family Offices, Hedge Funds): Long-only portfolio manager evaluates investment ideas pitches to deploy capital over the long term. Pitches are also useful in long/short or market-neutral hedge funds, to construct relative-value ideas or pair-trades (going long on an undervalued company while being short on an overvalued peer to isolate company-specific alpha from market-wide beta).
  • Sell-Side (Investment Banks): Equity Research Analysts pitch research views to institutional clients to generate trade ideas and commission.
  • Corporate Finance & M&A: The same fundamental skill set—evaluating business drivers, competitive moats, and financial models—underpins transaction advisory and strategic planning.

2. From Passive Learning to Active Valuation

Studying financial statements in a textbook is static. Building a stock pitch forces you to bridge theory and practice. You move from reading financial ratios to predicting operational drivers, learn to defend your assumptions, test sensitivities, and quantify risk versus reward.

3. Developing a “Variant View”

The market is generally efficient, meaning public information is already reflected in the stock price. The true relevance of a stock pitch lies in training your mind to spot market inefficiencies, situations where public perception, short-term panic, or over-optimism obscures a business’s true long-term earning potential.

How to pick your stock?

The first thing you will have to do is choose a stock to analyze and pitch. Those are the key factors to consider when choosing a firm to analyze:

  • Size (market capitalization): choosing a “large cap” (over a billion euros/dollars) will let you have access to much more content and research than when choosing a “small cap”, making your work easier.
  • Geography: European or American firms are usually easier to analyze because of more detailed reporting, a more developed financial ecosystem, and ?. You may also find it easier to analyze a firm from your home country.
  • Sector / industry: a utility company will be easier to forecast than a biotech one. This ultimately comes down to how you can model the company’s revenue and earnings: for Netflix, you can use number of subscribers X average subscription price, for Amundi you can use Asset under management X average management fee, but forecasting Société Générale’s earnings require you to have a much better understanding of the banking industry.
  • Number of operating segments: some firms may hold different business units that will have to be analyzed separately, making them more time-consuming to understand and analyze.

We can summarize this choice under two axis: predictability and complexity.

  • Predictability: can you reasonably make assumptions about this firm’s future revenue and profits, or is it too unpredictable to do so comfortably ?
  • Complexity: can you easily understand and model how the company makes its money or will it take some time to do so ?

Predictability versus Complexity graph
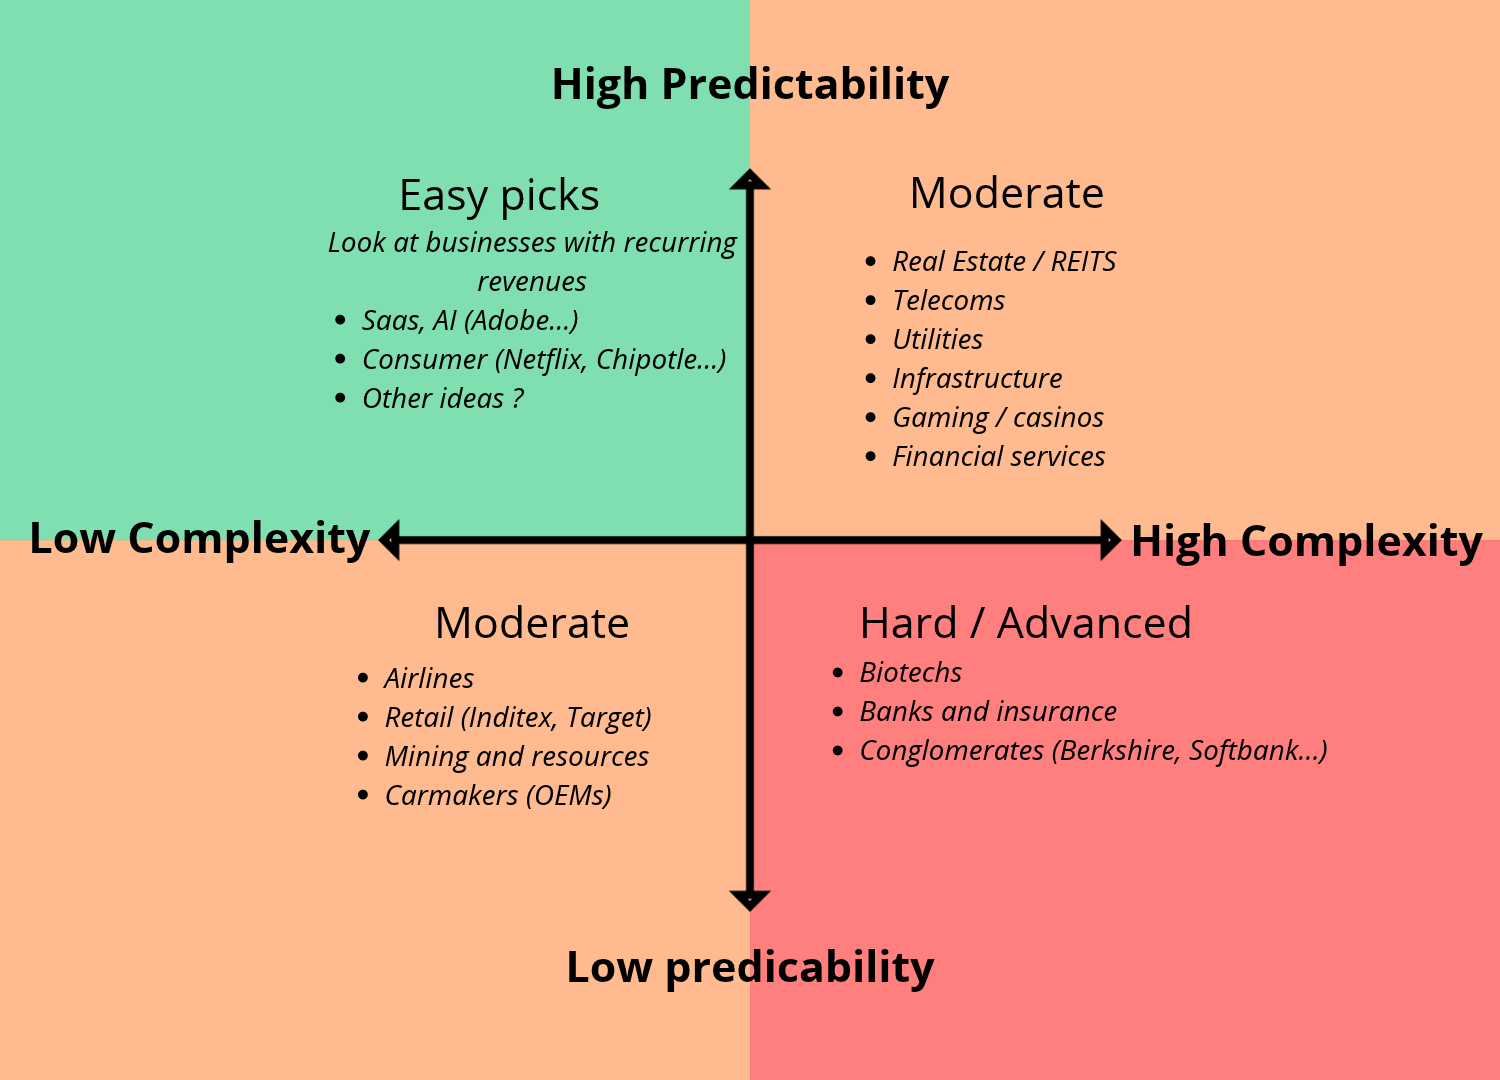
A graph of predictability vs complexity when it comes to picking a stock

Firms that are predictable and not complex will be easier to analyze. Firms that are both complex and unpredictable will be much more difficult to deal with.

A stock pitch does not have to be a BUY recommendation, but can also be a HOLD or a SELL. Therefore, simply pick a firm you want to work on and you’ll see in the end what your recommendation will be.

Structure of a Stock Pitch

Objective of this case study and roadmap

The goal of this guide is to provide a clear, step-by-step roadmap for building your first stock pitch.

Because you may come from different backgrounds and have more or less experience or expectations for this exercise, we outline what is strictly needed at a basics level for each section, along with how you can take your analysis further (advanced) to get closer to institutional equity research standards.

Step-by-Step Pitch Breakdown

Your pitch should cover the standard structure outlined below. The templates provided further in this article follow this order and structure, and you are welcome to follow it strictly, or feel free to change the order and add any additional section that you believe is relevant to your particular stock pitch.

For each section, start with Basic, and then look at Advanced to explore how to take it further depending on the depth of analysis you are targeting.

1 – Company Overview

  • What is needed (Basics): Provide a simple overview of what the firm does. Is it a single business or do they have multiple operating segments? In which countries does it operate? What is the current share price, market capitalization, turnover, profits, dividends?
  • How to take it further: Provide a detailed overview of the firm, including but not limited to detailed key data, shareholder analysis, ESG analysis, and corporate governance structure.

2 – Industry Overview

  • What is needed (Basics): What business does this firm operate in? Can you find a few key figures on this industry and how the markets believe it will evolve in the coming years? List a few competitors for your company.
  • How to take it further: Go deeper into the industry analysis by looking at research notes or papers. Try to find all relevant competitors and analyze market share dynamics, entry barriers, and structural shifts.

3 – Investment Thesis

  • What is needed (Basics): Try to formulate in a few key sentences why you believe this stock is, by itself, a good buy or sell (or neutral) opportunity. What do you think makes this a good or a bad business?
  • How to take it further: In addition to the basic arguments, try to understand and explain why this company may be undervalued or overvalued by the market. Is there an irrational fear or something the market may be wrong about (or at least irrational)? Is there an assumption embedded in the current share price that may be wrong in your opinion? In other words, how could it be possible that you are right and that the current market price is not?

4 – Valuation

Historical Share Price Analysis
  • What is needed (Basics): How has the stock evolved in the past 5 years? Can you identify specific events linked to sharp increases or drops in the share price? This is easily done by adding an image of the stock price that you can get from the internet.
  • How to take it further: Provide a graph of the historical share price versus the relevant index and key competitors, in a base 100 over a few years. Add a list of all relevant key events on the same graph. Build this graph yourself in Excel or Python.
Discounted Cash Flow (DCF)
  • What is needed (Basics): Build a simplified Discounted Cash Flow (DCF) model by forecasting the shareholders’ free cash flows and discounting them using the Weighted Average Cost of Capital (WACC). Estimate the terminal value using a perpetual growth model and explain the main assumptions underlying your valuation.
  • How to take it further: Develop a more detailed financial model based on the company’s fundamental operating drivers, integrating the income statement, balance sheet, and cash flow statement. Refine the WACC calculation, incorporate the bridge from enterprise value to equity value, and perform sensitivity and scenario analyses.
Comparable Company Analysis (CCA)
  • What is needed (Basics): Gather data on the firm’s main competitors. Look at price-to-earnings (P/E) and analyze your company’s current ratio to try and understand if there is room for increase or decrease in this ratio. Once you have a target ratio, you can compute a target price relative to it too.
  • How to take it further: Multiple ratios (EV/EBITDA, P/E, EV/Sales, etc.), choose the most relevant ratios, much more thinking on what they mean, and add a confidence interval to this.

5 – Valuation Summary, Investment Recommendation, Trading Implementation

  • What is needed (Basics): Summarize your DCF and comparable company valuation results in a single table to determine and justify your own target price. Do not average in the current stock price or analyst targets—use the current price to compute your expected upside or downside over an explicit horizon (e.g., 12 months), and use consensus targets only as an external point of comparison. Formulate an unambiguous recommendation (Buy, Hold, or Sell). Finally, define a practical trading setup: state your entry price, a take-profit target, and a stop-loss level based on thesis-invalidation criteria, and calculate the resulting reward-to-risk ratio (targeting at least a 3:1 ratio).
  • How to take it further (Advanced): Synthesize your valuation ranges using a football field chart across base, bull, and bear scenarios, and apply a weighted average with clear economic justification for the assigned weights. Provide a breakdown of recent, relevant analyst expectations (e.g., via Bloomberg/FactSet) in the appendix to highlight your variant view against consensus. On the trading side, detail your position sizing rules relative to fund portfolio limits and daily trading volume (liquidity constraints), identify the specific operational or macro catalysts that will trigger the repricing, and outline predefined conditions under which you would revise, hedge, or exit the trade.

6 – Appendix

  • What is needed (Basics): It’s a good habit to put your tables and calculations that are not already in your presentation inside of the appendix, in case you get asked any questions. You can also add graphs, maps, the company’s products, the countries it operates in …
  • How to take it further: Think about deep technical questions you could be asked during a Q&A session. Add captures of your dynamic Excel tables, debt schedules, sensitivity matrices, and detailed analyst opinion breakdowns.

Your stock pitch should present a coherent investment argument supported by financial data, quantitative analysis, and relevant charts or tables. All sources should be properly referenced, and all data has to be exact, up to date, and relevant.

Templates

To guide you through the process, we provide templates for both the excel file and the powerpoint presentation. You will find here one set of templates for the ‘Basic’ work and one for the ‘Advanced’ version.

Basic:

  • Excel file
  • Powerpoint template

Advanced:

  • Excel file
  • Powerpoint template

 Download the PowerPoint file for the stock pitch

 Download the Excel file for the financial valuation of the company for a stock pitch

Please find all available documents in this google drive : https://drive.google.com/drive/folders/10j3z13r2aw_YNaIS_tfYCTM6SS9lC_gg?usp=sharing

Examples

Here are a few examples of what a pitch could look like.

Please find all available documents in this google drive.

About the use of AI for investment analysis

I would strongly advise you to avoid using AI for this work. Three key reasons why:

  • Artificial intelligence (AI) tools can help you understand financial concepts, retrieve and organize information, write code, and improve the presentation of your analysis. However, they should not replace your own financial reasoning and investment judgment.
  • AI-generated financial data, calculations, and interpretations may contain errors or rely on outdated information. You should therefore verify all figures against reliable sources, understand the assumptions underlying your valuation, and critically assess the conclusions.
  • The objective of this case study is not simply to produce a stock pitch, but to develop your ability to analyze a company, estimate its value, and defend an investment recommendation. You remain responsible for the accuracy, originality, and quality of your work, but what really matters is the path you took, not the final outcome.

Feel free, however, to ask AI for advice, explanations on financial concepts, rewriting some text, or fixing mistakes.

Related financial concepts

  • Fundamental analysis
  • Market efficiency and a variant view
  • Discounted Cash Flow (DCF)
  • Comparable Company Analysis (CCA)

Why should you be interested in this post?

Whether you are preparing for interviews in Equity Research, Asset Management, Private Equity, or Corporate Finance, mastering a stock pitch moves you from passive theoretical learning to active investment decision-making.

By engaging with this case study, you will bridge the gap between financial statements and practical business valuation, practice finding market inefficiencies, and build hands-on skills in financial modeling and presentation.

Related posts on the SimTrade blog

   ▶ Hadrien PUCHE Price is what you pay, value is what you get – Warren Buffett

   ▶ Roberto RESTELLI The role of DCF in valuation

How to download financial data using either Python or R :

   ▶ Hadrien PUCHE How to download financial data with Python

   ▶ Hadrien PUCHE How to download financial data with R

Useful resources

Graham, B. (2003). The Intelligent Investor: The Definitive Book on Value Investing. Revised edition, with commentary by J. Zweig. HarperBusiness Essentials.

Damodaran, A. (2012). Investment Valuation: Tools and Techniques for Determining the Value of Any Asset. 3rd edition. Wiley.

Rosenbaum, J., and J. Pearl (2022). Investment Banking: Valuation, LBOs, M&A, and IPOs. 3rd edition. Wiley.

Lasse Heje Pedersen (2015): Efficiently Inefficient: How Smart Money Invests and Market Prices Are Determined

SimTrade course

Financial valuation

My experience as an Investment Research Analyst intern at Regarde Familia, a US single-family office

Aarichsun BATLISH

In this article, Aarichsun BATLISH (Indian Institute of Technology Kanpur, B.Tech in Civil Engineering, 2024-2028) shares his experience as an Investment Research Analyst intern at Regarde Familia, a single-family office based in Miami. During the internship, he researched venture capital funds and emerging technology sectors from the point of view of an investor who allocates capital to funds rather than directly to companies.

About the company

Regarde Familia is a single-family office (SFO) founded in 1980 to manage the wealth of the Empire Electric and Regarde family. It is based in Miami, Florida. A single-family office serves one family only: it has no outside clients and does not raise external capital. Its purpose is to preserve and grow the family’s wealth across generations, and Regarde Familia organizes its mission around four pillars: wealth preservation, education of the next generation, philanthropy and longevity.

Like many family offices of its size, Regarde Familia invests a large part of its capital indirectly, by committing money to private equity and venture capital funds run by specialized managers. Industry databases estimate its assets at around US$500 million, with a focus on buyout, growth and venture capital funds. Buyout funds acquire controlling stakes in mature companies, often financed with debt; growth funds back companies that are already expanding; venture capital funds invest in young start-ups. In this structure, the family office is a limited partner (LP): it does not pick start-ups itself but selects the fund managers who do.

Logo of Regarde Familia.
Logo of Regarde Familia
Source: the company.

I worked in Regarde Familia (RF) Research, a team that the office was building in 2026 to give it a forward-looking view of the sectors in which it wanted to allocate capital. Analysts were assigned to categories such as artificial intelligence and deep tech, climate and energy, fintech and cybersecurity, and a second track produced research on technology in higher education. The team worked remotely across India and the United States.

My professional experience

I joined the team after a competitive selection process based on a written assignment. Candidates had five days to produce two in-depth research pieces on sectors of their choice, covering both India and the rest of the world, and to go from the sector to the funds making the strongest bets in it, to a clear recommendation on one fund. I chose climate and energy, and artificial intelligence and deep tech. Around 15 people were selected out of several hundred applicants, based on the quality of their research reports and a demanding review of their analysis. I was selected for both the investment research and the higher-education research tracks and worked remotely from April to July 2026.

My missions

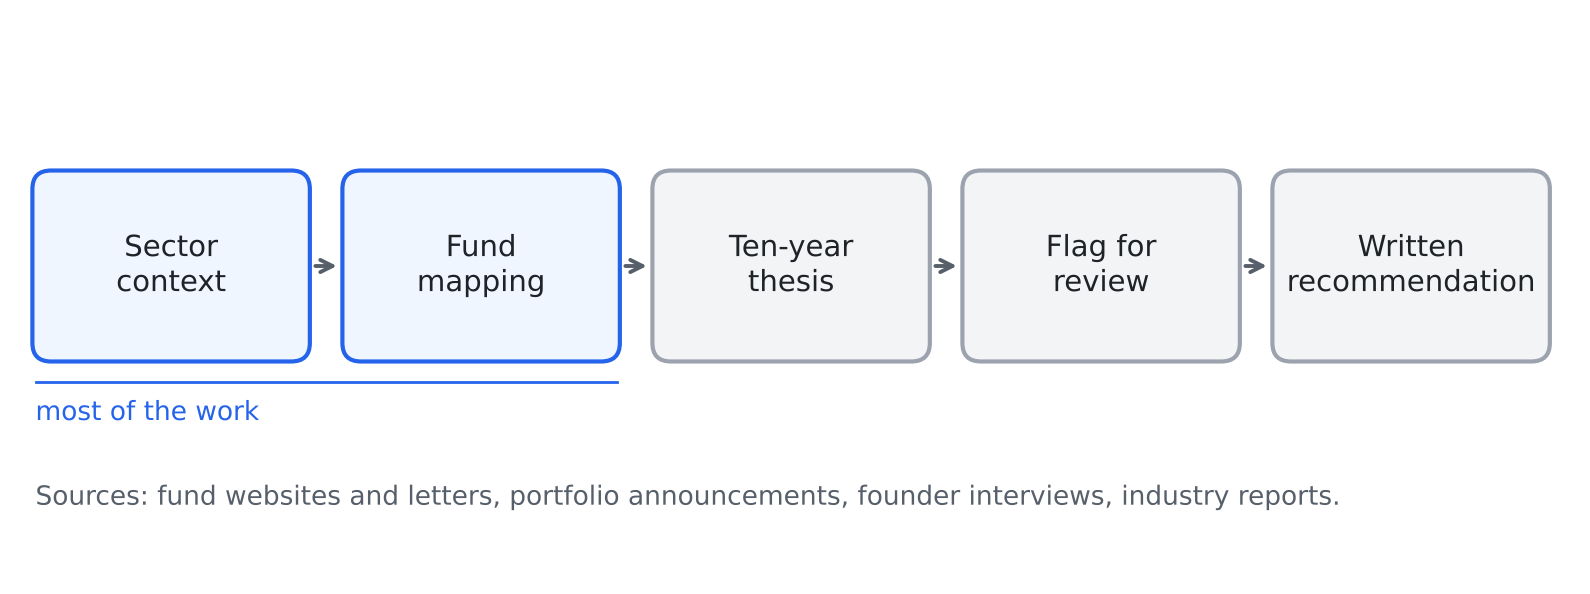
Sector and fund research. My main task was to build what the team called a “decade-cycle view” of my categories: which technologies are likely to gain market traction over the next ten years, which funds are positioned to benefit, and what the investment landscape could look like by the end of the decade. The approach is easiest to explain with the selection assignment I prepared before joining, which relied only on public information. In climate and energy, I built my thesis around electrification and grid-scale storage and then looked for early-stage funds whose portfolios matched it, in India as well as abroad. Congruent Ventures is a good illustration: an early-stage climate fund whose public portfolio includes Fervo Energy (next-generation geothermal power) and SPAN (smart electrical panels), two companies positioned exactly where electrification creates new demand. In India, funds such as Avaana Capital and Infuse Ventures back companies in electric mobility, distributed solar and energy management. In artificial intelligence, I studied how foundation models are moving into the physical world (robotics, autonomous systems and defense) and looked at funds such as Lux Capital, whose public portfolio spans several layers of that stack, from Hugging Face to Applied Intuition and Anduril. I quickly found that the most useful information was not in news articles but in fund letters, portfolio announcements and founder interviews.

Figure 1. How I approached sector and fund research.
Sector and fund research process
Source: the author.

Understanding how fund managers are evaluated. When a manager presents a new fund, an LP has to decide whether past returns came from a repeatable process or from a few lucky deals. During the internship, I learned the kind of questions allocators ask before committing capital: how gross and net returns were generated, how position sizes were decided, how much of the reported value has already been returned in cash, and how the manager’s edge translates into better entry prices. These questions are standard across the industry and many of them appear in the public due diligence questionnaire of the Institutional Limited Partners Association (ILPA).

Deal screening. I also took part in the early screening of investment opportunities. This meant preparing a founder call: requesting the company’s materials in advance, building a questionnaire and a conversation flow mapped to its pitch deck, and then summarizing the discussion in a preliminary investment memo. Such a memo follows a standard investment committee structure: an executive summary, the business model, the market and competition, the fundraising terms, key strengths and risks, and the points that would require due diligence before any decision. I learned to ask two or three questions per slide, to keep the most important question for the end, and not to discuss ticket sizes (the amount the investor would put in) before the investor has decided whether it is interested. I also joined calls where founders pitched their business to the team. Our questions always came back to the fundamentals: the financial projections and the assumptions behind them, what IRR (internal rate of return, the annual return implied by the timing and size of all the cash flows) and investment multiple (total value returned per dollar invested) an investor could expect under those assumptions, and whether the business could sustain itself over the long term given its historical run rate (current revenue extrapolated over a full year). Details of the opportunities I worked on are confidential, but the exercise taught me how an investor turns a one-hour conversation into a decision document.

Research for the higher-education track. On the higher-education track, I contributed to a series of buyer’s guides that help universities select technology solutions: what problem the solution addresses, which data it relies on, how to evaluate vendors objectively, and which questions to ask before signing a contract. Each guide went through several rounds of feedback on content, grammar and formatting before publication.

Required skills and knowledge

On the technical side, the work required reading fund documents (presentations, track records and portfolio pages), mastering the vocabulary of private markets (commitments (the amounts investors promise to a fund), capital calls (when the fund draws on these commitments), IRR, MOIC (multiple on invested capital) and DPI (distributions to paid-in capital), all explained below), and finding reliable information quickly in free sources such as Crunchbase, Tracxn, fund websites and letters, SEC EDGAR filings (the public database of company filings of the US Securities and Exchange Commission) and industry reports. It also required structured writing: an investment committee reads the conclusion first, so every note had to open with a clear view and then present the evidence.

On the personal side, the most important skill was autonomy. The team was remote and spread across time zones, so I had to manage my own priorities, follow up proactively and take the initiative when an opportunity appeared. Clear written communication over Microsoft Teams and email mattered even more than it would in an office.

What I learned

This internship was something very new to me. Working with a US-based family office was an interesting and unique experience, and at the beginning I was not familiar with much of the terminology: commitments, capital calls, carried interest (the share of profits paid to the fund manager), DPI (distributions to paid-in multiple), TVPI (total value to paid-in capital) and many other terms that the team used every day. I learned them by doing the work, asking questions and reading as much as I could.

First, I learned that investing through funds is a different job from investing in companies. A family office does not only ask “Is this start-up good?” but also “Will this manager keep finding good start-ups, and is the fund structured in my interest?”

Second, I learned to stress the fundamentals. When founders pitched their business, the discussion was never about the story alone: we asked for their financial projections, tested them with IRR and multiples, and compared them with the historical run rate to judge whether the business could last. Working on live opportunities showed me how much a careful background check and a few precise questions can change an investment view.

Third, I learned from the people around me. I worked alongside experienced and knowledgeable colleagues, reviewing opportunities together and sharing research and analysis on each company. I also had great mentors who guided me, gave me detailed feedback and inspired me to raise the quality of my work.

Finally, I learned how much a junior analyst’s contribution depends on initiative. In a remote team, the people who learn the most are those who propose ideas, create their own work and communicate it clearly.

Financial concepts related to my professional experience

I present below three financial concepts related to my professional experience: the limited partner and general partner structure, the performance measures of private funds, and the selection of fund managers.

Limited partners (LPs) and general partners (GPs)

Private equity and venture capital funds are usually organized as limited partnerships. The general partner (GP), or an affiliated management entity, is responsible for managing the fund: it raises the fund, selects and manages the investments, and earns a management fee (often around 2% of commitments per year) and a share of the profits called carried interest (often 20% above a minimum return). The limited partners (LPs), such as pension funds, endowments and family offices, provide most of the capital. An LP typically contributes its committed capital progressively through capital calls: it makes a commitment, which the GP draws through capital calls during the first years of the fund as it finds deals. Cash flows back as distributions when portfolio companies are sold or listed, typically after five to ten years. This commitment structure matters for investors: Gourier, Phalippou and Westerfield (2024) show that the obligation to meet capital calls on demand substantially affects an LP’s optimal portfolio and welfare, and that investors require a premium for bearing this commitment risk. My work at Regarde Familia sat on the LP side of this relationship.

Measuring the performance of a private fund: IRR, TVPI and DPI

Because cash goes in and comes out at different dates, a private fund cannot be judged with a simple return. Three measures are standard.

The internal rate of return (IRR) is the discount rate that sets the net present value of all the LP’s cash flows to zero. It takes timing into account, but it can be flattered by returning cash early.

The total value to paid-in multiple (TVPI), close to the multiple on invested capital (MOIC) reported by many managers, equals distributions plus the remaining value of the portfolio, divided by the capital paid in. It shows how much value has been created per dollar invested, whether realized or not.

The distributions to paid-in multiple (DPI) equals distributions divided by the capital paid in. It only counts cash actually returned, which is why LPs watch it closely: a high TVPI combined with a low DPI means that most of the value is still on paper.

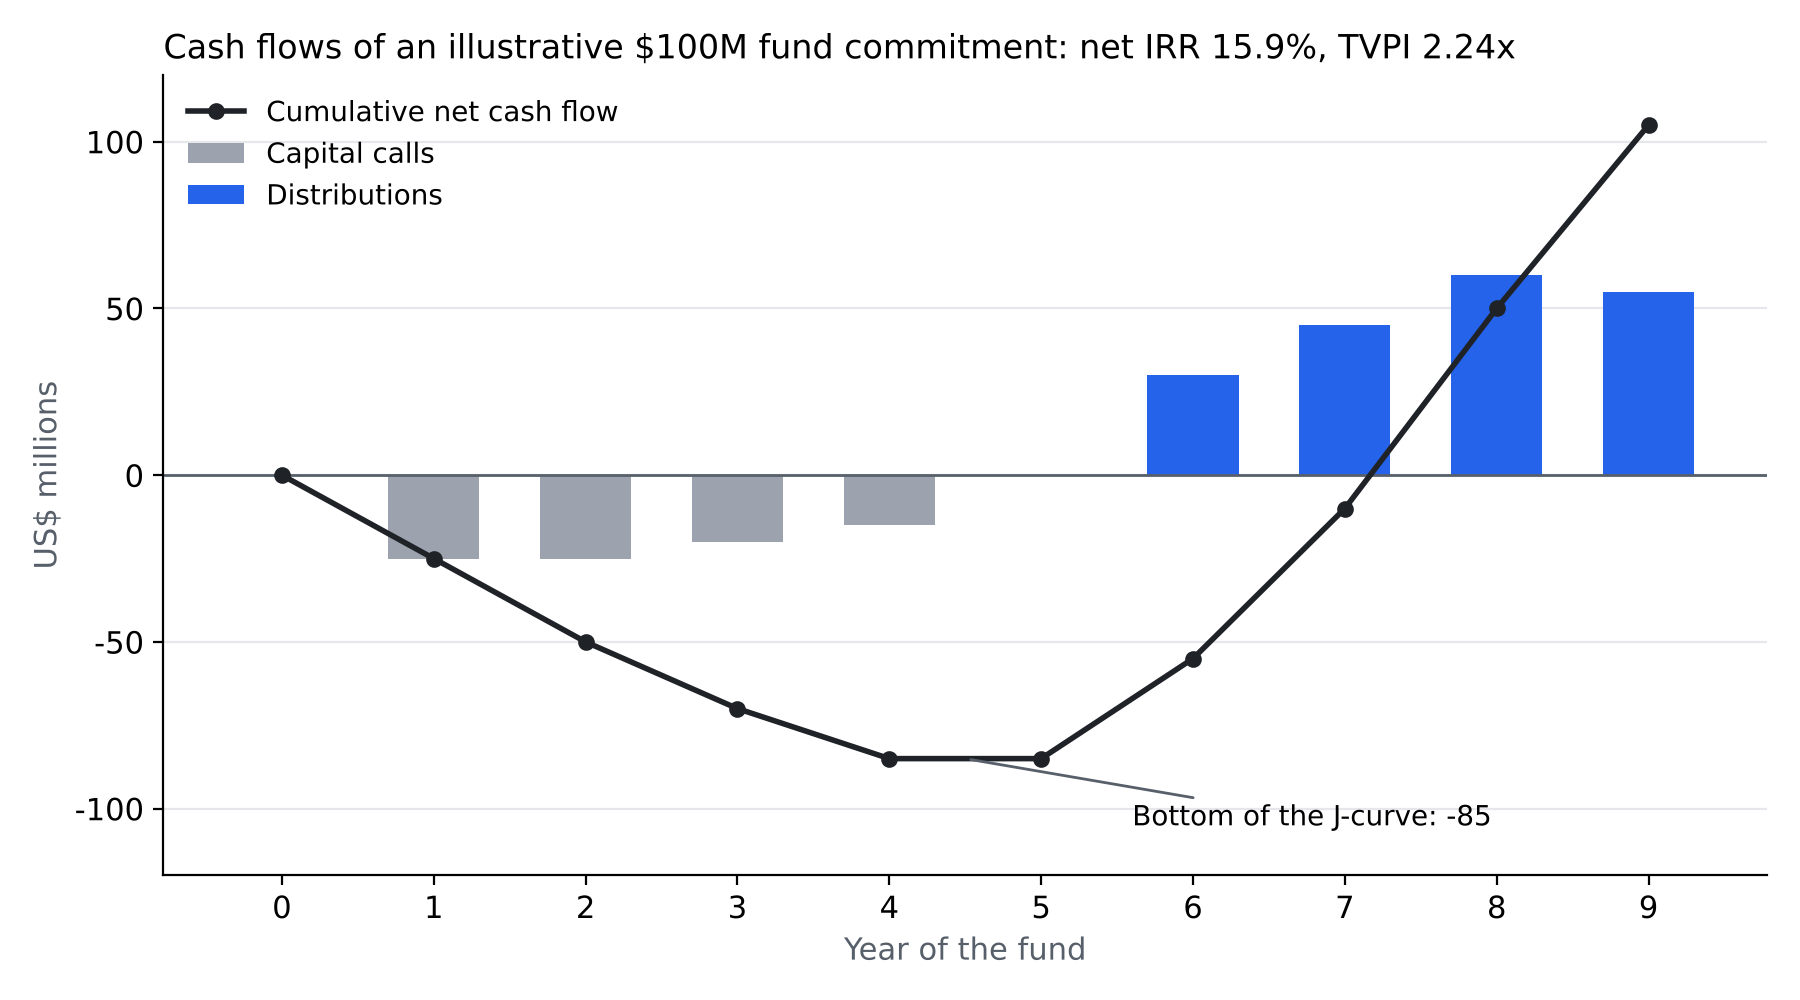
Figure 2 shows an illustrative example that I built. An LP commits 100 million dollars to a fund. The GP calls 85 million over the first four years and returns 190 million between years 6 and 9. The net IRR is 15.9% and the final TVPI is 2.24x. The cumulative cash flow falls to minus 85 million before turning positive in year 8: this is the “J-curve” that every private-market investor has to finance. At the end of year 6, if the remaining portfolio were valued at 95 million, the fund would show a TVPI of 1.47x but a DPI of only 0.35x. All the calculations behind Figure 2 are in the Excel file below, which also shows how DPI, RVPI and TVPI change each year.

Figure 2. Cash flows of an illustrative fund commitment and the J-curve.
J-curve of an illustrative fund commitment
Source: computation by the author (illustrative figures), Excel file below (sheets ‘Parameters’, ‘Computations’ and ‘Figure J-curve’).

This is why an allocator’s questions focus on how returns are split between realized and unrealized value, and between a few outlier deals and the rest of the portfolio.

Download the Excel file with J curve example for private equity

Manager selection and the persistence of returns

For an LP, the most important decision is which manager to back, and academic research explains why. Kaplan and Schoar (2005) documented persistence in private equity fund performance in their sample: GPs whose previous funds outperformed tend to outperform again, which is unusual in asset management. Harris, Jenkinson and Kaplan (2014) found that buyout funds have, on average, outperformed public markets, with large differences between managers. In venture capital, returns are concentrated in a small number of very large successes, so the gap between top and average funds is wide. Gompers, Gornall, Kaplan and Strebulaev (2020) surveyed venture capitalists and found that the quality of the management team is the factor they rank first when selecting deals. In my work, this translated into one simple rule: look for evidence that a manager’s process, not luck, produced the past results, through portfolio construction, sector conviction and access to the best founders.

Why should I be interested in this post?

If you are interested in private equity or venture capital, most of what you read describes the job of the fund manager. This post describes the other side of the table: the investor who chooses the fund managers. Family offices, endowments and pension funds hire analysts to do exactly this work, and the skills involved (building sector theses, assessing funds and measuring performance) are equally valuable if you later want to join a fund. The post also shows that a student can gain meaningful exposure to private markets through a remote internship, provided that the selection work is strong and that you take the initiative once you join.

Related posts on the SimTrade blog

Professional experiences

   ▶ All posts about Professional experiences

   ▶ Adam MERALLI BALLOU My internship experience in Investor Relation at Eurazeo

   ▶ Jules HERNANDEZ My internship experience in a Multi-Family Office

   ▶ Dante MARRAMIERO My Experience as an Investment Intern at Eurazeo

   ▶ Alberto BORGIA My Experience as a Wealth Management Intern at Nextam Partners

Private Equity

   ▶ Lilian BALLOIS Discovering Private Equity: Behind the Scenes of Fund Strategies

   ▶ Adam MERALLI BALLOU The Private Equity Secondary Market: from liquidity mechanism to structural pillar

   ▶ Matisse FOY Key participants in the Private Equity ecosystem

   ▶ Dante MARRAMIERO Structured Debt in Private Equity: Rated Feeder Funds and Collateral Fund Obligations

   ▶ Ian DI MUZIO Leverage in LBOs: How Debt Creates and Destroys Value in Private Equity Transactions

Financial techniques

   ▶ All posts about Financial techniques

   ▶ Raphaël ROERO DE CORTANZE The Internal Rate of Return

Useful resources

Academic research

Gompers, P. A., Gornall, W., Kaplan, S. N., Strebulaev, I. A. (2020). How do venture capitalists make decisions? Journal of Financial Economics, 135(1), 169-190.

Gourier, E., Phalippou, L., Westerfield, M. M. (2024). Capital Commitment. Journal of Finance, 79(5), 3407-3457.

Harris, R. S., Jenkinson, T., Kaplan, S. N. (2014). Private Equity Performance: What Do We Know? Journal of Finance, 69(5), 1851-1882.

Kaplan, S. N., Schoar, A. (2005). Private Equity Performance: Returns, Persistence, and Capital Flows, Journal of Finance, 60(4), 1791-1823.

Business resources

Regarde Familia

Institutional Limited Partners Association (ILPA), Performance Template Guidance (2025)

Institutional Limited Partners Association (ILPA), Due Diligence Questionnaire

Congruent Ventures, Fund III announcement

About the author

The article was written in November 2026 by Aarichsun BATLISH (Indian Institute of Technology Kanpur, B.Tech in Civil Engineering, 2024-2028).

Aarichsun is interested in quantitative finance, financial economics and private markets. After his studies at IIT Kanpur, he plans to pursue a master’s degree, and possibly a PhD, in quantitative finance.

   ▶ Discover all posts by Aarichsun BATLISH.

My experience as an independent portfolio manager of a family-funded equity and derivatives portfolio

Romil SOJITRA

In this article, Romil SOJITRA (Indian Institute of Technology Kanpur, BS in Economics, 2024-2028) shares his experience as an independent portfolio manager of a family-funded equity and derivatives portfolio in the Indian market, which he started with equities in May 2025 and extended to options in May 2026.

About the market: Indian equity derivatives

My portfolio was invested in Indian listed equities and in equity derivatives (futures and options) traded on the National Stock Exchange of India (NSE). NSE was founded in 1992 and introduced fully electronic, screen-based trading in India. It launched futures on the Nifty 50 index in 2000 and options in 2001. Since then, the Indian equity derivatives market has grown enormously. According to the Futures Industry Association (FIA), NSE was the largest derivatives exchange in the world by number of contracts traded for five consecutive years (2019 to 2023), mainly because of very high volumes in options on the Nifty 50 and Nifty Bank indexes with weekly expiries, that is, contracts that expire within seven days or less and that are heavily traded in the last days before expiry.

Logo of the National Stock Exchange of India (NSE).
Logo of NSE
Source: the company.

This growth came with risks for individual investors. In September 2024, the Securities and Exchange Board of India (SEBI), the market regulator, published a study showing that 93% of individual traders in equity futures and options made losses between FY22 and FY24 (in India, the fiscal year runs from April to March, so the study covers April 2021 to March 2024). Their aggregate net losses reached ₹1.81 lakh crore over the three years (1 lakh = 100,000 and 1 crore = 10 million, so 1 lakh crore = ₹1 trillion), that is about ₹1.8 trillion or roughly US$21 billion, and most of these losses came from options.

SEBI reacted to these losses. Because most losses were concentrated among small traders buying and selling short-dated index options, its circular of October 1, 2024 (applied from November 20, 2024) made this type of speculation harder: the minimum value of an index derivative contract was raised from ₹5-10 lakh to ₹15 lakh, so that each trade requires more capital, and each exchange may now offer weekly expiries on only one benchmark index (the Nifty 50 for NSE), which reduces the number of very short-dated contracts. These rules also mattered for my own sizing: one lot of a Nifty option now represents a notional amount of at least ₹15 lakh, so I could not size positions as finely as I wanted. I therefore started trading derivatives knowing that most individual participants lose money. My objective was not to “beat the market” quickly, but to build a process that controls risk first.

The portfolio was funded by my family. They gave me capital to manage after I had shown consistent results on a smaller amount. This made me accountable to real “clients”, even though they were family members: I reported my performance to them regularly and explained my decisions and my mistakes.

My experience

I started in May 2025 with Indian equities, investing in stocks and learning how markets work alongside my studies at IIT Kanpur. In May 2026, I moved to a more structured and quantitative approach: I added options trading and began applying the concepts presented in this article (the Black-Scholes-Merton model and the Greeks, the Kelly Criterion, Monte Carlo simulations) to a leveraged equity and derivatives portfolio. This post focuses mainly on this second phase, from May to August 2026 (44 trading sessions), and on the drawdown of March-April 2026 that came just before it. I am responsible for the full investment process: generating ideas, building positions, sizing them, hedging the portfolio, and measuring and reporting performance.

My missions

Since May 2026, when I added options to the portfolio, my work has covered the five areas below. The first one (relative-value equity positions) continued the equity book I had run since May 2025; the four others were new.

Building relative-value positions. I constructed long/short equity pairs: buying one stock and selling a related stock (for example, two companies in the same sector) to be exposed to their relative performance rather than to the direction of the overall market. When a pair is well built, a large part of the market risk cancels out, and the return depends on the spread between the two stocks.

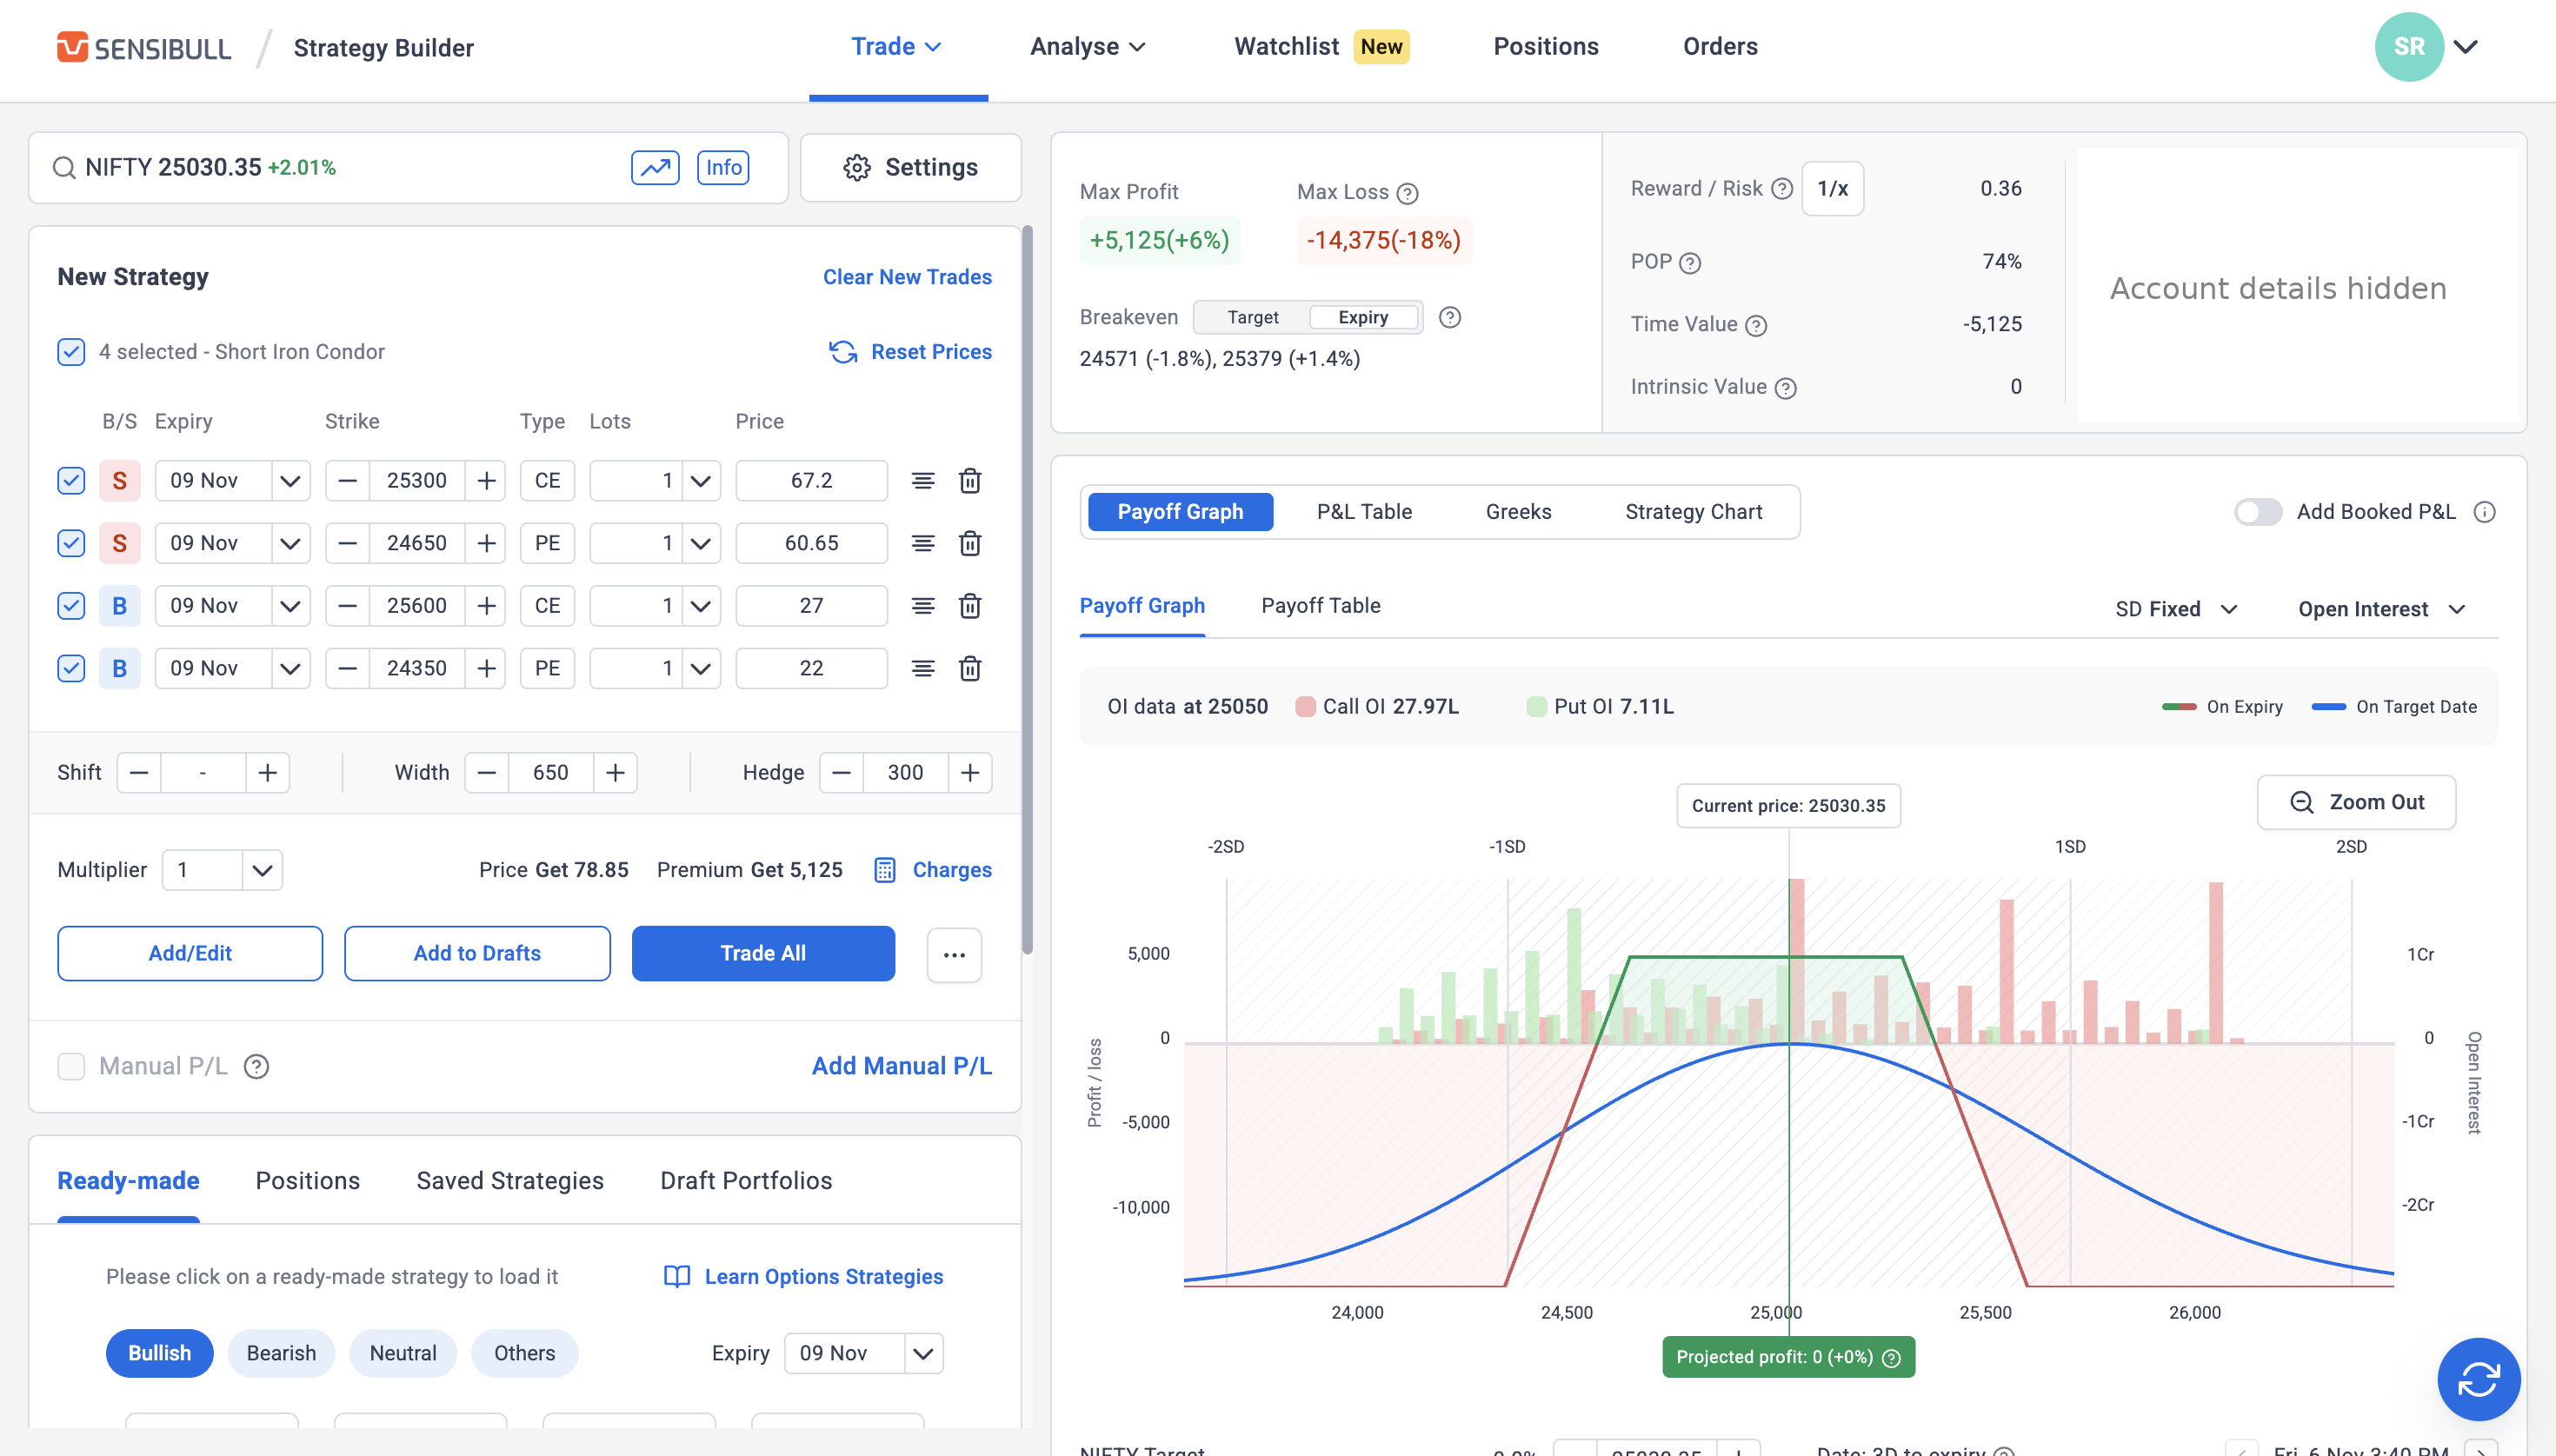
Running delta-neutral option positions. My option positions were mainly short volatility: I sold Nifty index options (for example a call and a put together, as in a short strangle) and kept the delta of the whole position close to zero by adjusting it with Nifty futures or by moving one of the option legs. Each position was therefore a combination of options and of the underlying (through futures), not options alone. Small moves of the index then had little impact, and the profit or loss came from two other sources. The first is time decay (theta): an option loses a little value every day as expiry approaches, and as a seller I earned this decay. The second is volatility. As a seller, I lost money when the volatility implied by option prices rose (negative vega), and above all I earned money when the index actually moved less than the volatility implied by the prices at which I sold the options, and lost money when it moved more (negative gamma). I explain this mechanism with an equation in the section on the Greeks below. I used Sensibull, an Indian options analytics platform, to analyze option chains, Greeks and the payoff of each strategy before entering a position. Figure 1 illustrates this analysis on an example: a short iron condor on the Nifty 50 (selling the 24,650 put and the 25,300 call, and buying the 24,350 put and the 25,600 call as protection), whose maximum loss is capped at the width of a wing (300 points) minus the net premium received (78.85 points).

Figure 1. Illustration: payoff of a short iron condor on the Nifty 50 in the Sensibull strategy builder (expiry of November 9, 2026).
Analysis of an option position on Sensibull
Source: Sensibull, screenshot by the author (illustration, November 6, 2026).

Hedging tail risk. Short-volatility and leveraged positions can lose a lot of money in a market crash. To protect the portfolio against extreme events, I held a long-dated index put option as a tail-risk hedge. This hedge costs a small premium in normal times but gains value when the market falls sharply. A bought put has positive gamma: its delta becomes more and more negative as the market falls, so its gains accelerate in a crash. It therefore offsets part of the negative gamma of the options I sold.

Sizing positions and modelling risk. I used the Kelly Criterion to decide how much capital to allocate to each trade, the Black-Scholes-Merton model to price options and compute their Greeks, and correlation and information-ratio analysis to build the portfolio. I also built Monte Carlo simulations. For position sizing, each session is a random draw: a win with probability p = 59.1% that pays b = 1.45 times the average loss, or a loss otherwise. I simulated 10,000 paths of 100 sessions for different bet sizes (this model is detailed in my article on the Kelly Criterion). For option positions, I simulated the Nifty 50 with a geometric Brownian motion, the model behind Black-Scholes-Merton, for several levels of annual volatility (for example 10%, 15% and 25%), and revalued the position on each simulated path.

Measuring and reporting performance. I kept a structured trading journal and a performance report. I tracked the win rate, the profit factor (gross profits divided by gross losses), the Sharpe, Sortino and Calmar ratios, and the drawdown, for each account and each strategy.

Required skills and knowledge

Hard skills. I needed a solid understanding of derivatives: how futures and options are priced (a futures price follows the cost-of-carry relation F = S × e(r − q)T, where S is the spot price, r the interest rate, q the dividend yield and T the maturity, while options are priced with the Black-Scholes-Merton model presented below), what the Greeks measure, and how a combination of options behaves when the price, volatility or time to maturity changes. I also needed statistics and econometrics to measure correlations and evaluate whether a strategy has a real edge or is just lucky. The courses I took at IIT Kanpur in econometrics, financial econometrics and optimization, and my preparation for the CFA Level I exam (which I passed in August 2026), were very useful here.

Soft skills. The most important skills were discipline and emotional control. It is easy to follow rules when trades are winning; it is much harder during a drawdown, when the temptation is to increase risk to recover losses quickly. Behavioral finance explains why. In prospect theory, Kahneman and Tversky (1979) show that people feel a loss more strongly than a gain of the same size (roughly twice as strongly) and become risk-seeking when they are below their reference point: after a loss, a trader is tempted to take more risk to get back to break-even. Kahneman (2011) adds that under stress, fast and intuitive thinking takes over from slow and deliberate thinking. This is why I relied on a written process and on my trading journal, not on my feelings, during the drawdown. I also needed honesty and communication skills to report bad periods to my family as clearly as good ones.

What I learned

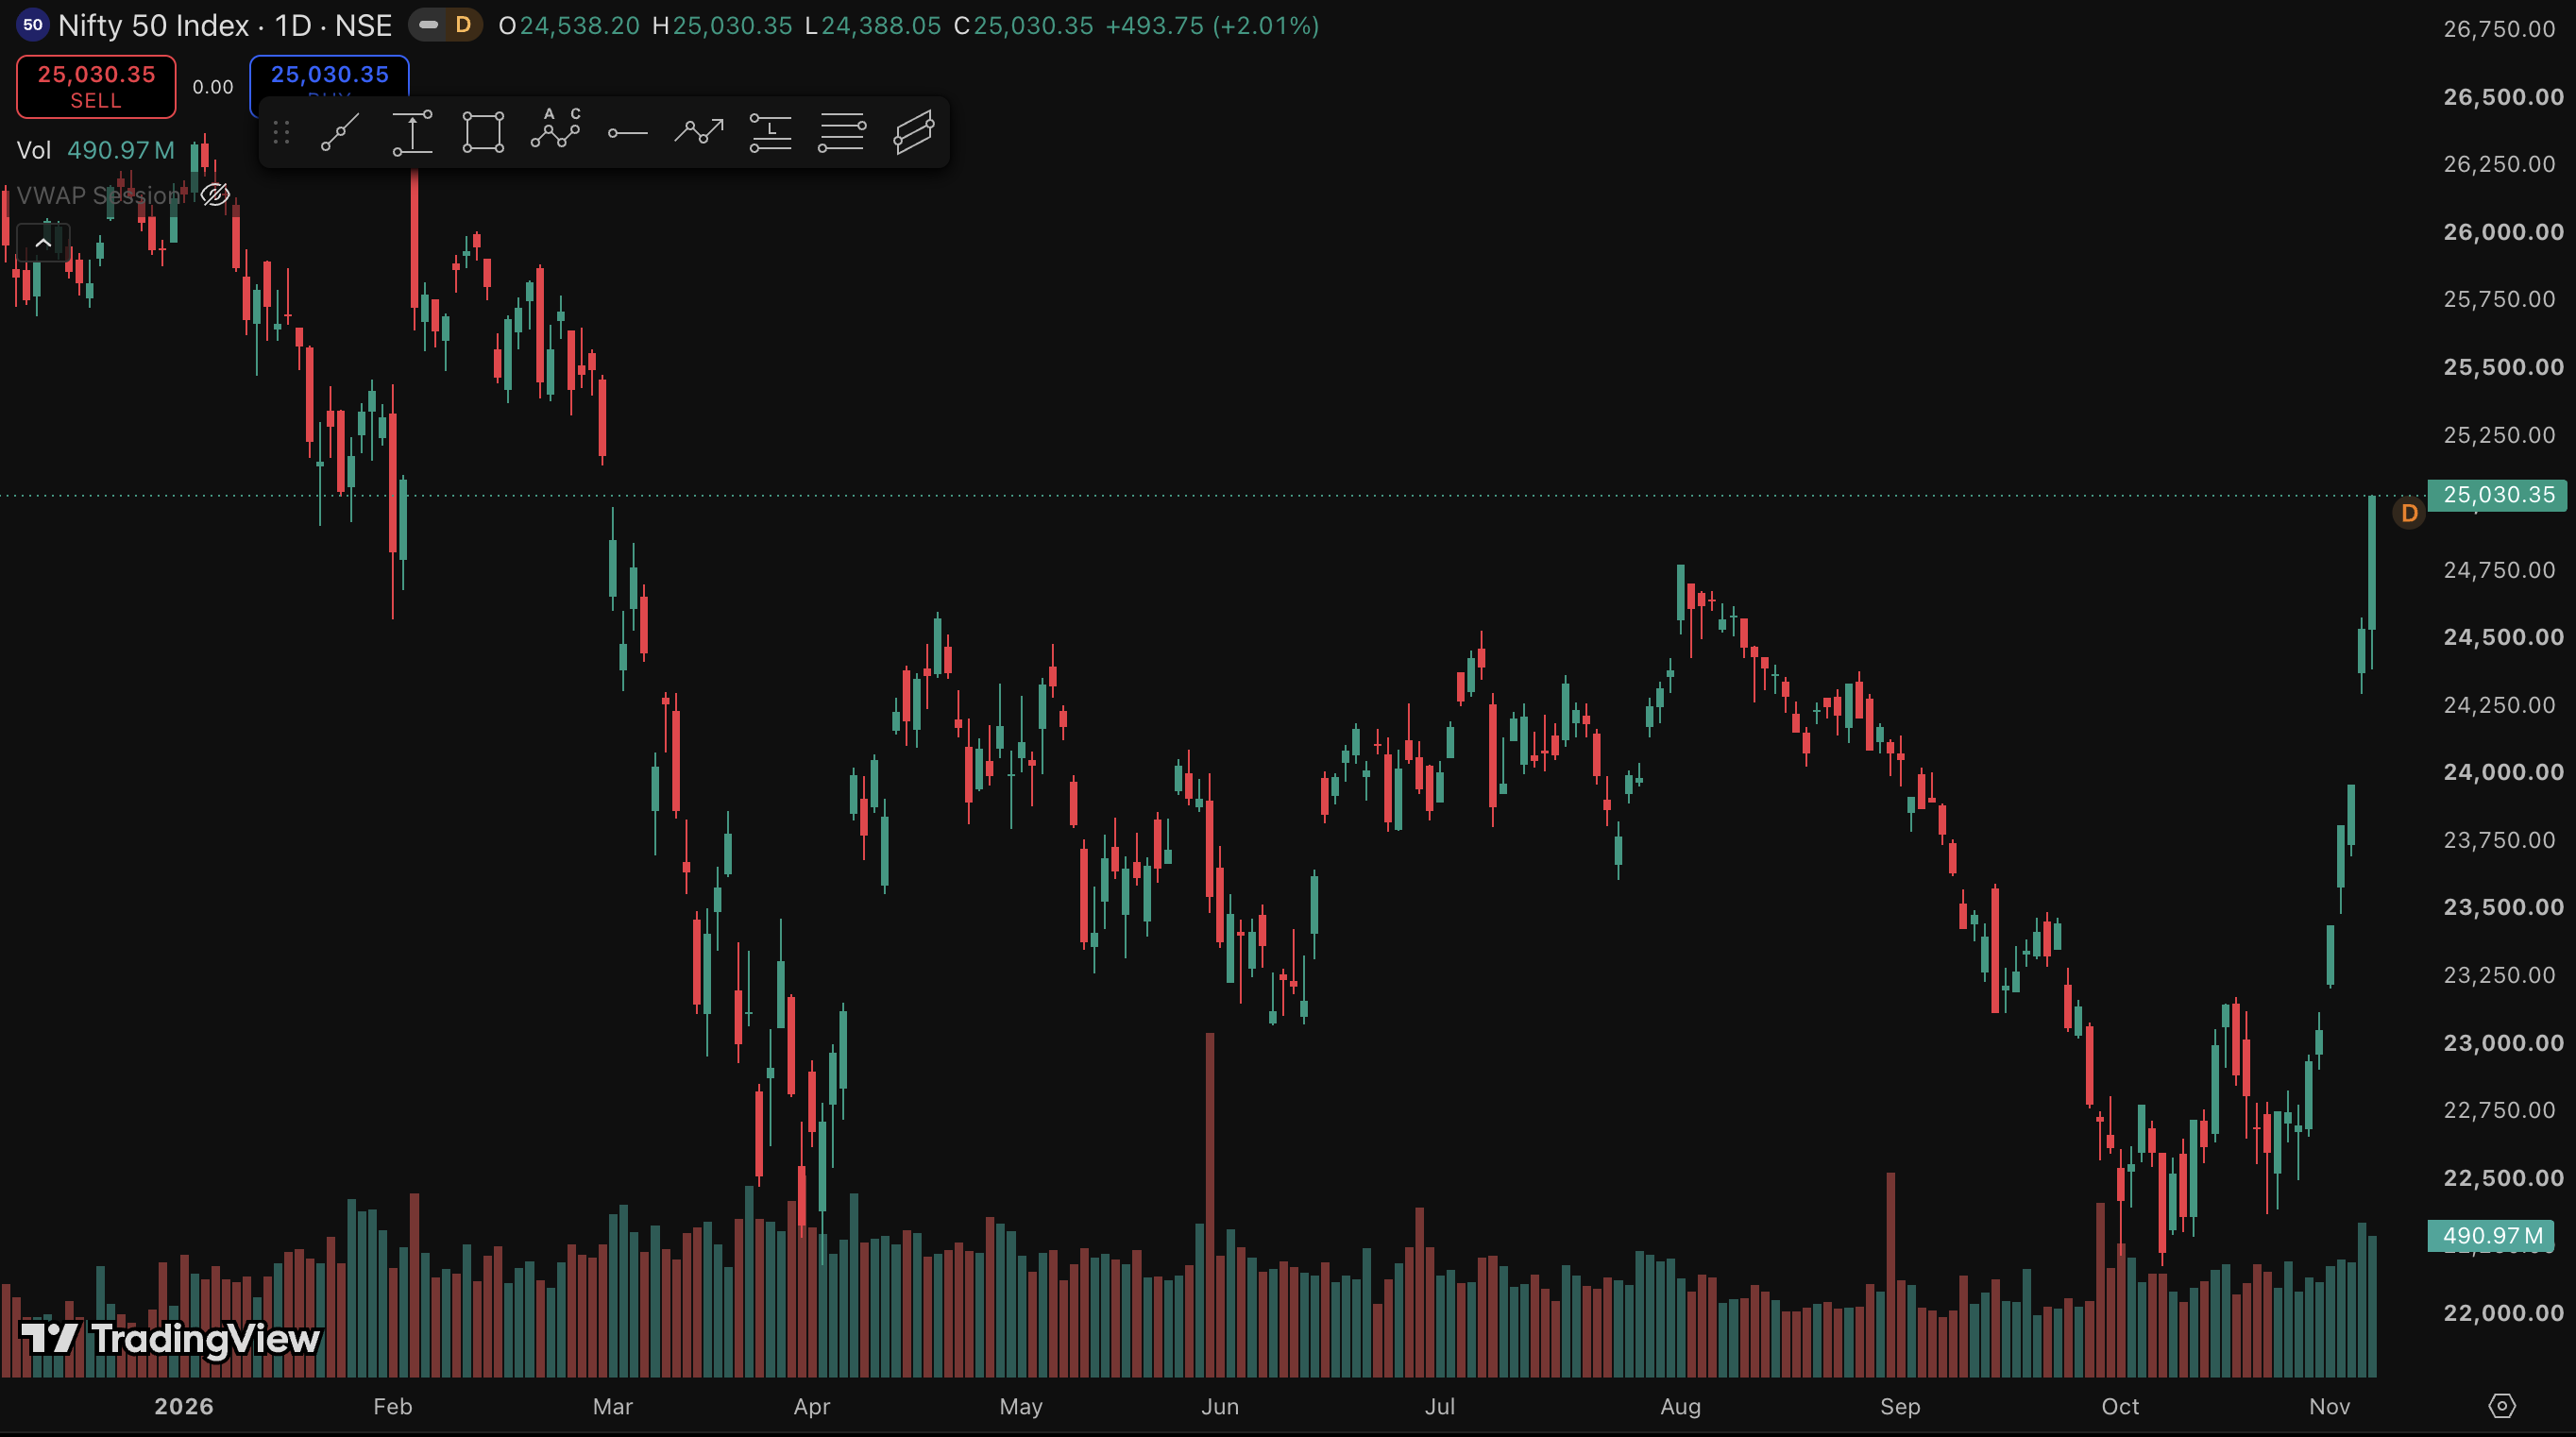
The most important lesson came from a difficult period. During the market sell-off of March-April 2026, linked to the US-Iran conflict, my portfolio suffered a heavy drawdown, mainly on high-beta stocks in my equity book (Figure 2). I had underestimated how much my positions were exposed to the same market factor, that is, the general movement of the Indian equity market measured by the Nifty 50. High-beta stocks amplify the moves of the index (a stock with a beta of 1.5 tends to fall by about 1.5% when the index falls by 1%), so in a sell-off they all fall together and their correlations rise: positions that looked different were in fact the same bet on the market. I did not try to win everything back at once. I reduced risk, kept following my process, and the portfolio recovered and became profitable over the following two months.

Figure 2. Evolution of the Nifty 50 index in 2026 (daily prices, January to early November).
Evolution of the Nifty 50 index in 2026
Source: TradingView (data: NSE).

Table 1 summarizes the performance of the portfolio over May-August 2026. A session is a trading day on which I had open positions and recorded a profit or a loss in my journal: there were 44 such sessions over the period. The portfolio delivered a return of 5.79% on deployed capital and 4.05% on total capital (part of the capital stayed in cash as a buffer). Of the 44 sessions, 26 were winners and 18 were losers, which gives a win rate of 59.1% (26/44). The profit factor (gross profits divided by gross losses) was 2.10, so the average winning session earned about 1.45 times what the average losing session lost (2.10 × 18/26). Figure 3 shows the evolution of the portfolio and its drawdown.

Table 1. Performance of the portfolio (May-August 2026).

MeasureValueHow it is computed
Trading sessions44Days with open positions
Winning / losing sessions26 / 18From the trading journal
Win rate (p)59.1%26 / 44
Profit factor2.10Gross profits / gross losses
Payoff ratio (b)1.45Average win / average loss = 2.10 × 18/26
Return on deployed capital5.79%Profit / capital in positions
Return on total capital4.05%Profit / total capital
Average share of capital deployedabout 70%4.05% / 5.79%

Source: trading journal of the author.

Figure 3. Evolution of the portfolio and drawdown (May-August 2026).
Evolution of the portfolio and drawdown
Source: computation by the author (data: trading journal).

In July-August, a second drawdown appeared. My journal showed that my edge was decaying: the same strategies were producing weaker results. I decided to de-risk rather than force trades. I learned that knowing when to reduce exposure is as important as knowing when to take risk, and that a strategy’s edge is not permanent.

Financial concepts related to my experience

I present below three financial concepts related to my experience: the Black-Scholes-Merton model and the option Greeks (with an equation that shows how my option positions made or lost money, and alternative ways to bet on volatility), the Kelly Criterion for position sizing, and risk-adjusted performance measures.

The Black-Scholes-Merton model and the option Greeks

The Black-Scholes-Merton model (Black and Scholes, 1973; Merton, 1973) gives a theoretical price for a European option as a function of the price of the underlying asset, the strike price, the time to maturity, the risk-free interest rate and the volatility of the underlying. Its partial derivatives, called the Greeks, measure how the option price reacts to each of these inputs: delta (price of the underlying), gamma (change in delta), vega (implied volatility), and theta (time). In my delta-neutral strategies, I kept the delta of the whole position close to zero, that is, the sum of the deltas of all the options and futures in the position, each multiplied by its quantity: Δposition = Σ ni × Δi (a future has a delta of 1 per unit of the index). Small market moves then had little impact. My profit or loss came mainly from theta and gamma, that is, from the passage of time and from the difference between implied and realized volatility, as the equation below shows. Without the model and its Greeks, I could not have measured or controlled these exposures.

The profit and loss of an option position: a second-order approximation

For a small change dS in the price of the underlying asset over a short period dt, a second-order Taylor expansion of the value V of an option position gives:

dV ≈ Δ × dS + ½ × Γ × (dS)2 + Θ × dt + ν × dσ

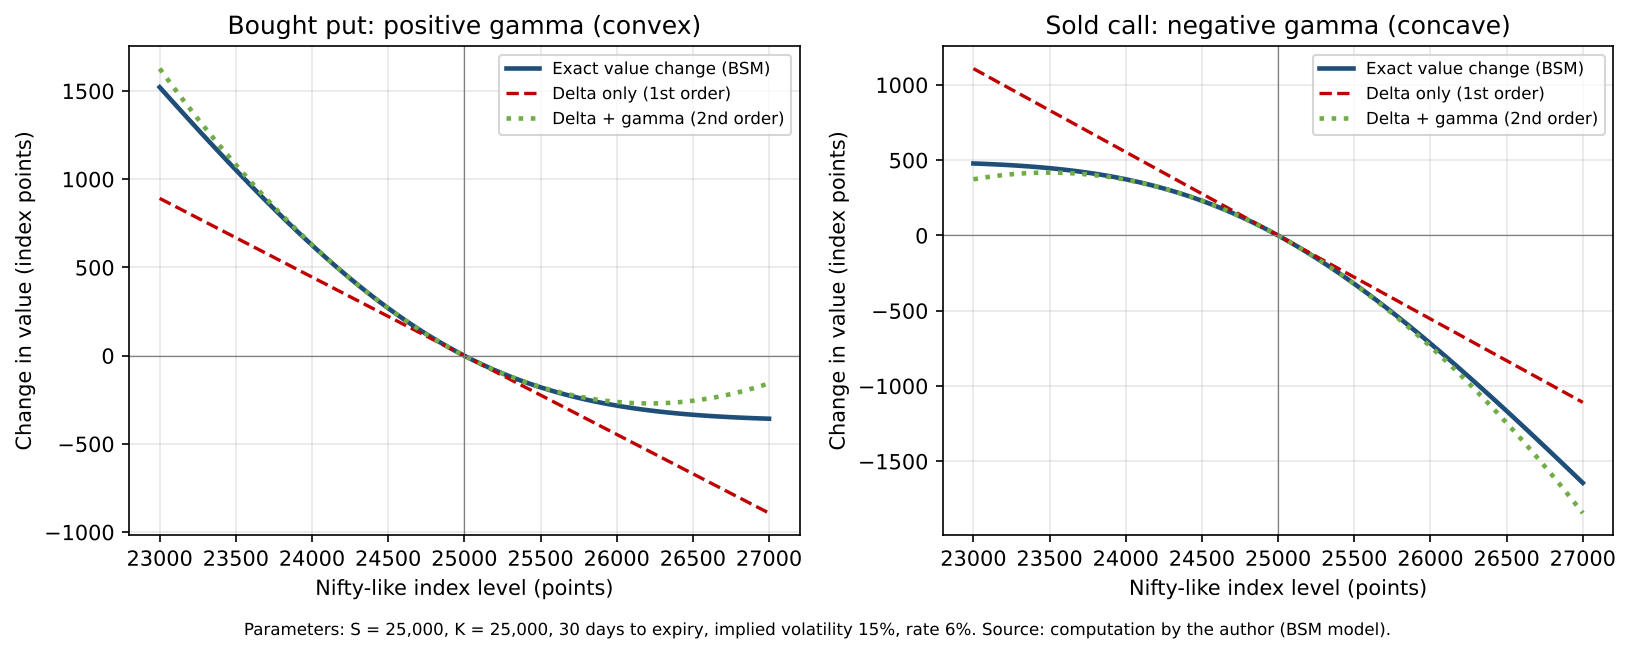
where Δ is the delta, Γ the gamma, Θ the theta and ν the vega of the position. The first term is linear: it is the first guess given by the delta. The second term is the convexity. It does not depend on the direction of the move because (dS)2 is always positive: for a bought option (Γ > 0, for example the purchase of a put) it is always a gain, and for a sold option (Γ < 0, for example the sale of a call) it is always a loss.

For a delta-neutral position (Δ = 0) with constant implied volatility, only gamma and theta remain. In the Black-Scholes-Merton model, theta and gamma are linked: when the interest rate is ignored, Θ = −½ × Γ × S2 × σimplied2. The profit and loss over one day can then be written as:

dV ≈ ½ × Γ × S2 × [ (dS/S)2 − σimplied2 × dt ]

The term (dS/S)2 is the squared return actually realized over the day, while σimplied2 × dt is the squared return implied by option prices. For a seller of options (Γ < 0), the day is profitable when the market moves less than implied volatility predicts, and costly when it moves more. Over many days, the seller earns money when realized volatility is below implied volatility. This is the precise meaning of “betting on volatility”, and it explains the returns of my delta-neutral positions. Empirically, implied volatility is on average higher than realized volatility on equity indexes (the volatility risk premium documented by Bakshi and Kapadia, 2003), which is what option sellers try to earn, at the cost of large losses in sudden market moves.

Figure 4 illustrates the convexity with two positions on an index at 25,000 points: the purchase of an at-the-money put (positive gamma) and the sale of an at-the-money call (negative gamma), both with 30 days to expiry, an implied volatility of 15% and an interest rate of 6% (illustrative parameters). The gamma of each option is 0.000368 per point. For a fall of 2,000 points (−8%), the bought put gains 1,522 points: the delta alone predicts 892 points, and adding the gamma term (+735 points) gives 1,627 points, much closer to the exact value. For moves of ±500 points (±2%), the second-order approximation is almost exact (269 points for the bought put after a fall of 500 points, against 269 points with the full model). The curve of the bought put bends upward (convex), while the curve of the sold call bends downward (concave): for a rise of 2,000 points, the sold call loses 1,643 points against 1,108 points predicted by the delta alone.

Figure 4. Change in value of a bought put and of a sold call as a function of the price of the underlying asset.
Change in value of a bought put and of a sold call as a function of the underlying price
Source: computation by the author (Black-Scholes-Merton model).

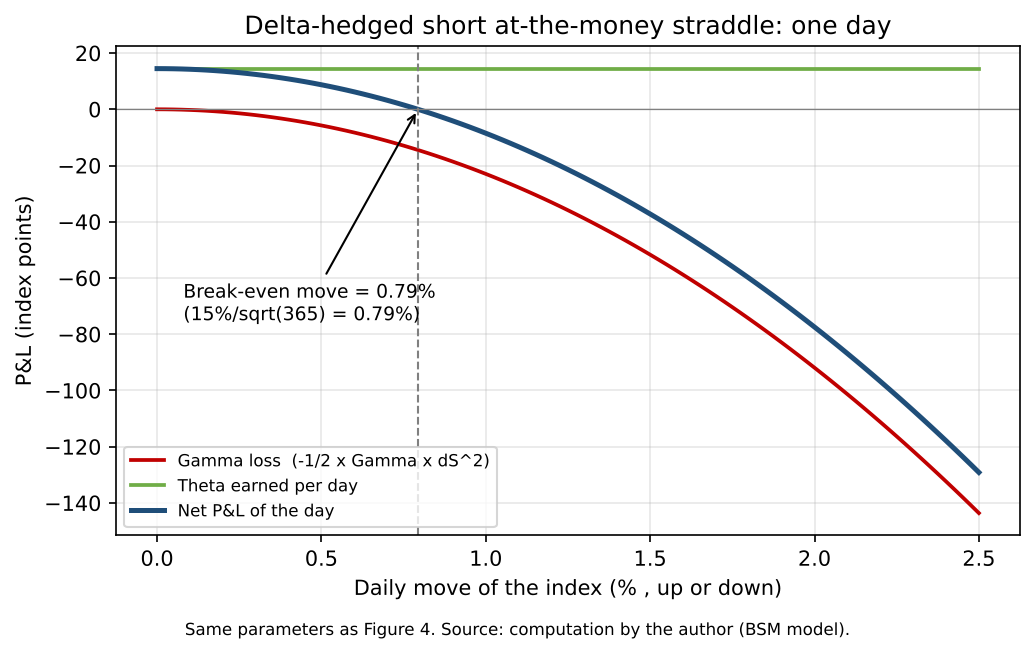
Figure 5 applies the second equation to a delta-hedged short at-the-money straddle (one call and one put sold with the same strike) with the same parameters. The position earns about 14.5 points of theta per day but loses ½ × Γ × (dS)2 when the index moves. The break-even daily move is about 198 points, or 0.79% of the index, which is almost exactly the daily move implied by an annual volatility of 15% (15% / √365 = 0.79%).

Figure 5. Profit and loss over one day of a delta-hedged short straddle as a function of the daily move of the index.
Daily profit and loss of a delta-hedged short straddle
Source: computation by the author (Black-Scholes-Merton model).

You can download below the Excel file with the tables and figures of this section (option prices and Greeks, the position as a function of the price of the underlying asset for a bought put and a sold call, the gamma-theta trade-off, and the payoffs of volatility strategies).

Download the cleaned S&P 500 index options data

Alternative strategies to bet on volatility

Selling options is only one way to take a view on volatility. Table 2 lists the main alternatives. Long-volatility strategies (positive gamma) gain when the market moves a lot and pay theta every day; short-volatility strategies (negative gamma) earn theta and lose in large moves.

Table 2. Strategies to bet on volatility.

StrategyPositionBetGammaMaximum loss
Long straddle / strangleBuy a call and a put (same strike, or out-of-the-money strikes)Large move in either direction+Premiums paid
Delta-hedged long options (gamma scalping)Buy options and re-hedge the delta with futuresRealized volatility above implied volatility+Premium paid and hedging costs
Long out-of-the-money put (tail hedge)Buy a long-dated index putMarket crash+Premium paid
Short straddle / strangleSell a call and a putCalm market, realized volatility below implied−Unlimited
Iron condorShort strangle plus a bought put and a bought call further out of the moneyIndex stays within a range−Width of the wings minus premium received
Calendar spreadSell a short-dated option and buy a longer-dated one with the same strikeCalm market now, stable or rising long-dated implied volatility−Net premium paid
Volatility index and variance productsTrade volatility directly (India VIX for NSE, variance swaps)Rise or fall of volatility itselfn/aDepends on the product (variance swaps are mainly traded by institutions)

Source: the author.

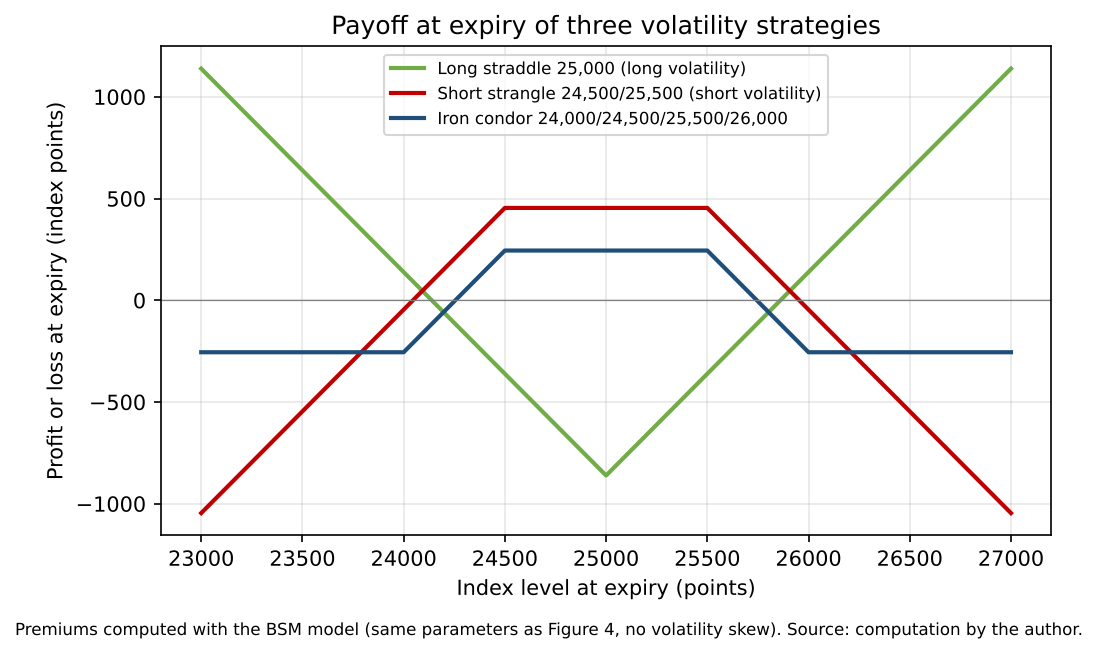
Figure 6 compares the payoff at expiry of a long straddle, a short strangle and an iron condor with the same parameters as above. The iron condor is a defined-risk version of the short strangle: with strikes at 24,000, 24,500, 25,500 and 26,000 points, it collects a net premium of 245 points and its maximum loss is capped at 255 points (the 500-point width of a wing minus the premium), whereas the loss of the short strangle has no limit. Defined-risk structures are therefore better suited to a small portfolio, where one large move must not wipe out months of theta.

Figure 6. Payoff at expiry of three volatility strategies.
Payoff at expiry of three volatility strategies
Source: computation by the author (Black-Scholes-Merton model).

The Kelly Criterion

The Kelly Criterion (Kelly, 1956) answers the question: if I have a positive edge, what fraction of my capital should I risk on each trade? It chooses the fraction that maximizes the expected logarithm of wealth, which is the same as maximizing the long-run growth rate of capital. For a trade that wins with probability p and pays b times the amount risked, the optimal fraction is f* = p − (1 − p)/b. Risking more than this lowers long-run growth and greatly increases drawdowns. I used the Kelly Criterion as an upper limit for my position sizes and in practice risked only a fraction of it, because my estimates of p and b were based on a limited number of trades. I explain this concept in detail in a separate article on the SimTrade blog.

Risk-adjusted performance measures

A return figure alone says nothing about the risk taken to obtain it. The Sharpe ratio (Sharpe, 1966) divides the excess return over the risk-free rate by the volatility of returns. The Sortino ratio (Sortino and Price, 1994) only penalizes downside volatility, which is more relevant for strategies with asymmetric returns such as options strategies. The Calmar ratio compares the annual return to the maximum drawdown, the largest fall from a peak to a trough. I tracked all three measures in my journal because they tell different stories: my drawdown in March-April 2026 hurt my Calmar ratio much more than my Sharpe ratio, which reminded me that volatility is not the only dimension of risk.

Why should I be interested in this post?

If you are a student interested in asset management, trading or derivatives, managing a real portfolio, even a small one, is one of the best ways to understand how theory meets practice. Concepts such as the Greeks, position sizing and drawdowns become very concrete when your own money, or your family’s, is at stake. This experience also shows that a good trading process is mostly about risk management, record-keeping and honest evaluation of performance, and that most individual derivatives traders lose money if they ignore these principles.

Related posts on the SimTrade blog

Professional experiences

   ▶ All posts about Professional experiences

   ▶ Youssef LOURAOUI My experience as a portfolio manager in a central bank

   ▶ William ARRATA My experiences as Fixed Income portfolio manager then Asset Liability Manager at Banque de France

   ▶ Adam MERALLI BALLOU My internship experience in Portfolio Management at Mirabaud

   ▶ Tanguy TONEL My experience as an Investment Specialist at Amundi Asset Management

   ▶ Alberto BORGIA My Experience as a Wealth Management Intern at Nextam Partners

Financial techniques

   ▶ Jayati WALIA Black-Scholes-Merton option pricing model

   ▶ Akshit GUPTA Option Greeks – Gamma

   ▶ Abel ARAYA Delta Hedging Explained: How Traders Stay Market Neutral

   ▶ Akshit GUPTA Straddle and strangle strategy

   ▶ Akshit GUPTA Protective Put

   ▶ Raphael TRAEN Understanding Correlation in the Financial Landscape: How It Drives Portfolio Diversification

Indian financial markets

   ▶ Nithisha CHALLA The Nifty 50 index

   ▶ Nithisha CHALLA Securities and Exchange Board of India (SEBI)

   ▶ Nithisha CHALLA Top 5 companies by market capitalization in India

Useful resources

Academic research

Bakshi, G., Kapadia, N. (2003) Delta-Hedged Gains and the Negative Market Volatility Risk Premium, Review of Financial Studies, 16(2), 527–566.

Black, F., Scholes, M. (1973) The Pricing of Options and Corporate Liabilities, Journal of Political Economy, 81(3), 637–654.

Gatev, E., Goetzmann, W. N., Rouwenhorst, K. G. (2006) Pairs Trading: Performance of a Relative-Value Arbitrage Rule, Review of Financial Studies, 19(3), 797–827.

Hull, J. C. (2021) Options, Futures, and Other Derivatives, Eleventh Edition, Harlow, Pearson.

Kahneman, D. (2011) Thinking, Fast and Slow, New York, Farrar, Straus and Giroux.

Kahneman, D., Tversky, A. (1979) Prospect Theory: An Analysis of Decision under Risk, Econometrica, 47(2), 263–291.

Kelly, J. L. (1956) A New Interpretation of Information Rate, Bell System Technical Journal, 35(4), 917–926.

Merton, R. C. (1973) Theory of Rational Option Pricing, Bell Journal of Economics and Management Science, 4(1), 141–183.

Sharpe, W. F. (1966) Mutual Fund Performance, Journal of Business, 39(1), 119–138.

Sortino, F. A., Price, L. N. (1994) Performance Measurement in a Downside Risk Framework, Journal of Investing, 3(3), 59–64.

Business resources

National Stock Exchange of India (NSE)

SEBI (2024) Updated SEBI study reveals 93% of individual traders incurred losses in equity F&O between FY22 and FY24

SEBI (2024) Circular of October 1, 2024: Measures to strengthen Equity Index Derivatives framework for increased investor protection and market stability.

Futures Industry Association (FIA)

CFA Institute

Sensibull

About the author

The article was written in October 2026 and revised in November 2026 by Romil SOJITRA (Indian Institute of Technology Kanpur, BS in Economics, 2024-2028).

   ▶ Discover all posts by Romil SOJITRA.

My professional experience at Tea Ideas: redesigning a social enterprise café in Singapore

Arjun KODAPPULLY

In this article, Arjun KODAPPULLY (ESSEC Business School, Global Bachelor in Business Administration (GBBA), 2024-2028) shares his professional experience as an operations and business development intern at Tea Ideas, a Singapore social enterprise that runs the Sippy Mug cafés. He explains what he did during the internship and uses it to present three business concepts: unit economics, break-even analysis and the financing of mission-driven organizations.

About the company

Tea Ideas Pte Ltd is a social enterprise based in Singapore and founded in 2012. It sells tea-based food and beverage products and creates jobs for people who face barriers to work, such as seniors, caregivers, people with disabilities (PWDs) and people living with debilitating health conditions. Its mission statement says that “for some, it’s a first job, for others, a step toward entrepreneurship”. The company has been a member of raiSE, the Singapore Centre for Social Enterprise, since 2017.

The product range includes teas, cookies, cold brew coffee and customized corporate gifting. Tea Ideas also operates the Sippy Mug cafés and presents its model as Singapore’s first food and beverage social franchising model, in which trainees receive hands-on training and a pathway towards co-ownership. raiSE classifies the company as an “Emerging Social Enterprise”, a category for businesses that have tracked at least three months of social impact and generated market revenue. It received the Brands of Good Award in 2019 and 2020 and was a Steward Leadership 25 Honouree in 2023. The supporters listed in its profile include the National Kidney Foundation, the Ministry of Home Affairs, Prudential Corporation Asia and the TungLok Group.

According to the impact summary published in its raiSE directory profile, seven beneficiaries are employed and 52% of the manpower is dedicated to social impact creation. These figures are self-disclosed by the company, so they should be read as its own report and not as audited data. Tea Ideas is a small private company: it has no market capitalization or stock chart.

The company operates in a dense ecosystem. raiSE alone supports more than 350 social enterprise members. In food and beverages, Tea Ideas shares the market with other inclusive businesses such as Dignity Kitchen and with social enterprise cafés listed in the raiSE directory, such as Foreword Coffee.

Logo of Tea Ideas.
Logo of Tea Ideas
Source: the company.

I worked at a Sippy Mug café located inside the Ministry of Home Affairs. The café is small, with one counter and a compact kitchen area. Its team combines colleagues on the autism spectrum, who take orders and prepare drinks, with older mentors who coach them, and the founders are closely involved in the daily running of the business. Our group of three interns joined this team for one month.

My professional experience

The internship lasted one month in 2026. Looking back, it had four phases: learning the system, fixing it, rethinking the business model and testing it in public.

My missions

Learning the system. During the first week we served customers and prepared drinks while documenting how everything was done. We created visual guides for every item on the menu, to be displayed at each workstation. Each guide gives the sequence of steps, the quantities, the timings and a photo of each step, so that a team member can follow a recipe without guessing. We then expanded this work into a guidebook covering the opening routine, mise en place, taking orders on the point-of-sale system, and the closing and cleaning procedure.

Fixing the system. After the first week, simultaneous orders made the small work area chaotic. I proposed a station-based workflow: every person owns a station, every order is written on a ticket placed on a slider, the person taking the order reads it aloud, and the kitchen starts with the items that take the longest so that everything reaches the plate warm at the same time. By the end of the second week, I was coordinating the kitchen. In parallel, a guest mixologist ran a session with the team, and we added new drinks to the menu, such as an Oreo frappe, a Biscoff frappe and a cold brew tea.

Rethinking the model. In the second half of the internship we helped prepare the application for a S$50,000 social enterprise grant offered through raiSE. This meant presenting the business model, building financial projections and explaining how the money would be used. We spent several days on it, including a full day of strategy discussions with the founders in Johor Bahru, Malaysia. The central idea was to use the café as a training ground for a workplace integration model: older mentors train PWDs in the café, and the trainees are then placed in regular corporate workplaces where they can earn a living.

Testing in public. At the end of the internship we ran a roadshow in a corporate office, with a stall to sell Tea Ideas tea products, hand out samples and talk to prospective customers.

Required skills and knowledge

The hard skills were process mapping and the writing of operating procedures, building a simple financial model in a spreadsheet with revenue lines, cost lines and scenarios, using a point-of-sale system and applying food hygiene standards. The soft skills mattered at least as much: patience and clear communication with colleagues who need precise and unambiguous instructions, leading without formal authority, adapting quickly when a plan fails in the middle of service, and presenting a business case to the founders and, indirectly, to a grant reviewer.

What I learned

The most important lesson came from a colleague on the autism spectrum. He followed every instruction with more precision than most people would, but when something went wrong, for example when too much salt went into a dish, the only recovery he knew was to start again. I would simply add water. It showed me that the limit was in the design of the instructions and not in the person. A good operating procedure needs recovery steps, not only the normal path. This is also the logic of the workplace integration model: train people not only to execute but to adapt.

On the business side, I learned how a funding proposal is read. A reviewer wants to see a story of pilot, validation, scale and sustainability, supported by explicit assumptions. I also learned how much operations drive financial results: a ticket system or a clearer recipe card looks like a small change, but it changes how many orders a small team can serve in an hour.

Economic, financial and business concepts related to my professional experience

I present below three concepts related to my professional experience: unit economics, break-even analysis and blended financing. The numbers in the first two sections are stylized illustrations that I built for this article. They are not Tea Ideas’ figures.

Unit economics and contribution margin

Unit economics measures what one unit of a business earns after the costs that vary with that unit. In this example, the unit of analysis is a billable session. The contribution margin (CM) is the price (P) minus the variable cost per unit (VC), and the contribution margin ratio is this amount divided by the price. The contribution margin measures the amount available to cover fixed costs and, once these costs are covered, to generate operating profit.

CM = P − VC     and     CM ratio = (P − VC) / P

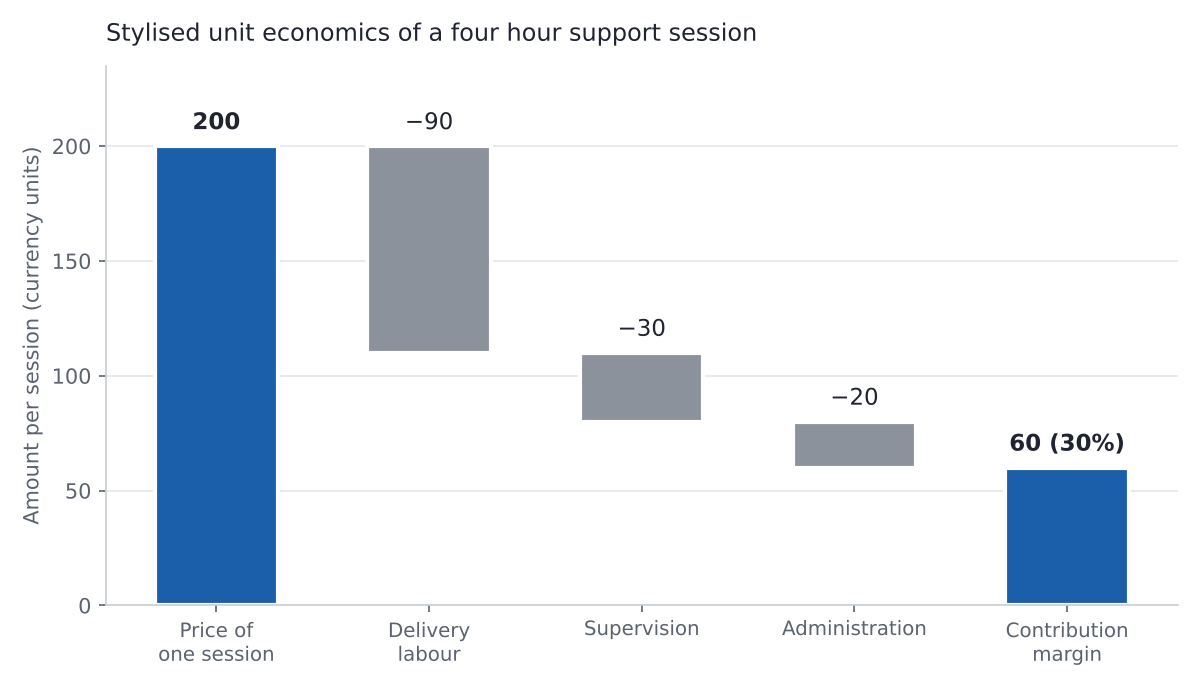
Suppose a four-hour support session is billed S$200. Delivering it costs S$90 for the person who delivers it, S$30 for supervision and S$20 for administration. All costs in this example are assumed to vary with the number of sessions delivered. The contribution is S$60, or 30% of the price (Figure 1).

Figure 1: Stylized unit economics of a four-hour support session.
Stylized unit economics of a support session
Source: author’s own illustration, stylized numbers.

This was the starting point of the financial projections we prepared. Before forecasting a single year, we had to ask what one unit of service earns after the people who deliver it are paid. The framework also shows where management attention matters most. With these numbers, a 10% price increase (from S$200 to S$220) lifts the contribution from S$60 to S$80, an increase of 33.33%, while a 10% reduction in all variable costs (S$14 out of S$140) increases the contribution margin by 23.33%. In this example, increasing the price has a greater impact on the contribution margin than reducing variable costs by the same percentage. However, the effectiveness of a pricing strategy also depends on how customers respond to price changes.

Break-even analysis and operating leverage

Fixed costs, such as rent, core salaries, and insurance, remain constant within a relevant range of activity and over a given time horizon. The break-even volume is the number of units at which total contribution equals fixed costs. The operating profit (EBIT) is equal to the total contribution margin minus fixed costs (FC). The break-even volume is reached when EBIT equals zero.

EBIT = Q × CM – FC

Q* = FC / CM

where Q is the number of sessions sold, CM is the contribution margin per session, and FC represents fixed costs.

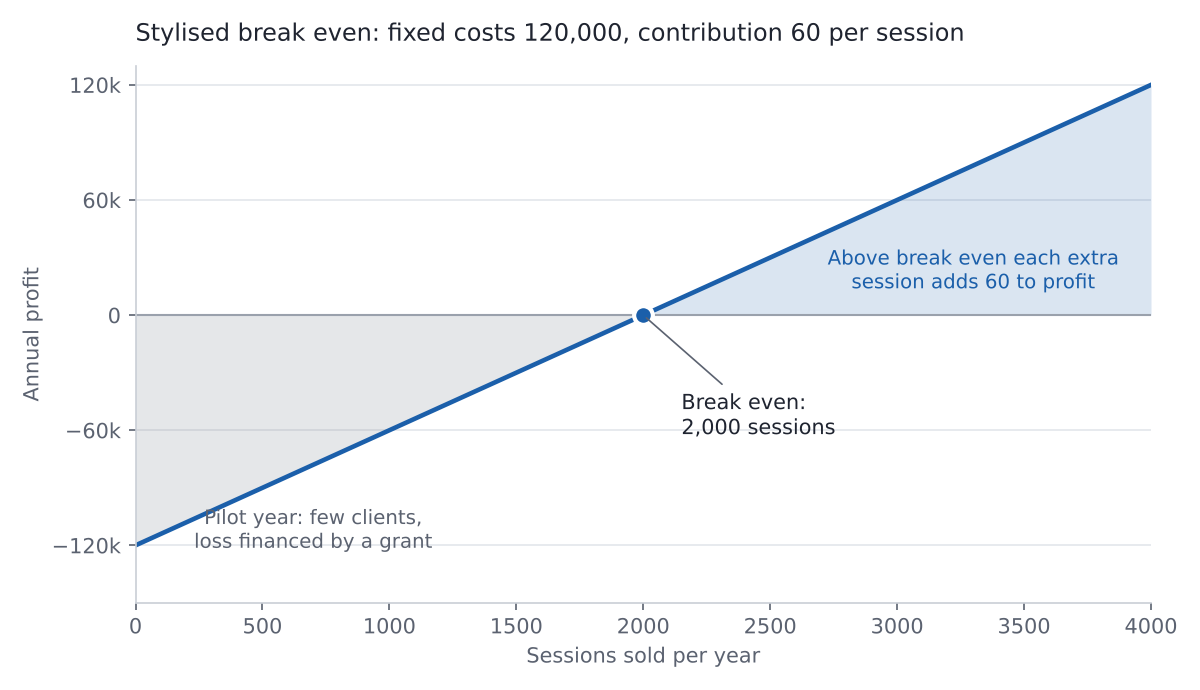
With stylized fixed costs (FC) of S$120,000 per year and a contribution of S$60 per session, break even is reached at 2,000 sessions (Figure 2). A pilot year has few clients and sits to the left of this point, so it makes a loss. A grant can help finance the operating costs of the pilot phase, provided these expenditures are eligible under the grant conditions. Initial losses may be economically justified if the business plan demonstrates a credible path toward financial sustainability.

Figure 2: Stylized break-even analysis.
Stylized break-even analysis
Source: author’s own illustration, stylized numbers.

Beyond the break-even point, each additional session adds its full contribution of S$60 to operating profit. Operating leverage measures the sensitivity of operating profit to changes in sales volume. For a given contribution margin per unit and sales volume, higher fixed costs increase the relative sensitivity of operating profit to changes in sales volume, provided operating profit remains positive. It explains why scaling a service business is attractive, but also why a pilot must prove demand before fixed costs are committed.

Blended financing and mission drift

A social enterprise sells products or services like a business, but its goal is a social outcome. It therefore often combines earned revenue with grants and donations. A grant does not dilute ownership and is usually tied to a purpose, but it is temporary. Earned revenue is renewable, but it creates a risk that researchers call mission drift: the organization moves toward the customers who pay best and away from the people it wants to serve (Battilana and Lee, 2014). Yunus, Moingeon and Lehmann-Ortega (2010) argue that a social business must be designed so that its economic engine covers its costs while serving the social objective.

In our case, the objective was to use the grant to finance the pilot phase while developing a sustainable revenue stream from companies paying for workplace integration programs. These revenues could eventually cover the program’s operating costs. Funders also look at what is measured. Ebrahim and Rangan (2014) distinguish outputs (for example, the number of people trained), outcomes (for example, the number who keep a job) and impact, defined as lasting change in the lives of people. A proposal that is explicit about this ladder is easier to evaluate and harder to criticize.

Why should I be interested in this post?

If you are a business or finance student, this post shows how finance tools apply outside a bank. Unit economics, break-even analysis, and financing decisions are also central to the financial analysis of startups and investment projects. A grant application is also close to an investment memo: it requires assumptions, scenarios and a clear use of proceeds. Impact investing and sustainability reporting are areas where understanding how a mission-driven organization balances revenue and impact is directly useful. Finally, an operations role in a very small organization gives responsibility early, and it teaches you what drives margins in a way that a valuation model captures only indirectly.

Related posts on the SimTrade blog

   ▶ All posts about Professional experiences

   ▶ Anant JAIN My internship experience at Deloitte

   ▶ Bochen LIU My Internship Experience as a Marketing Intern at XING QI Educational Institution

Useful resources

Academic research

Battilana, J., Lee, M., (2014) Advancing Research on Hybrid Organizing: Insights from the Study of Social Enterprises, Academy of Management Annals, 8(1), 397–441.

Ebrahim, A., Rangan, V. K., (2014) What Impact? A Framework for Measuring the Scale and Scope of Social Performance, California Management Review, 56(3), 118–141.

Yunus, M., Moingeon, B., Lehmann-Ortega, L., (2010) Building Social Business Models: Lessons from the Grameen Experience, Long Range Planning, 43(2–3), 308–325.

Business resources

Tea Ideas profile in the raiSE member directory

raiSE, Singapore Centre for Social Enterprise

Tea Ideas

About the author

The article was written in November 2026 by Arjun KODAPPULLY (ESSEC Business School, Global Bachelor in Business Administration (GBBA), 2024-2028).

   ▶ Discover all posts by Arjun KODAPPULLY.

My experience as a Cross-Asset Structurer in a Structured Products Broker

Jules HERNANDEZ

In this article, Jules HERNANDEZ (ESSEC Business School, Global Bachelor in Business Administration (GBBA), 2021-2025) shares his professional experience as Cross-Asset Structurer in a structured products brokerage firm.

What is this article about?

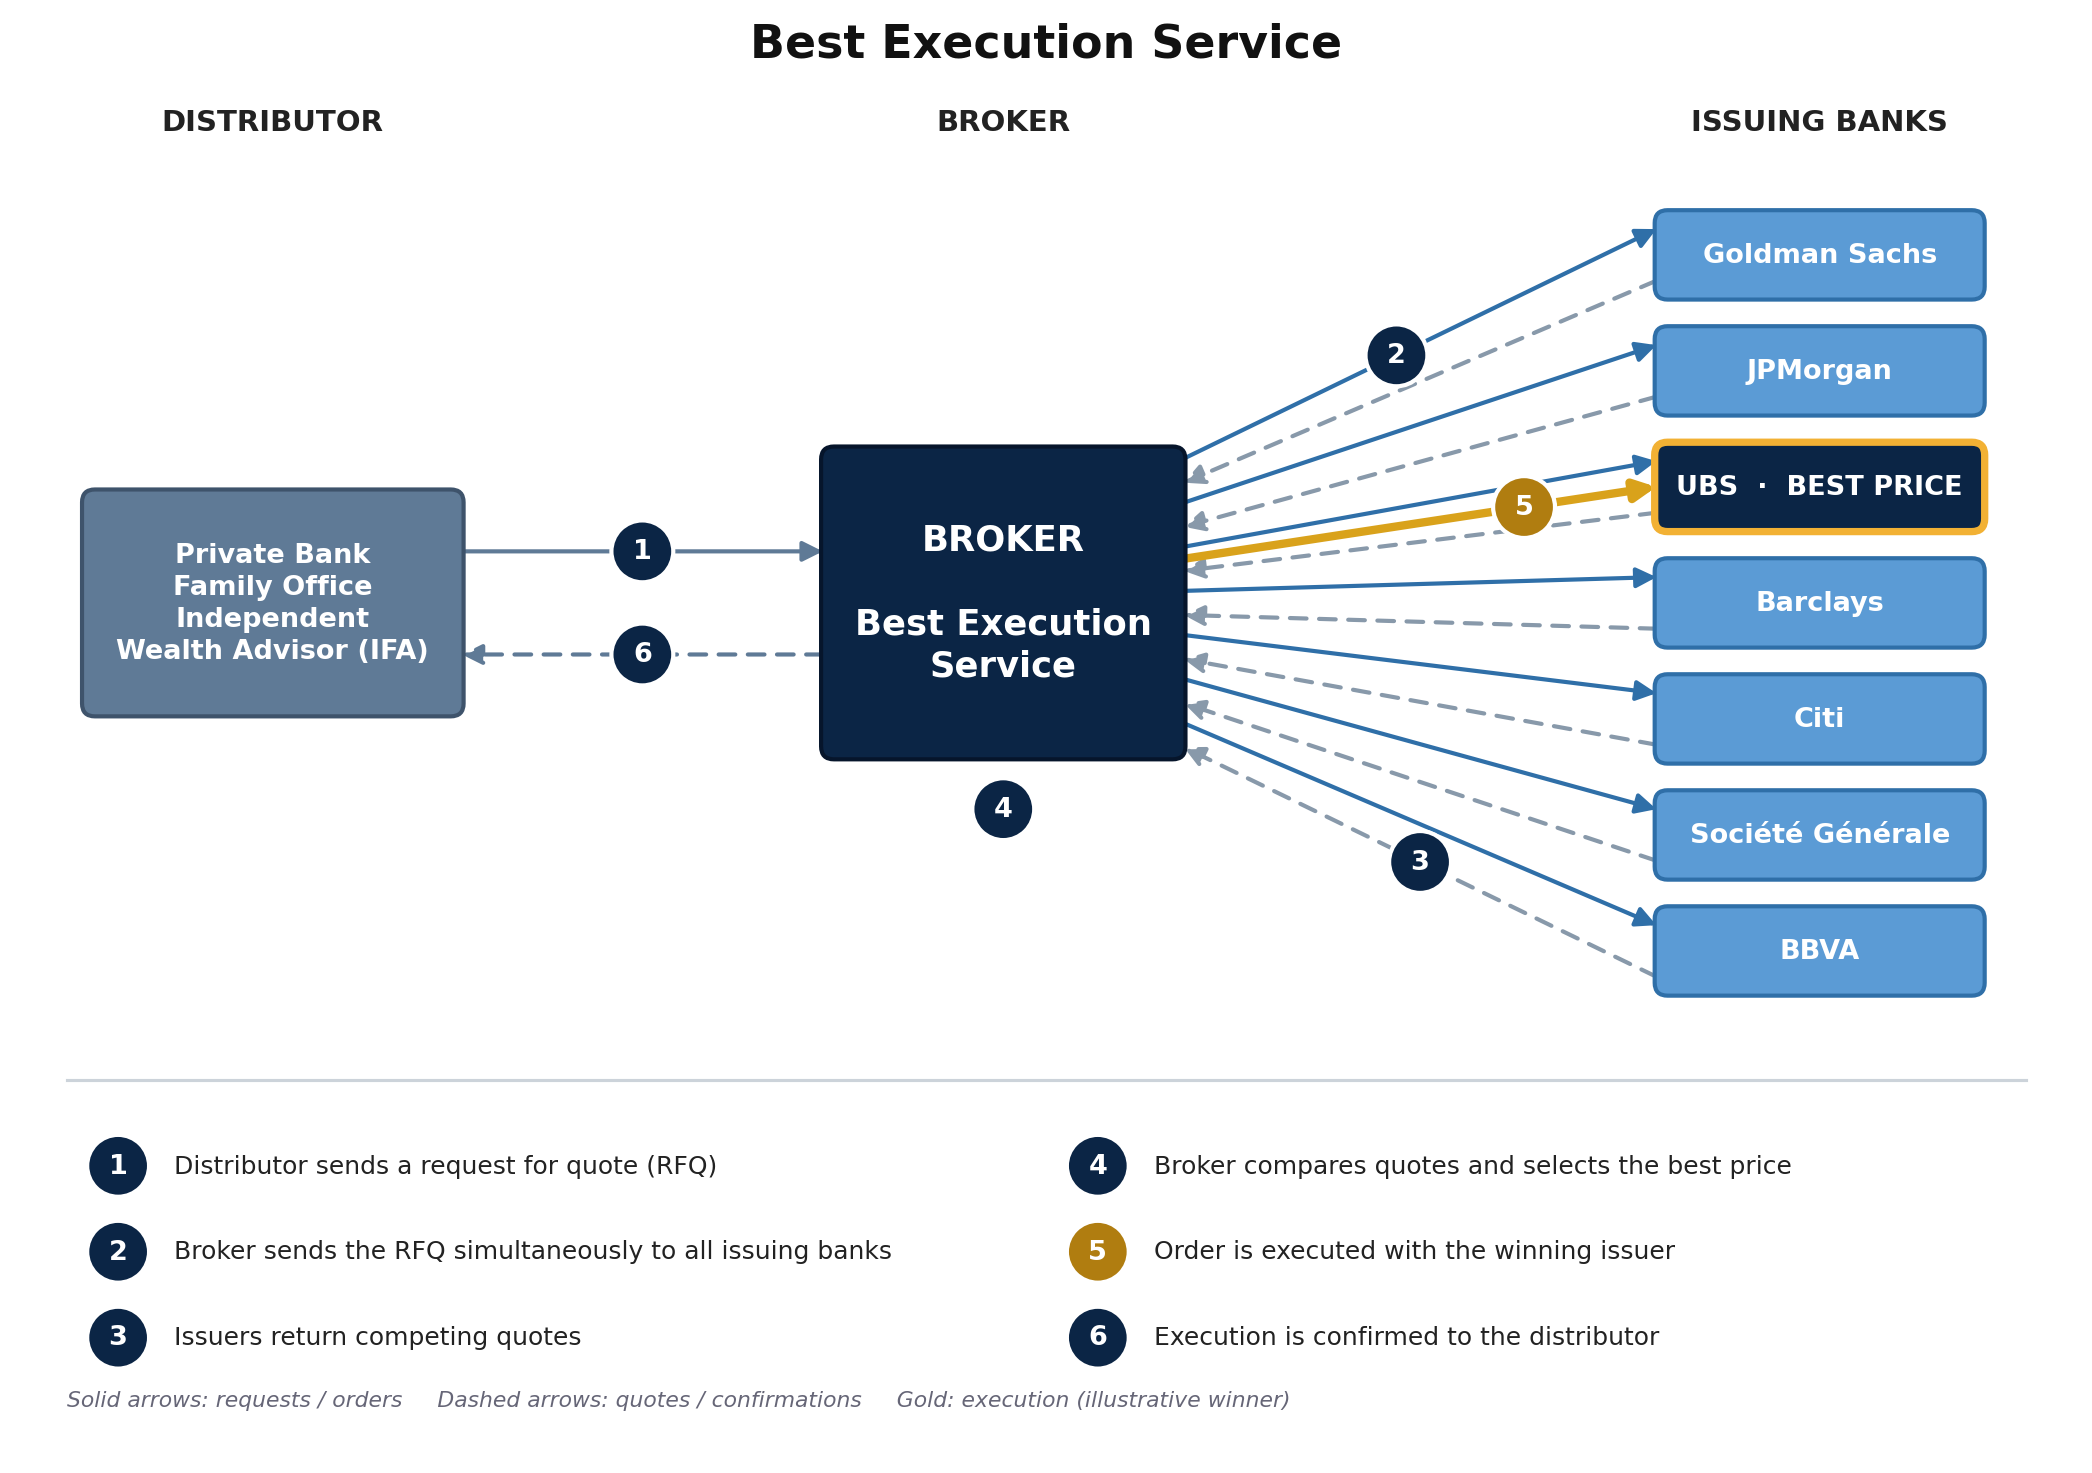
In this article, I will explore the role of a structured products brokerage firm and the four key services it provides: structuring, best execution, financial analysis and investment ideas, and product monitoring and lifecycle management. I will then share my experience as an intern, describe my main responsibilities, from product pricing and marketing presentations to client and issuer relationships, and explain the knowledge and skills required to succeed in this field, including how to prepare for an interview.

However, having knowledge about these investment solutions will help you to fully understand this article and the description of an internship in a structured product broker. Therefore, if you have limited knowledge about structured products, I highly recommend reading this article first where you’ll find an explanation of this financial instrument and many details related to it: Structured products: what’s behind them?

What is a structured product broker?

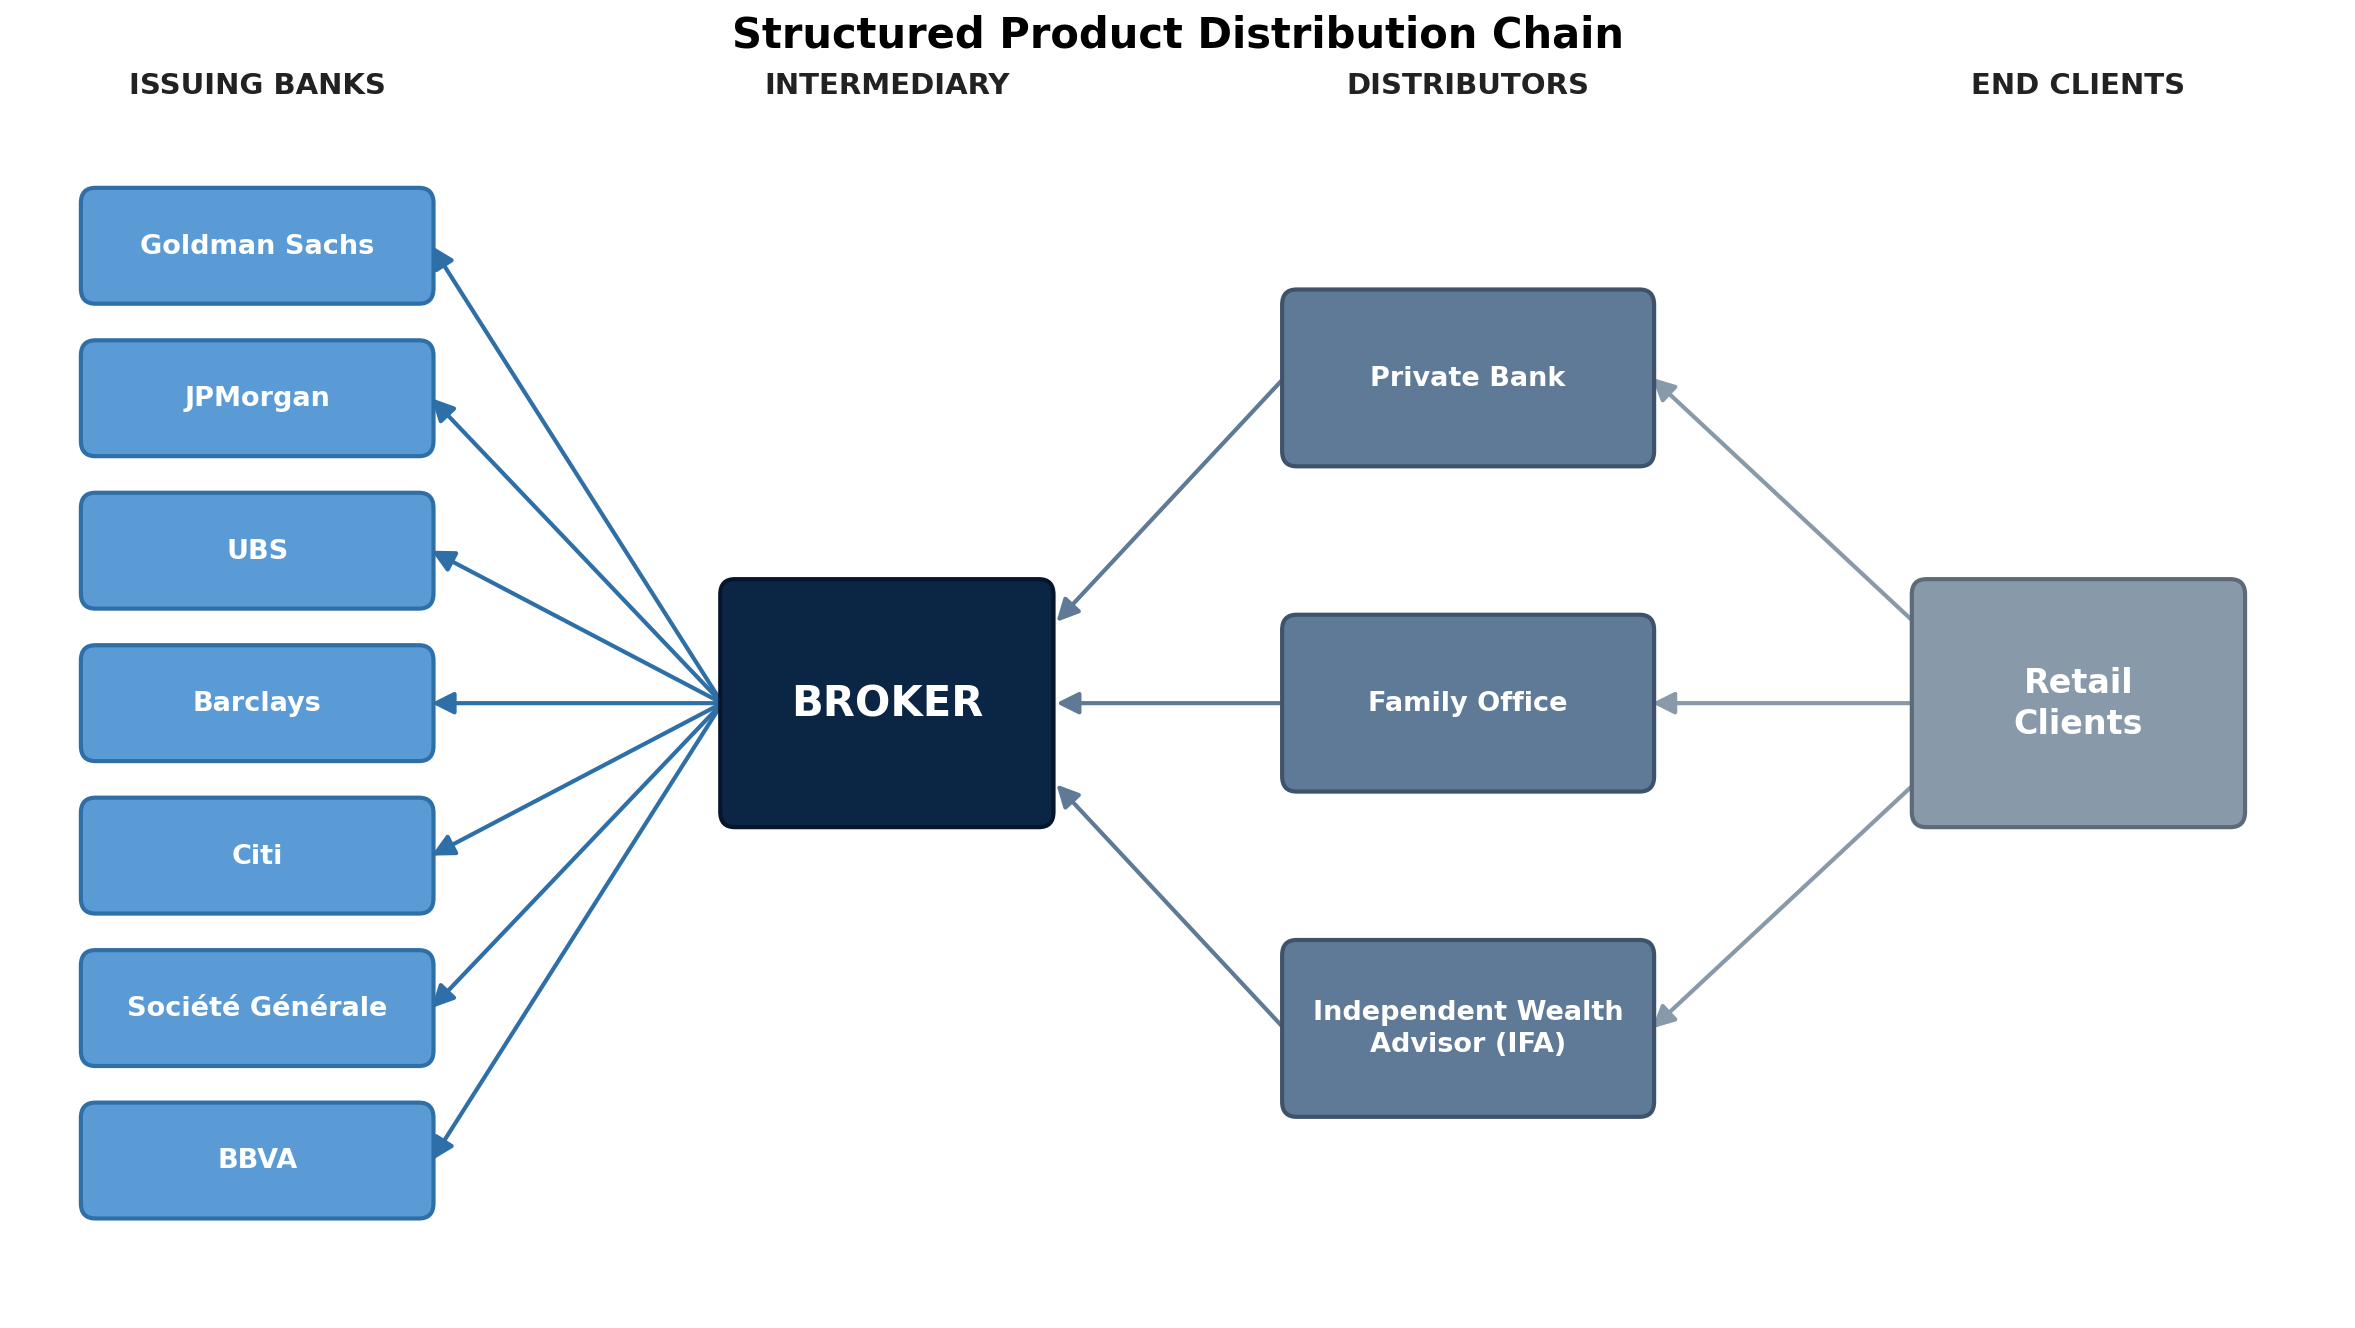
A structured product broker acts as an intermediary between professional investors and issuing banks such as JPMorgan, Goldman Sachs, UBS, BBVA, Citi, Barclays, and many others. Its clients include wealth management advisers, known in France as Conseillers en Gestion de Patrimoine (CGPs), single-family offices and multi-family offices, as well as private banks. Although these clients may have different business models and customer bases, they share the same objective when approaching a broker: finding a structured product that reflects their market views and investment objectives, while obtaining the most competitive pricing possible. To achieve this, brokers leverage their network of banking partners to source and compare proposals, helping clients identify the most attractive investment opportunities available on the market.

You will find below a chart clarifying the structured products actor and the distribution chain :

Structured products actors and the distribution chain

How is a Structured Products Brokerage Firm Organized?

From my experience, a structured products brokerage firm can be divided into two main teams: Sales and Structuring. Both teams must work closely together to ensure that each transaction runs smoothly, from the initial client discussion to the final execution of the order.

The Sales Team

The Sales team is responsible for developing the firm’s client base and maintaining long-term relationships with existing clients. This involves prospecting new clients, contacting wealth management advisers, family offices and private banks, and demonstrating the value a broker can bring to their investment activities.

Beyond acquiring new clients, Sales professionals act as the main point of contact throughout the investment process. They identify clients’ needs, understand their market views, advise their clients about the market, present investment opportunities, and communicate proposals prepared with the Structuring team. For example, a client may have a positive outlook on equity markets but may not want broad exposure to the entire market or to every sector. In this case, the broker can help refine the client’s investment view by identifying sectors with strong growth potential, such as electrification, and highlighting companies that could benefit from this trend. Examples include Schneider Electric, Bloom Energy or Prysmian, which could be suitable underlyings for a structured product. The objective is to help clients translate their market views into more targeted investment opportunities.

They also explain product mechanics, discuss potential risks and returns, and can even teach client about structured products. Maintaining strong relationships is essential, as clients rely on their Sales contacts not only to access investment products but also to receive relevant market insights and timely investment ideas.

The Structuring Team

The Structuring team provides the technical and operational support required to turn client requests into executable investment solutions. Working closely with Sales, its responsibilities include designing and pricing structured products, obtaining quotes from issuing banks, comparing available structures, and preparing marketing presentations for clients. Its role also extends beyond the initial design and pricing stages. The team monitors product events, coordinates with issuers, and helps ensure that financial orders are processed correctly. Depending on the firm’s organization, these responsibilities can cover activities associated with both the front office, such as structuring and pricing, and the back office, such as transaction processing and operational follow-up.

The two teams are complementary: Sales’ objectives are to understand the client’s needs and communicate the investment opportunity, while the Structuring Team aims to provide the technical expertise and operational support needed to deliver it.

The Four Key Services of a Structured Products Broker

Structuring Services: Turning Market Views into Investment Solutions

One of the broker’s core responsibilities is to translate a client’s market expectations into a structured investment product. Clients may have a specific view on an underlying asset, an expectation about future market volatility, or a target return subject to defined risk constraints. The broker’s role is to convert these expectations into a product with clearly defined payoff conditions. For example, imagine a wealth manager who expects the Euro Stoxx 50 to remain relatively stable or rise moderately over the next three years. Rather than investing directly in the index, the wealth manager may want to offer clients a product that generates periodic coupons as long as the index remains above a predefined barrier, with the possibility of early redemption if certain conditions are met. The broker works with the Sales team to understand the client’s objectives, including the desired maturity, coupon level, capital protection conditions, and acceptable risk. The Structuring team then uses pricing tools provided by different issuing banks to model and compare possible structures. By adjusting parameters such as coupon barriers, capital barriers, observation dates, and maturity, it can assess different combinations and identify solutions that best match the client’s requirements.

This process requires a solid understanding of financial instruments, derivatives, market parameters, and the mechanics of structured products. It also involves balancing several constraints: a more attractive coupon may require the client to accept a higher level of risk, while stronger capital protection may reduce the potential return. The objective is not simply to design a product with an attractive headline yield, but to find a structure whose payoff, risk profile, and pricing are consistent with the client’s investment objectives.

Best Execution: Finding the Most Competitive Offer

Best execution is another fundamental service provided by structured products brokers. Because multiple banks can issue similar structured products, the broker can request competing proposals and compare the terms offered by different issuers. The comparison goes beyond the headline coupon. Depending on the product, relevant parameters may include the issue price, coupon, observation schedule, barriers, maturity, capital protection features, and the issuer’s credit quality. The broker also considers the consistency of each proposal with the client’s investment objectives and the practical conditions required to execute the transaction. For example, suppose a client wants to invest €1 million in a three-year autocallable product linked to a basket of European equities. The broker may approach several issuers with the same product specifications. One bank might offer a 7.5% annual coupon, another 7.8%, and a third 8.0%. The broker would then give the best price to its customer. The diagram below illustrates how our best execution service works.

Best Execution service

This ability to compare multiple issuers is a key source of value. An individual wealth manager may have access to only a limited number of banking partners, whereas a broker can leverage a broader network of issuers and centralise the comparison process. The objective is to obtain the best available terms for the client, while ensuring that the product remains appropriate for their needs. However, this should not be confused with simply choosing the highest coupon: the overall terms, risks, issuer quality, and execution conditions all matter.

Financial Analysis and Investment Ideas

A structured products broker also provides financial analysis to help clients and Sales teams identify investment opportunities. This research can cover macroeconomic developments, equity markets, interest rates, currencies, commodities, corporate fundamentals, volatility, and relative-value opportunities.

The purpose is to connect market developments with actionable investment ideas. For example, if a broker’s analysis suggests that a particular equity index offers an attractive risk-return profile, the team may investigate whether a structured product linked to that index could be relevant. Similarly, changes in implied volatility or interest-rate expectations may create opportunities to design products with different coupon levels or payoff profiles. Research therefore supports both the development of investment ideas and the structuring process. The analysis team helps identify potential underlying assets and market themes, while Sales professionals use these insights to discuss opportunities with clients and explain the rationale behind a proposed investment. This service is particularly valuable for wealth managers and private banks that may not have dedicated research teams covering every asset class. By providing accessible market commentary, investment scenarios, and product ideas, a broker helps clients make more informed decisions and gives Sales teams relevant material for their client discussions. Importantly, financial analysis should also consider the downside scenario. An investment idea must be assessed in terms of its potential return, the risks that could undermine the underlying market view, and the conditions under which the product could incur losses.

Product Monitoring and Lifecycle Management

A structured product is not static once it has been issued. Its market value fluctuates throughout its life in response to several factors, including the performance of its underlying assets, interest rates, dividends, volatility, and the issuer’s credit spread. Depending on its structure, changes in these parameters can materially affect the product’s valuation and potential redemption value.

A broker helps clients access this information easily by providing valuations and facilitating communication with issuers. This allows wealth managers and other professional investors to monitor their positions and better understand how market developments affect their investments. In addition to valuation, structured products can generate several contractual events during their lifetime. These may include coupon payments, the observation of coupon or capital barriers, early redemption through autocall features, and maturity. Monitoring these events is essential to ensure that clients understand what has happened to their investments and what may happen next.

Many brokers therefore use dedicated digital platforms that allow clients to view their portfolios, monitor product valuations, and track upcoming or completed events. Some platforms also include integrated pricing tools, enabling users to simulate different product structures, adjust parameters, and explore potential payoffs before submitting a request to the broker. These tools improve transparency and simplify portfolio monitoring. They also allow clients to become more autonomous when exploring investment opportunities, while retaining access to the broker’s expertise for product design, pricing comparisons, and execution. Overall, product monitoring extends the broker’s role beyond the initial transaction. It helps maintain the relationship with clients throughout the product’s lifecycle and provides them with the information needed to follow their investments over time.

My internship

I spent six months working alongside the Structuring team, informally referred to in French as “La Structu”. Interns are entrusted with real responsibilities and quickly exposed to both sides of the business: clients and banking partners (issuers). This level of exposure requires rigor, attention to detail, and a strong sense of responsibility, since the intern’s tasks can have a significant impact on transactions, client relationships, and ultimately, the firm’s business.

My missions

One of the most interesting aspects of my internship was the variety of responsibilities I had. Working within the Structuring team gave me exposure to almost every stage of a structured product transaction, from its initial pricing to its execution and monitoring. Pricing was one of my main responsibilities. Using the dedicated platforms provided by our banking partners like Goldman Sachs, BNP Paribas and Société Générale, I could simulate different structured products and obtain indicative pricing. For instance, I could enter the parameters of an autocallable product, such as its coupon barrier, capital protection barrier and maturity, to determine the coupon each bank was prepared to offer. I would then compare the quotes received from different issuers to identify the most competitive proposal and share the results with the Sales team. The aim was to provide clients with the best available terms for their desired structure. This task demanded precision and a good understanding of product mechanics, as even small differences in pricing could influence the final terms offered to a client.

Below, you’ll find an exemple of a pricing platform. The following pricer is provided by Bloomberg. On this pricer, we can find all the relevant paramters used to price a structured product :

Bloomberg structured product pricer

My responsibilities did not end once a client decided to invest. I also took part in the operational follow-up of transactions, helping ensure that orders were processed and settled correctly. This involved coordinating with issuing banks, their back-office teams and custodians, checking transaction details and following up whenever an issue arose. Although less visible than pricing, this work was essential to ensure that transactions were completed smoothly and that all parties had the correct information.

Another part of my role involved document verification and product monitoring. Before products could be properly recorded and monitored, I had to check the documentation supplied by issuers, including term sheets, Key Information Documents (KIDs), target market documents and brochures used for life insurance contracts. I also entered newly issued products into a dedicated monitoring platform, enabling the firm and its clients to follow their valuations and key lifecycle events. This required particular attention to detail, since the information recorded needed to remain consistent with the product’s official documentation.

Finally, I contributed to the preparation of marketing materials used by the Sales team. These included presentations for client seminars and webinars, as well as product-specific presentations and one-pagers outlining a structure’s main features, payoff mechanics and investment rationale. The challenge was to turn technical financial information into clear, accessible material that Sales professionals could use when presenting investment opportunities to clients.

Alongside these core responsibilities, I also worked on various projects, particularly the automation of operational tasks using Excel and Bloomberg. The aim was to reduce manual work and improve efficiency in the team’s day-to-day activities. I also carried out regular market monitoring. Every week, I prepared and presented a short market update covering the macroeconomic environment and the main developments in economic news. This required keeping track of key indicators, central bank decisions, major market events and companies’ financial announcements that could boost implied volatility and offer investment opportunities to our clients.

Required skills and knowledge

Working in a structured products brokerage firm requires a combination of personal qualities and technical knowledge. While financial expertise can be developed over time, certain qualities are essential to work effectively in such a fast-paced environment.

First of all, teamwork and collaboration are arguably the most important qualities. As explained earlier, the business relies on close cooperation between the Sales and Structuring teams, as well as regular communication with issuing banks and clients. Information must flow smoothly between everyone involved, and the success of a transaction often depends on how well these different parties work together. Being approachable, responsive and willing to help colleagues is therefore just as important as individual performance. No matter how strong your technical skills are, you cannot succeed in this environment by working in isolation.

From my experience, I would then say that curiosity and a genuine interest in financial markets are equally important. Markets evolve constantly, driven by economic data, central bank decisions, geopolitical developments and corporate news. Understanding these movements helps identify investment opportunities, anticipate clients’ needs and assess how changing market conditions affect structured products. Reading financial news regularly, following market trends and developing your own investment views are all good ways to build this curiosity. You do not need to know everything from day one, but you must be willing to learn every day.

Rigour and attention to detail are also essential qualities. Structured products involve complex payoff mechanisms, precise contractual terms and multiple operational steps. An incorrect pricing parameter, an error in a term sheet or a mistake in an order can have financial consequences for both the client and the firm. Being organized, checking your work carefully and remaining focused under pressure are therefore fundamental to the job.

Beyond these personal qualities, working in this field requires a solid technical understanding of financial markets and financial engineering. You need to understand how different asset classes behave, including equities, interest rates, foreign exchange and commodities, as well as the main factors influencing their prices. Knowledge of derivatives, particularly options, is also valuable, since their pricing and risk characteristics underpin many structured products. It is equally important to understand the mechanics of structured products themselves: how coupons are generated, how barriers work, what triggers an early redemption, and under which conditions an investor may incur losses. A basic understanding of volatility, dividends, interest rates and correlation can also help explain why a product’s pricing changes depending on market conditions and its underlying assets.

And finally, it goes without saying, proficiency in Excel is particularly useful. It is used every day for analysing data and automating recurring tasks. Familiarity with Bloomberg can also be an advantage, as it allows you to access market data, monitor financial news and analyse market movements more efficiently.

What I learned during this internship

Of course, this internship allowed me to develop my technical knowledge, particularly in pricing structured products and understanding their mechanics. It also gave me a much clearer picture of how structured products are distributed, from the relationship between brokers and issuing banks to the role of wealth managers, Family Offices and private banks. I discovered an ecosystem involving a wide range of actors, each with their own objectives and constraints, and learned how they work together to bring investment solutions to clients.

But beyond the technical skills, the most important lesson I took away from this experience was the importance of curiosity. Financial markets are constantly evolving, and there is always something new to understand. An economic announcement, a central bank decision, a geopolitical event or a sudden change in volatility can create new opportunities or completely change the way an investment should be approached. Following the markets is therefore not simply about knowing what happened, but about understanding why it happened, how different asset classes interact and what the implications might be for investors. Why does a rise in interest rates affect equity valuations? How can a geopolitical event influence currency markets? Why does implied volatility change the pricing of an option? These are the kinds of questions that make financial markets so interesting to me. During my internship, I realised that curiosity also means going beyond the tasks you are assigned. Whenever I came across an underlying asset or an investment theme I did not know well, I wanted to understand it better, explore the factors that could influence its performance and consider whether it could offer an interesting investment opportunity. This approach helped me gradually move beyond the technical aspects of structuring and develop a broader understanding of the investment rationale behind each product. It also encouraged me to share my market views and ideas with the Sales team, sometimes on topics that were not initially part of my responsibilities.

I believe that curiosity is what allows you to keep learning, improve your judgement and become more relevant in this industry. Technical knowledge can be acquired, and tools can be mastered, but the willingness to ask questions, challenge your assumptions and continuously deepen your understanding is what drives long-term progress. This is what I enjoyed most during my internship, and it is the mindset I want to carry forward throughout my career in financial markets.

What to know for your interview?

The purpose of this section is not to provide an exhaustive explanation of every concept you may encounter during an interview. Instead, it is intended as a checklist of the main topics you should be familiar with before applying for an internship or a position in structured products. For more detailed explanations, I recommend consulting other articles on the SimTrade Blog, particularly Structured Products: What’s Behind Them?, which provides a deeper look at several of the concepts mentioned below.

First, you should have a solid understanding of how financial markets work and be familiar with the main asset classes. In structured products, four asset classes are particularly important: Equity, Rates, Credit and FX.

You should be able to explain the main characteristics of each asset class and understand how they react to main economic events such as central bank decisions and inflation announcements.

The Main Types of Structured Products

You should know the mechanics of the most common structured products, understand how they generate returns and identify the risks faced by investors. In particular, you should be familiar with:

  • Phoenix Products with Memory: structured products offering conditional coupons when the underlying asset meets a predefined coupon barrier condition on an observation date, with unpaid coupons potentially accumulated and paid later if the condition is subsequently satisfied.
  • Reverse Convertibles: structured products offering a fixed coupon, generally independent of the underlying asset’s performance, in exchange for exposure to its downside risk, subject to the issuer’s credit risk.
  • Capital-Protected Interest Rate Products: products designed to provide exposure to interest rate markets while protecting the invested capital at maturity, subject to the terms of the product and the issuer’s credit risk.
  • Credit-Linked Notes (CLNs): products whose returns and repayment depend on the credit performance of one or more reference entities or credit events.
  • Participation Products: products designed to provide exposure to the performance of an underlying asset, sometimes with a participation rate greater than or less than 100%.

Derivatives and Options

Options are at the heart of many structured products, so understanding them is essential. You should know the difference between calls and puts, European and American options, and vanilla and exotic options. You should also understand the main factors affecting option prices, including the underlying asset price, volatility, time to maturity, interest rates and dividends.

You should be particularly comfortable with the following option payoffs and strategies:

  • Upside participation mechanisms: call options, digital options and up-and-out calls.
  • Downside protection mechanisms: down-and-in puts, put spreads and leveraged puts.

You should be able to sketch their payoff profiles, explain how they behave under different market scenarios and understand how they can be combined to create a structured product.

Another useful concept to master is the replication of a digital option using a tight call spread. By combining a long call (lower strike) and a short call (higher strike) with nearby strike prices, it is possible to approximate the payoff of a digital option, with the accuracy of the approximation depending on the distance between the strikes. This question is almost always asked during an interview. The objective is to assess whether the candidate understands basic trading concepts and replication mechanics.

The Greeks and Risk Sensitivities

Finally, you should understand the main option Greeks, which measure how an option’s value responds to changes in different market parameters:

  • Delta: sensitivity to changes in the underlying asset price.
  • Gamma: sensitivity of delta to changes in the underlying asset price.
  • Vega: sensitivity to changes in implied volatility.
  • Theta: sensitivity to the passage of time.
  • Rho: sensitivity to changes in interest rates.

For structured products, it is particularly useful to understand how these sensitivities evolve over the product’s lifetime and how they are affected by barriers, early redemption features and market conditions. You do not necessarily need to derive every formula from memory, but you should be able to explain what each Greek measures and why it matters for pricing and risk management.

Why should you be interested in this post?

If you are interested in financial markets and considering a career in structured products, this article offers an overview of the role of a structured products broker, the main services provided and the responsibilities of a structuring intern. You will also find practical advice on the skills and knowledge required to prepare for an interview, based on my own six-month internship experience in a structured products brokerage firm.

Related posts on the SimTrade blog

Professional experiences

   ▶ All posts about Professional experiences

   ▶ Mathis HOUROU Client Segmentation and Private Banking: Marketing Strategy or Risk Shield?

   ▶ Wenxuan HU My experience as an intern of the Wealth Management Department in Hwabao Securities

   ▶ Lang Chin SHIU My internship experience at HSBC

   ▶ Louis DETALLE A quick review of Wealth Management’s job…

Financial techniques

   ▶ Jules HERNANDEZ Structured products: what’s behind them?

   ▶ Slah BOUGHATTAS Book by Slah Boughattas: State of the Art in Structured Products

   ▶ Mahé FERRET Selling Structured Products in France

   ▶ Akshit GUPTA Equity structured products

   ▶ Shengyu ZHENG Reverse Convertibles

   ▶ Nithisha CHALLA Index fund manager: Unveiling the Dynamics of Passive Investing

   ▶ Tianyi WANG Understanding Snowball Products: Payoff Structure, Risks, and Market Behavior

Useful resources

SRP Website – Industry insights This website is very useful to learn about the structured products industry. SRP conducts a lot of research on this matter

Yaël Eljarrat-Ouakni What is a Structured Product? Société Générale Private Banking France.

Pôle commun AMF-ACPR (06/2026) Distribution, frais et performance des produits structurés – Rapport final – Juin 2026

Autorité des Marchés Financiers (AMF) (24/05/2025) 2025 Markets and Risk Outlook

SRP (18/03/2025) Global Market review 2024, Europe Market review 2024

About the author

The article was written in November 2026 by Jules HERNANDEZ (ESSEC Business School, Global Bachelor in Business Administration (GBBA), 2021-2025).

   ▶ Discover all posts by Jules HERNANDEZ.