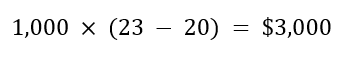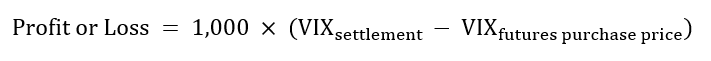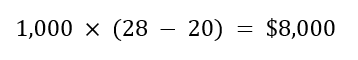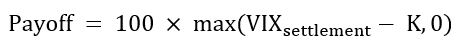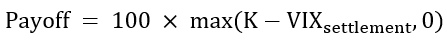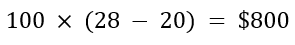
My experience as an independent portfolio manager of a family-funded equity and derivatives portfolio

Romil SOJITRA

In this article, Romil SOJITRA (Indian Institute of Technology Kanpur, BS in Economics, 2024-2028) shares his experience as an independent portfolio manager of a family-funded equity and derivatives portfolio in the Indian market, which he started with equities in May 2025 and extended to options in May 2026.

About the market: Indian equity derivatives

My portfolio was invested in Indian listed equities and in equity derivatives (futures and options) traded on the National Stock Exchange of India (NSE). NSE was founded in 1992 and introduced fully electronic, screen-based trading in India. It launched futures on the Nifty 50 index in 2000 and options in 2001. Since then, the Indian equity derivatives market has grown enormously. According to the Futures Industry Association (FIA), NSE was the largest derivatives exchange in the world by number of contracts traded for five consecutive years (2019 to 2023), mainly because of very high volumes in options on the Nifty 50 and Nifty Bank indexes with weekly expiries, that is, contracts that expire within seven days or less and that are heavily traded in the last days before expiry.

Logo of the National Stock Exchange of India (NSE).
Logo of NSE
Source: the company.

This growth came with risks for individual investors. In September 2024, the Securities and Exchange Board of India (SEBI), the market regulator, published a study showing that 93% of individual traders in equity futures and options made losses between FY22 and FY24 (in India, the fiscal year runs from April to March, so the study covers April 2021 to March 2024). Their aggregate net losses reached ₹1.81 lakh crore over the three years (1 lakh = 100,000 and 1 crore = 10 million, so 1 lakh crore = ₹1 trillion), that is about ₹1.8 trillion or roughly US$21 billion, and most of these losses came from options.

SEBI reacted to these losses. Because most losses were concentrated among small traders buying and selling short-dated index options, its circular of October 1, 2024 (applied from November 20, 2024) made this type of speculation harder: the minimum value of an index derivative contract was raised from ₹5-10 lakh to ₹15 lakh, so that each trade requires more capital, and each exchange may now offer weekly expiries on only one benchmark index (the Nifty 50 for NSE), which reduces the number of very short-dated contracts. These rules also mattered for my own sizing: one lot of a Nifty option now represents a notional amount of at least ₹15 lakh, so I could not size positions as finely as I wanted. I therefore started trading derivatives knowing that most individual participants lose money. My objective was not to “beat the market” quickly, but to build a process that controls risk first.

The portfolio was funded by my family. They gave me capital to manage after I had shown consistent results on a smaller amount. This made me accountable to real “clients”, even though they were family members: I reported my performance to them regularly and explained my decisions and my mistakes.

My experience

I started in May 2025 with Indian equities, investing in stocks and learning how markets work alongside my studies at IIT Kanpur. In May 2026, I moved to a more structured and quantitative approach: I added options trading and began applying the concepts presented in this article (the Black-Scholes-Merton model and the Greeks, the Kelly Criterion, Monte Carlo simulations) to a leveraged equity and derivatives portfolio. This post focuses mainly on this second phase, from May to August 2026 (44 trading sessions), and on the drawdown of March-April 2026 that came just before it. I am responsible for the full investment process: generating ideas, building positions, sizing them, hedging the portfolio, and measuring and reporting performance.

My missions

Since May 2026, when I added options to the portfolio, my work has covered the five areas below. The first one (relative-value equity positions) continued the equity book I had run since May 2025; the four others were new.

Building relative-value positions. I constructed long/short equity pairs: buying one stock and selling a related stock (for example, two companies in the same sector) to be exposed to their relative performance rather than to the direction of the overall market. When a pair is well built, a large part of the market risk cancels out, and the return depends on the spread between the two stocks.

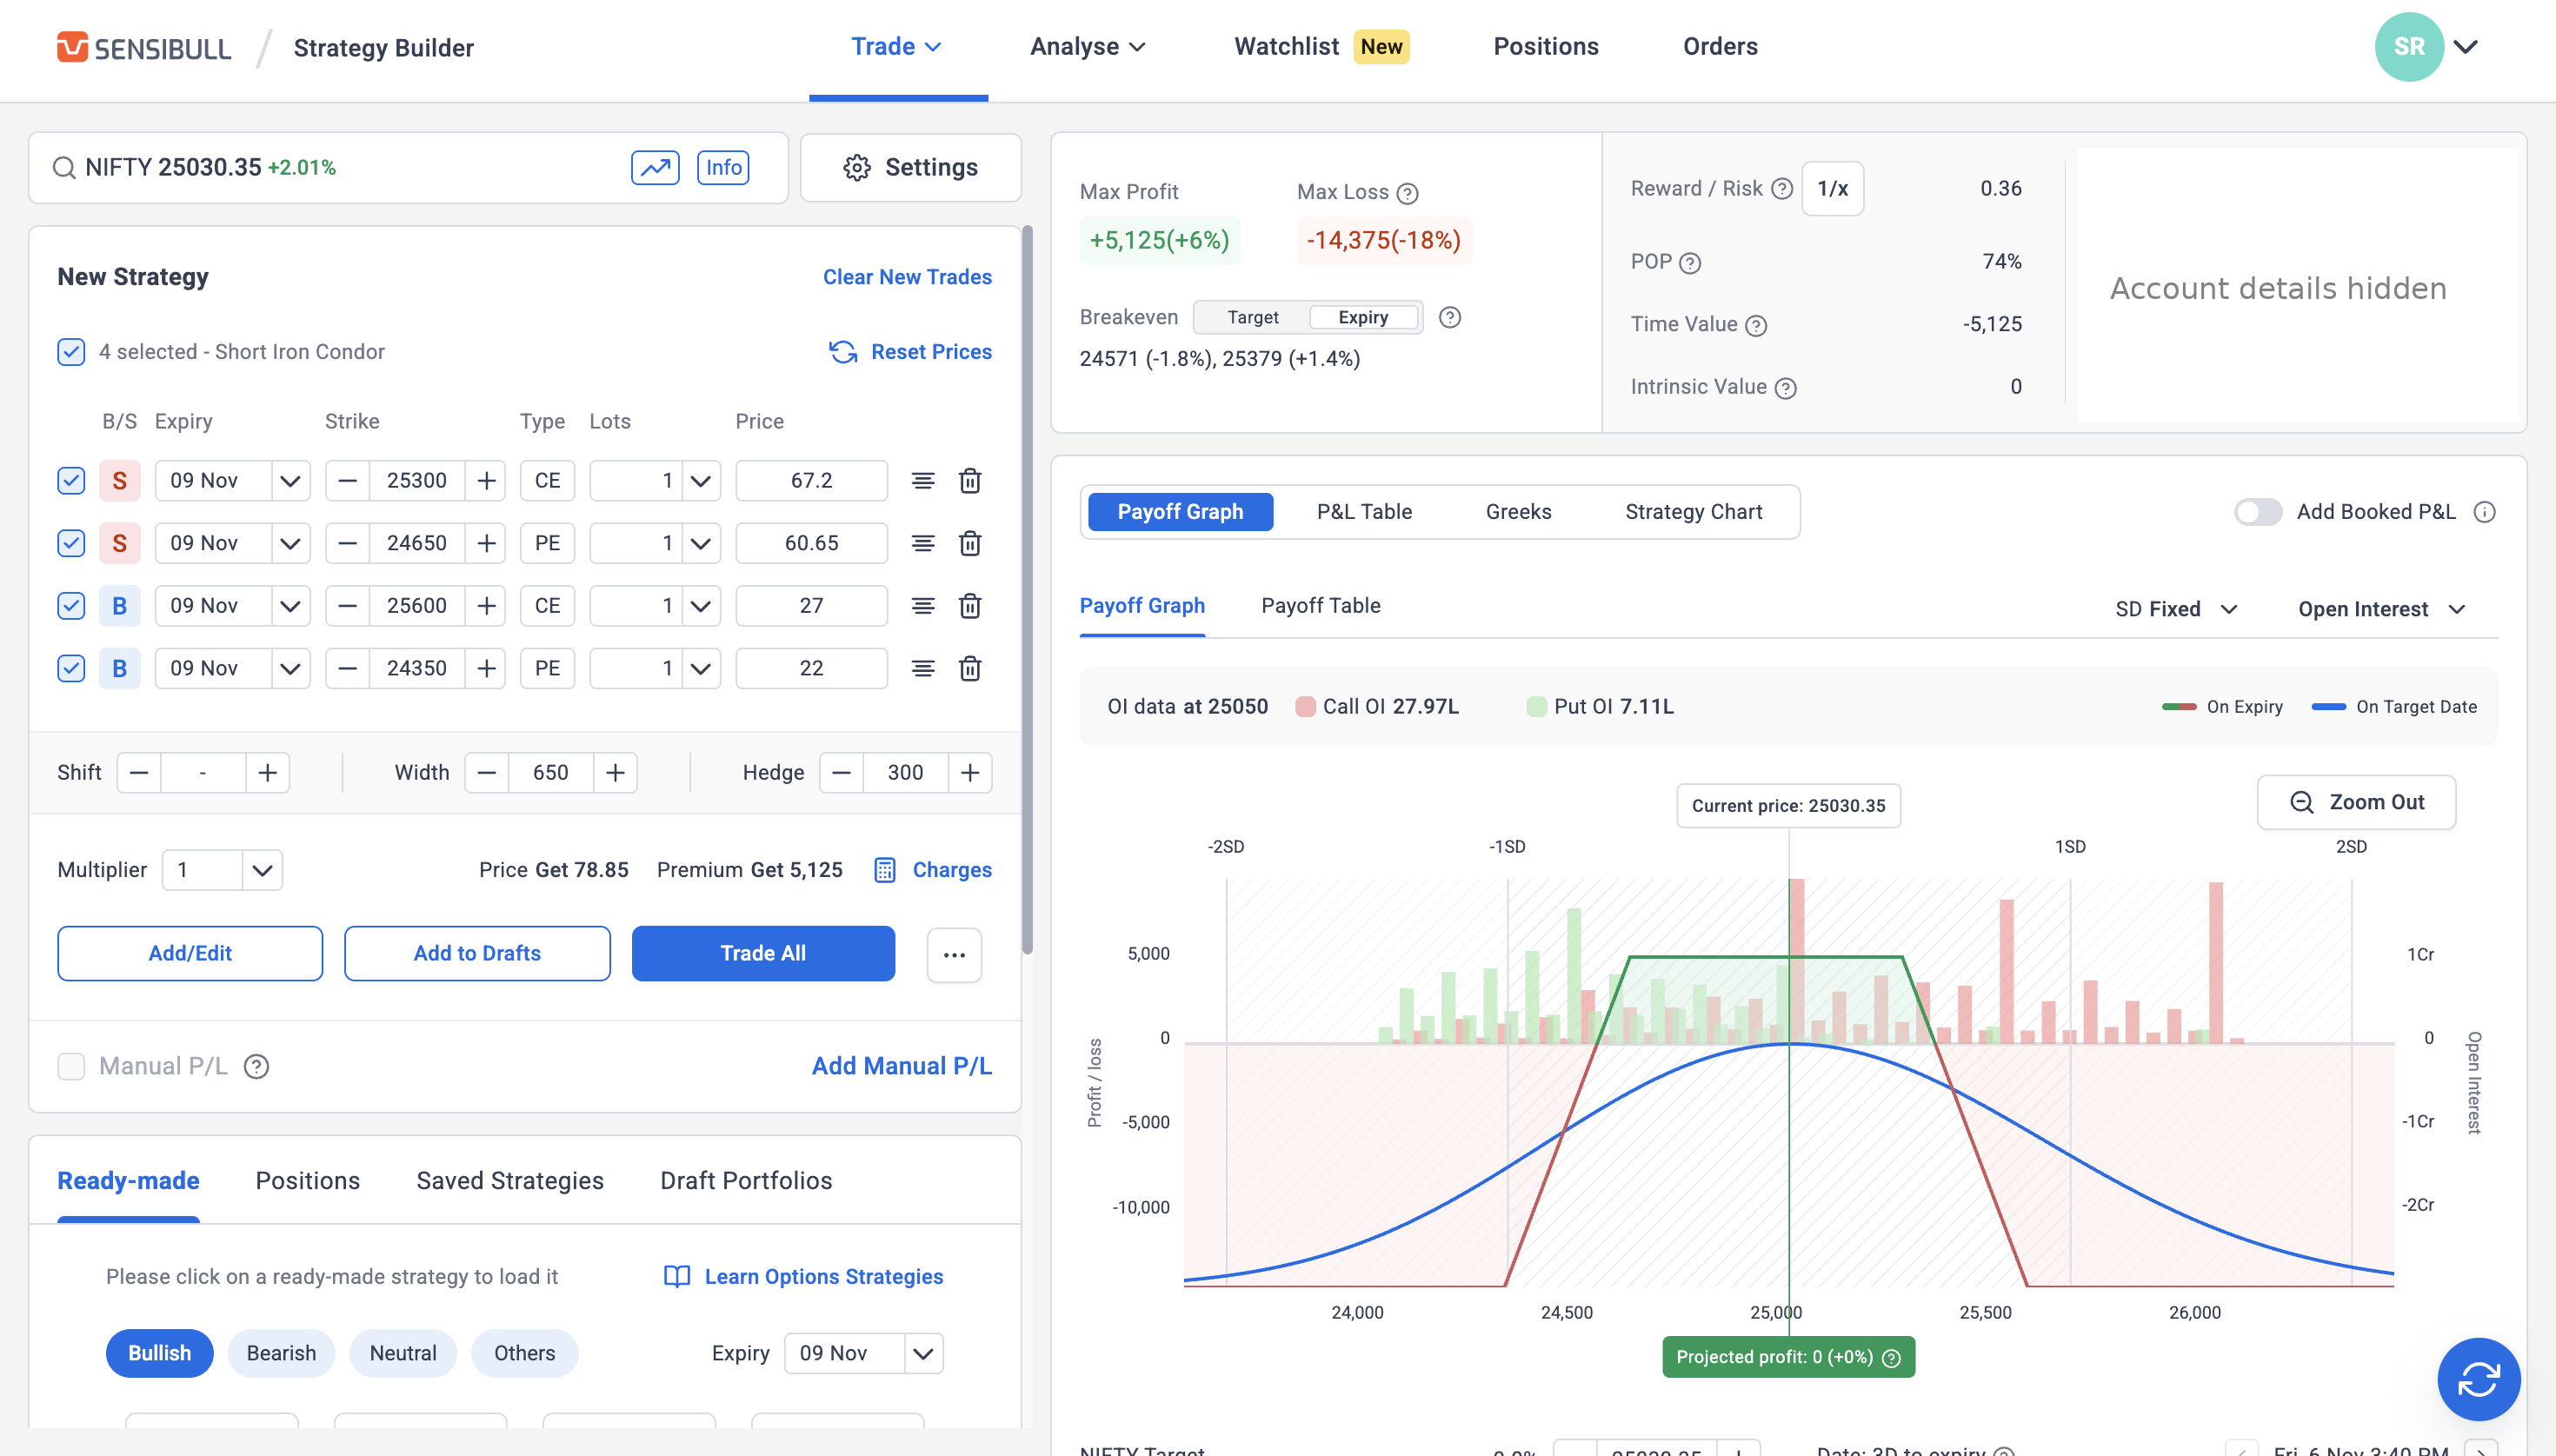
Running delta-neutral option positions. My option positions were mainly short volatility: I sold Nifty index options (for example a call and a put together, as in a short strangle) and kept the delta of the whole position close to zero by adjusting it with Nifty futures or by moving one of the option legs. Each position was therefore a combination of options and of the underlying (through futures), not options alone. Small moves of the index then had little impact, and the profit or loss came from two other sources. The first is time decay (theta): an option loses a little value every day as expiry approaches, and as a seller I earned this decay. The second is volatility. As a seller, I lost money when the volatility implied by option prices rose (negative vega), and above all I earned money when the index actually moved less than the volatility implied by the prices at which I sold the options, and lost money when it moved more (negative gamma). I explain this mechanism with an equation in the section on the Greeks below. I used Sensibull, an Indian options analytics platform, to analyze option chains, Greeks and the payoff of each strategy before entering a position. Figure 1 illustrates this analysis on an example: a short iron condor on the Nifty 50 (selling the 24,650 put and the 25,300 call, and buying the 24,350 put and the 25,600 call as protection), whose maximum loss is capped at the width of a wing (300 points) minus the net premium received (78.85 points).

Figure 1. Illustration: payoff of a short iron condor on the Nifty 50 in the Sensibull strategy builder (expiry of November 9, 2026).
Analysis of an option position on Sensibull
Source: Sensibull, screenshot by the author (illustration, November 6, 2026).

Hedging tail risk. Short-volatility and leveraged positions can lose a lot of money in a market crash. To protect the portfolio against extreme events, I held a long-dated index put option as a tail-risk hedge. This hedge costs a small premium in normal times but gains value when the market falls sharply. A bought put has positive gamma: its delta becomes more and more negative as the market falls, so its gains accelerate in a crash. It therefore offsets part of the negative gamma of the options I sold.

Sizing positions and modelling risk. I used the Kelly Criterion to decide how much capital to allocate to each trade, the Black-Scholes-Merton model to price options and compute their Greeks, and correlation and information-ratio analysis to build the portfolio. I also built Monte Carlo simulations. For position sizing, each session is a random draw: a win with probability p = 59.1% that pays b = 1.45 times the average loss, or a loss otherwise. I simulated 10,000 paths of 100 sessions for different bet sizes (this model is detailed in my article on the Kelly Criterion). For option positions, I simulated the Nifty 50 with a geometric Brownian motion, the model behind Black-Scholes-Merton, for several levels of annual volatility (for example 10%, 15% and 25%), and revalued the position on each simulated path.

Measuring and reporting performance. I kept a structured trading journal and a performance report. I tracked the win rate, the profit factor (gross profits divided by gross losses), the Sharpe, Sortino and Calmar ratios, and the drawdown, for each account and each strategy.

Required skills and knowledge

Hard skills. I needed a solid understanding of derivatives: how futures and options are priced (a futures price follows the cost-of-carry relation F = S × e(r − q)T, where S is the spot price, r the interest rate, q the dividend yield and T the maturity, while options are priced with the Black-Scholes-Merton model presented below), what the Greeks measure, and how a combination of options behaves when the price, volatility or time to maturity changes. I also needed statistics and econometrics to measure correlations and evaluate whether a strategy has a real edge or is just lucky. The courses I took at IIT Kanpur in econometrics, financial econometrics and optimization, and my preparation for the CFA Level I exam (which I passed in August 2026), were very useful here.

Soft skills. The most important skills were discipline and emotional control. It is easy to follow rules when trades are winning; it is much harder during a drawdown, when the temptation is to increase risk to recover losses quickly. Behavioral finance explains why. In prospect theory, Kahneman and Tversky (1979) show that people feel a loss more strongly than a gain of the same size (roughly twice as strongly) and become risk-seeking when they are below their reference point: after a loss, a trader is tempted to take more risk to get back to break-even. Kahneman (2011) adds that under stress, fast and intuitive thinking takes over from slow and deliberate thinking. This is why I relied on a written process and on my trading journal, not on my feelings, during the drawdown. I also needed honesty and communication skills to report bad periods to my family as clearly as good ones.

What I learned

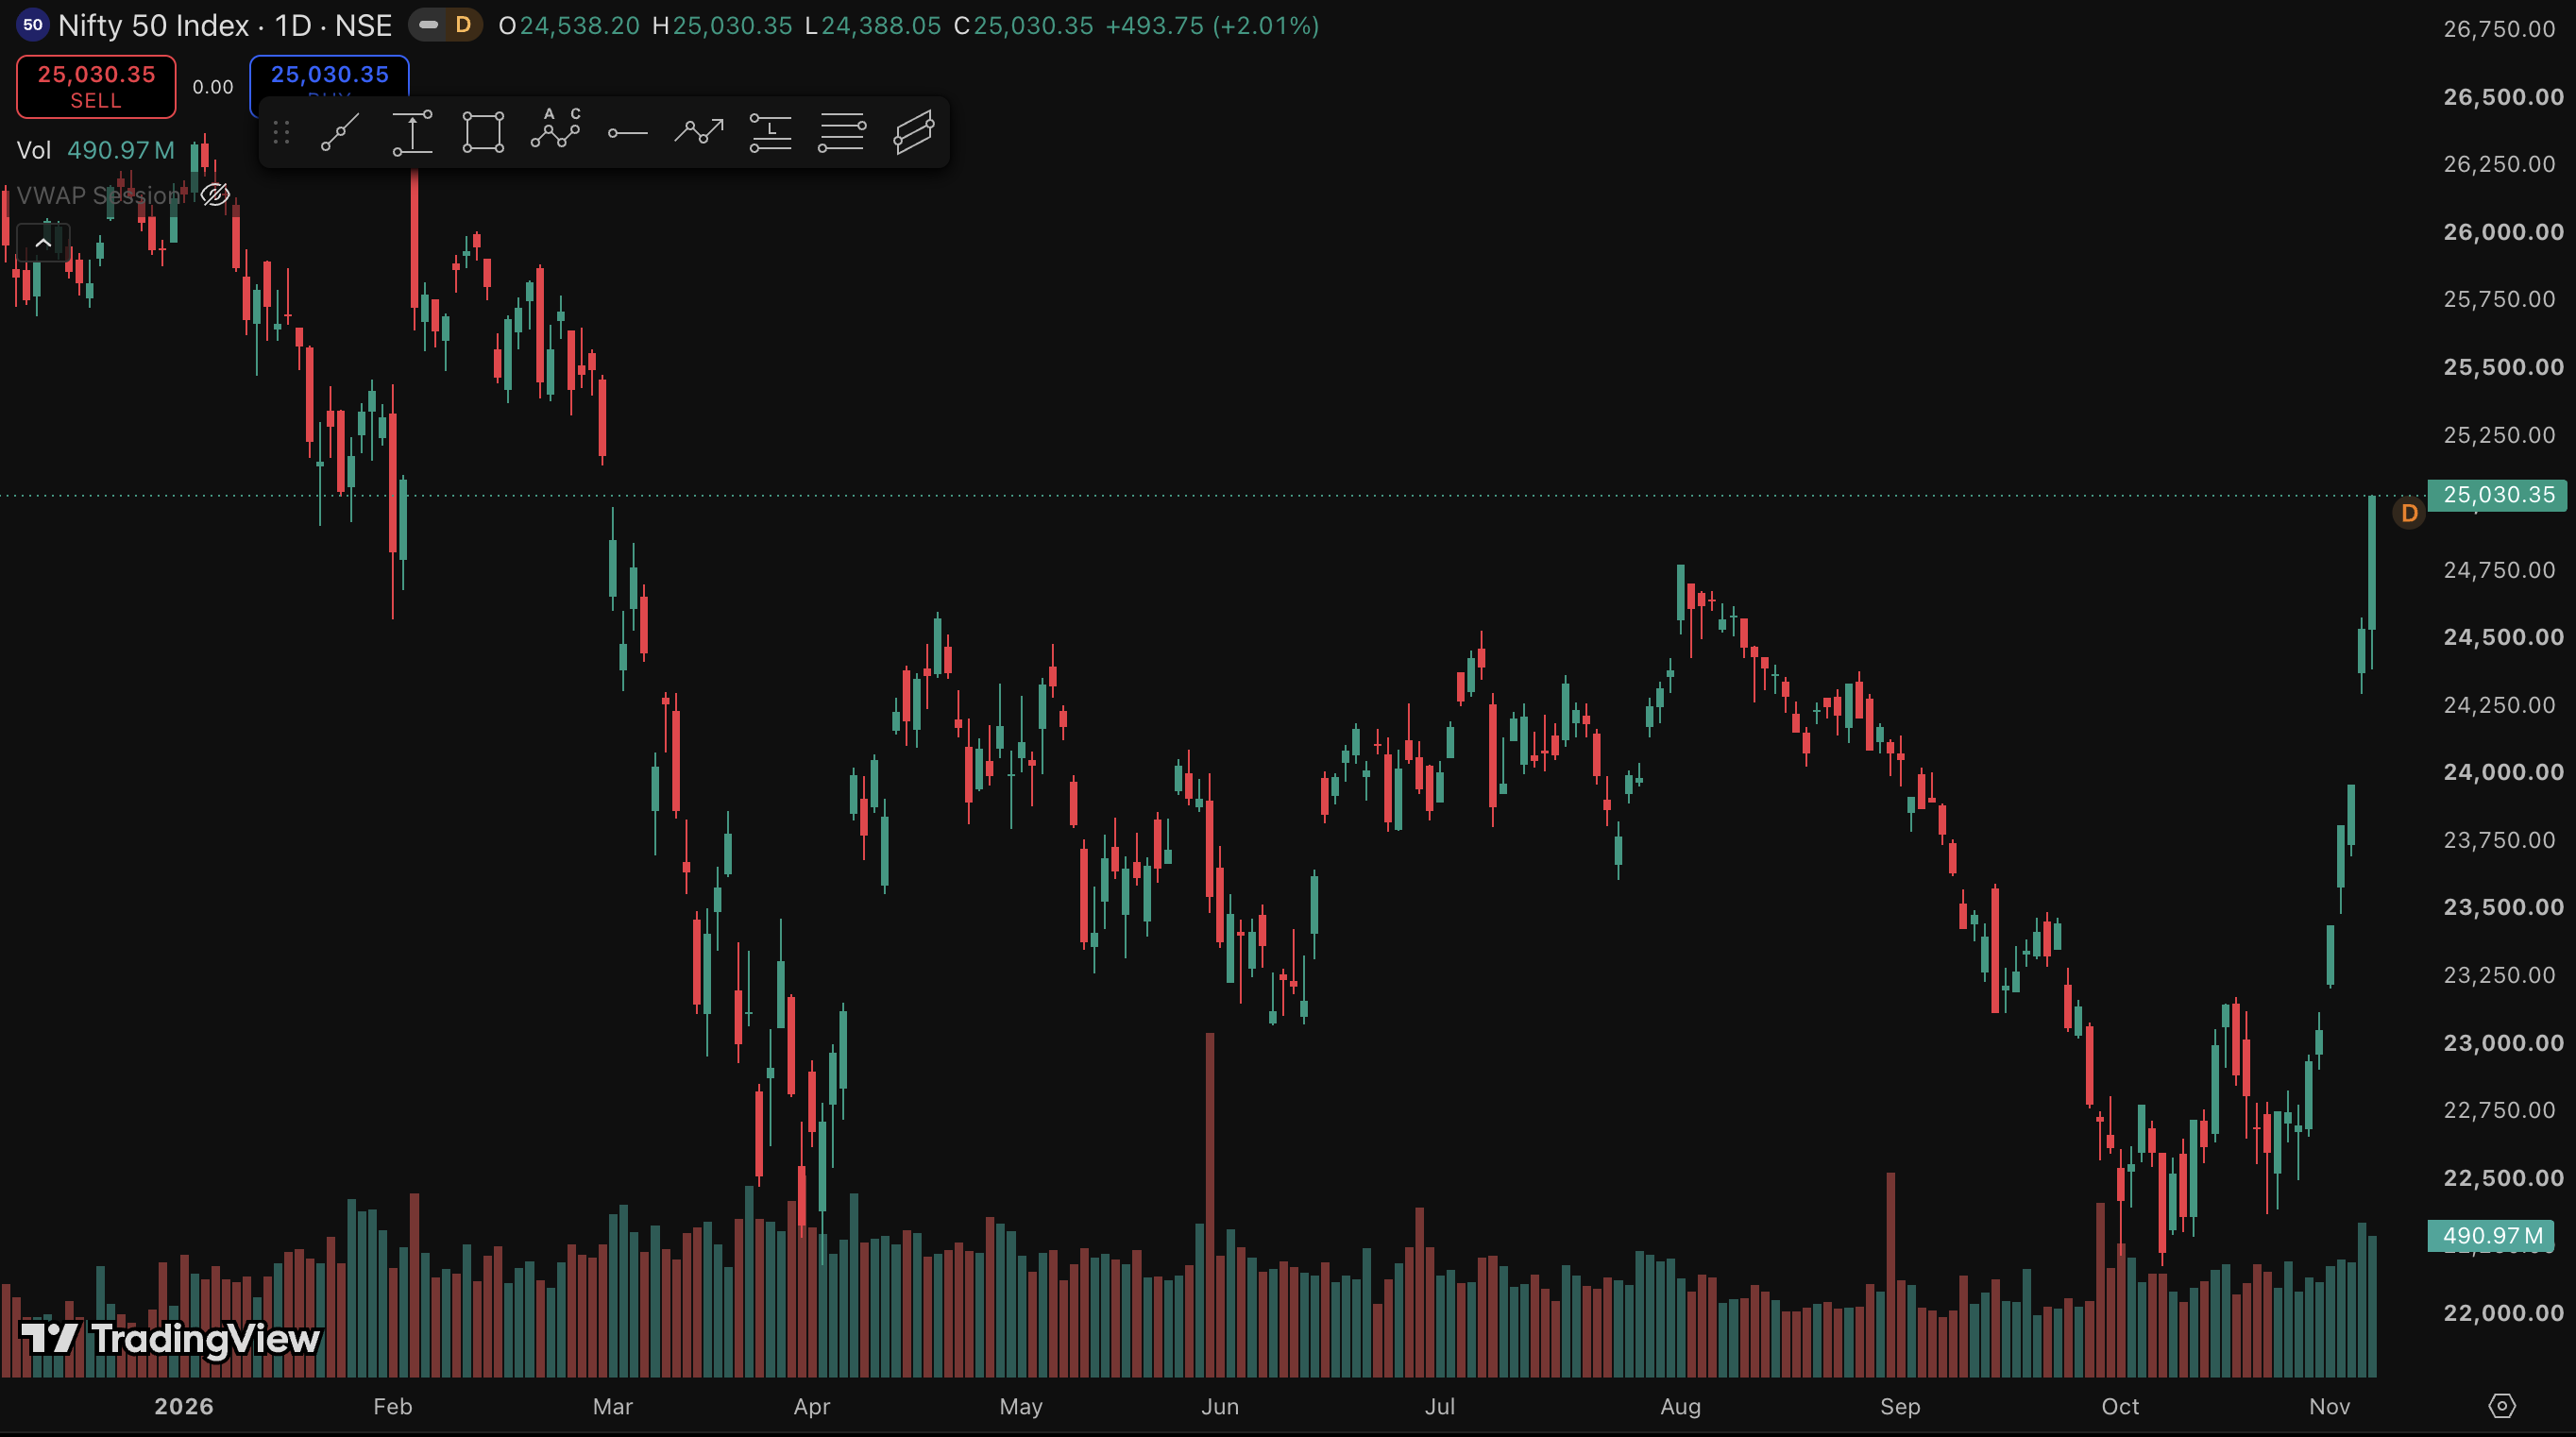
The most important lesson came from a difficult period. During the market sell-off of March-April 2026, linked to the US-Iran conflict, my portfolio suffered a heavy drawdown, mainly on high-beta stocks in my equity book (Figure 2). I had underestimated how much my positions were exposed to the same market factor, that is, the general movement of the Indian equity market measured by the Nifty 50. High-beta stocks amplify the moves of the index (a stock with a beta of 1.5 tends to fall by about 1.5% when the index falls by 1%), so in a sell-off they all fall together and their correlations rise: positions that looked different were in fact the same bet on the market. I did not try to win everything back at once. I reduced risk, kept following my process, and the portfolio recovered and became profitable over the following two months.

Figure 2. Evolution of the Nifty 50 index in 2026 (daily prices, January to early November).
Evolution of the Nifty 50 index in 2026
Source: TradingView (data: NSE).

Table 1 summarizes the performance of the portfolio over May-August 2026. A session is a trading day on which I had open positions and recorded a profit or a loss in my journal: there were 44 such sessions over the period. The portfolio delivered a return of 5.79% on deployed capital and 4.05% on total capital (part of the capital stayed in cash as a buffer). Of the 44 sessions, 26 were winners and 18 were losers, which gives a win rate of 59.1% (26/44). The profit factor (gross profits divided by gross losses) was 2.10, so the average winning session earned about 1.45 times what the average losing session lost (2.10 × 18/26). Figure 3 shows the evolution of the portfolio and its drawdown.

Table 1. Performance of the portfolio (May-August 2026).

MeasureValueHow it is computed
Trading sessions44Days with open positions
Winning / losing sessions26 / 18From the trading journal
Win rate (p)59.1%26 / 44
Profit factor2.10Gross profits / gross losses
Payoff ratio (b)1.45Average win / average loss = 2.10 × 18/26
Return on deployed capital5.79%Profit / capital in positions
Return on total capital4.05%Profit / total capital
Average share of capital deployedabout 70%4.05% / 5.79%

Source: trading journal of the author.

Figure 3. Evolution of the portfolio and drawdown (May-August 2026).
Evolution of the portfolio and drawdown
Source: computation by the author (data: trading journal).

In July-August, a second drawdown appeared. My journal showed that my edge was decaying: the same strategies were producing weaker results. I decided to de-risk rather than force trades. I learned that knowing when to reduce exposure is as important as knowing when to take risk, and that a strategy’s edge is not permanent.

Financial concepts related to my experience

I present below three financial concepts related to my experience: the Black-Scholes-Merton model and the option Greeks (with an equation that shows how my option positions made or lost money, and alternative ways to bet on volatility), the Kelly Criterion for position sizing, and risk-adjusted performance measures.

The Black-Scholes-Merton model and the option Greeks

The Black-Scholes-Merton model (Black and Scholes, 1973; Merton, 1973) gives a theoretical price for a European option as a function of the price of the underlying asset, the strike price, the time to maturity, the risk-free interest rate and the volatility of the underlying. Its partial derivatives, called the Greeks, measure how the option price reacts to each of these inputs: delta (price of the underlying), gamma (change in delta), vega (implied volatility), and theta (time). In my delta-neutral strategies, I kept the delta of the whole position close to zero, that is, the sum of the deltas of all the options and futures in the position, each multiplied by its quantity: Δposition = Σ ni × Δi (a future has a delta of 1 per unit of the index). Small market moves then had little impact. My profit or loss came mainly from theta and gamma, that is, from the passage of time and from the difference between implied and realized volatility, as the equation below shows. Without the model and its Greeks, I could not have measured or controlled these exposures.

The profit and loss of an option position: a second-order approximation

For a small change dS in the price of the underlying asset over a short period dt, a second-order Taylor expansion of the value V of an option position gives:

dV ≈ Δ × dS + ½ × Γ × (dS)2 + Θ × dt + ν × dσ

where Δ is the delta, Γ the gamma, Θ the theta and ν the vega of the position. The first term is linear: it is the first guess given by the delta. The second term is the convexity. It does not depend on the direction of the move because (dS)2 is always positive: for a bought option (Γ > 0, for example the purchase of a put) it is always a gain, and for a sold option (Γ < 0, for example the sale of a call) it is always a loss.

For a delta-neutral position (Δ = 0) with constant implied volatility, only gamma and theta remain. In the Black-Scholes-Merton model, theta and gamma are linked: when the interest rate is ignored, Θ = −½ × Γ × S2 × σimplied2. The profit and loss over one day can then be written as:

dV ≈ ½ × Γ × S2 × [ (dS/S)2 − σimplied2 × dt ]

The term (dS/S)2 is the squared return actually realized over the day, while σimplied2 × dt is the squared return implied by option prices. For a seller of options (Γ < 0), the day is profitable when the market moves less than implied volatility predicts, and costly when it moves more. Over many days, the seller earns money when realized volatility is below implied volatility. This is the precise meaning of “betting on volatility”, and it explains the returns of my delta-neutral positions. Empirically, implied volatility is on average higher than realized volatility on equity indexes (the volatility risk premium documented by Bakshi and Kapadia, 2003), which is what option sellers try to earn, at the cost of large losses in sudden market moves.

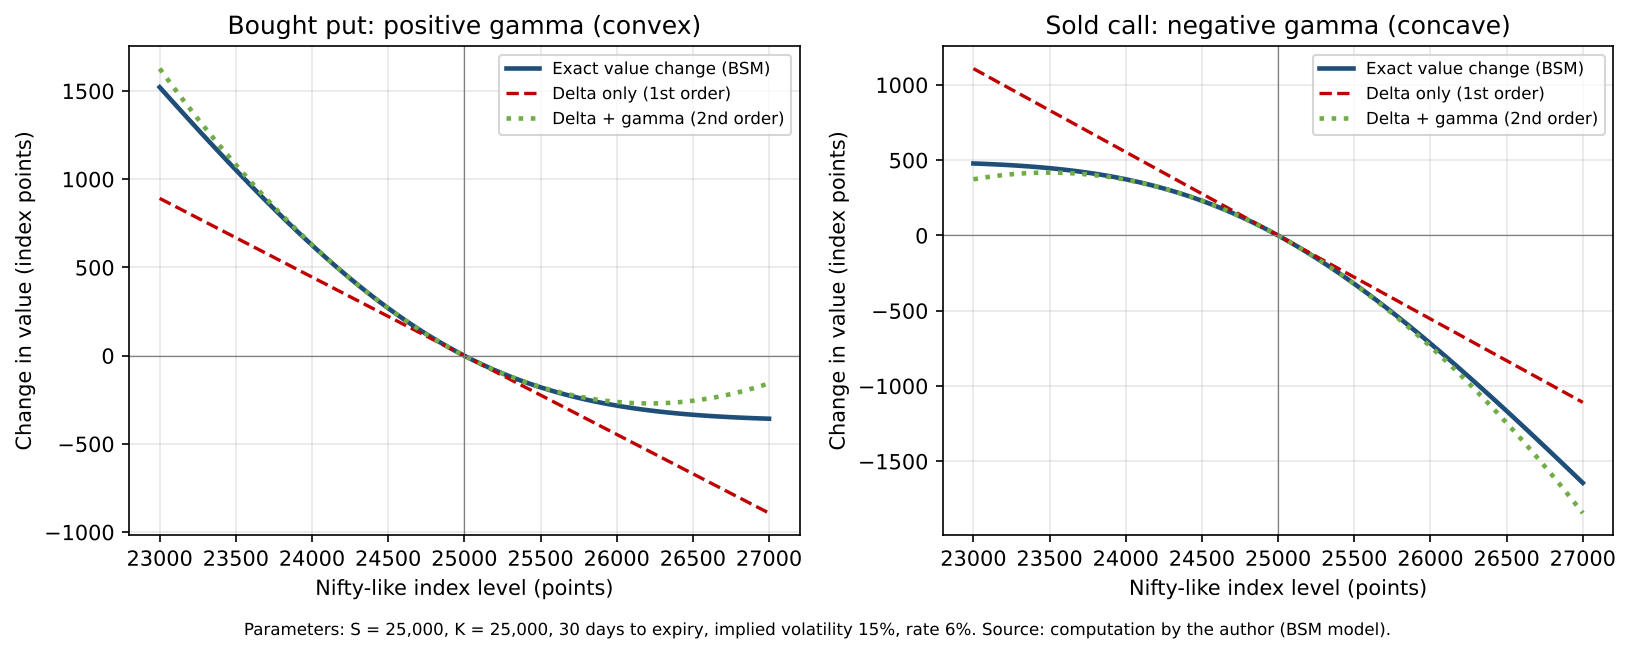
Figure 4 illustrates the convexity with two positions on an index at 25,000 points: the purchase of an at-the-money put (positive gamma) and the sale of an at-the-money call (negative gamma), both with 30 days to expiry, an implied volatility of 15% and an interest rate of 6% (illustrative parameters). The gamma of each option is 0.000368 per point. For a fall of 2,000 points (−8%), the bought put gains 1,522 points: the delta alone predicts 892 points, and adding the gamma term (+735 points) gives 1,627 points, much closer to the exact value. For moves of ±500 points (±2%), the second-order approximation is almost exact (269 points for the bought put after a fall of 500 points, against 269 points with the full model). The curve of the bought put bends upward (convex), while the curve of the sold call bends downward (concave): for a rise of 2,000 points, the sold call loses 1,643 points against 1,108 points predicted by the delta alone.

Figure 4. Change in value of a bought put and of a sold call as a function of the price of the underlying asset.
Change in value of a bought put and of a sold call as a function of the underlying price
Source: computation by the author (Black-Scholes-Merton model).

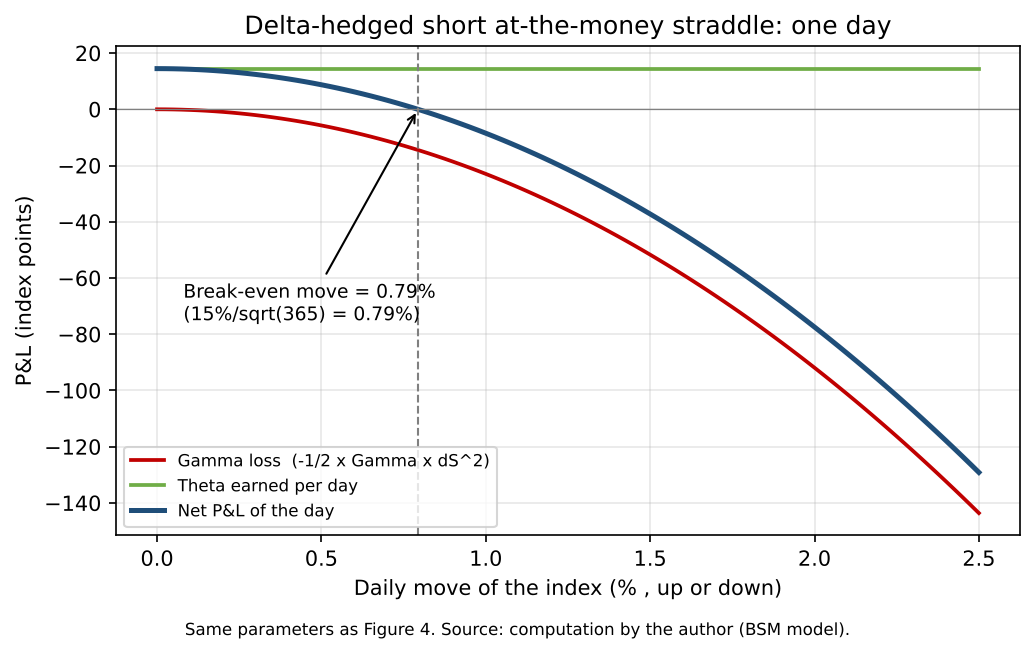
Figure 5 applies the second equation to a delta-hedged short at-the-money straddle (one call and one put sold with the same strike) with the same parameters. The position earns about 14.5 points of theta per day but loses ½ × Γ × (dS)2 when the index moves. The break-even daily move is about 198 points, or 0.79% of the index, which is almost exactly the daily move implied by an annual volatility of 15% (15% / √365 = 0.79%).

Figure 5. Profit and loss over one day of a delta-hedged short straddle as a function of the daily move of the index.
Daily profit and loss of a delta-hedged short straddle
Source: computation by the author (Black-Scholes-Merton model).

You can download below the Excel file with the tables and figures of this section (option prices and Greeks, the position as a function of the price of the underlying asset for a bought put and a sold call, the gamma-theta trade-off, and the payoffs of volatility strategies).
Download the cleaned S&P 500 index options data

Alternative strategies to bet on volatility

Selling options is only one way to take a view on volatility. Table 2 lists the main alternatives. Long-volatility strategies (positive gamma) gain when the market moves a lot and pay theta every day; short-volatility strategies (negative gamma) earn theta and lose in large moves.

Table 2. Strategies to bet on volatility.

StrategyPositionBetGammaMaximum loss
Long straddle / strangleBuy a call and a put (same strike, or out-of-the-money strikes)Large move in either direction+Premiums paid
Delta-hedged long options (gamma scalping)Buy options and re-hedge the delta with futuresRealized volatility above implied volatility+Premium paid and hedging costs
Long out-of-the-money put (tail hedge)Buy a long-dated index putMarket crash+Premium paid
Short straddle / strangleSell a call and a putCalm market, realized volatility below implied−Unlimited
Iron condorShort strangle plus a bought put and a bought call further out of the moneyIndex stays within a range−Width of the wings minus premium received
Calendar spreadSell a short-dated option and buy a longer-dated one with the same strikeCalm market now, stable or rising long-dated implied volatility−Net premium paid
Volatility index and variance productsTrade volatility directly (India VIX for NSE, variance swaps)Rise or fall of volatility itselfn/aDepends on the product (variance swaps are mainly traded by institutions)

Source: the author.

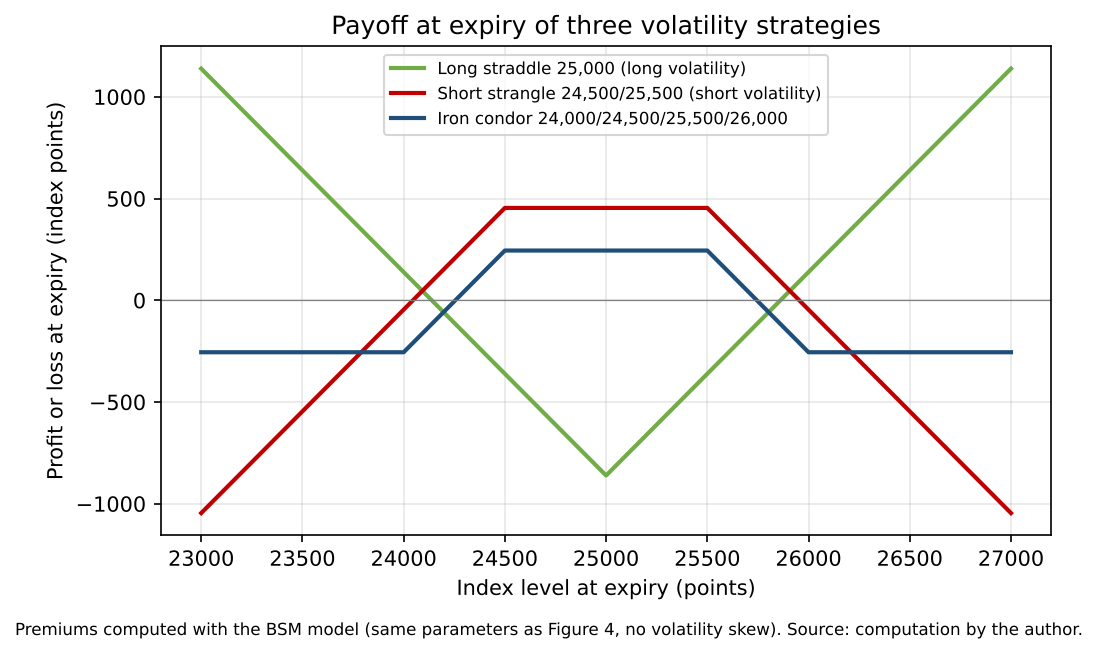
Figure 6 compares the payoff at expiry of a long straddle, a short strangle and an iron condor with the same parameters as above. The iron condor is a defined-risk version of the short strangle: with strikes at 24,000, 24,500, 25,500 and 26,000 points, it collects a net premium of 245 points and its maximum loss is capped at 255 points (the 500-point width of a wing minus the premium), whereas the loss of the short strangle has no limit. Defined-risk structures are therefore better suited to a small portfolio, where one large move must not wipe out months of theta.

Figure 6. Payoff at expiry of three volatility strategies.
Payoff at expiry of three volatility strategies
Source: computation by the author (Black-Scholes-Merton model).

The Kelly Criterion

The Kelly Criterion (Kelly, 1956) answers the question: if I have a positive edge, what fraction of my capital should I risk on each trade? It chooses the fraction that maximizes the expected logarithm of wealth, which is the same as maximizing the long-run growth rate of capital. For a trade that wins with probability p and pays b times the amount risked, the optimal fraction is f* = p − (1 − p)/b. Risking more than this lowers long-run growth and greatly increases drawdowns. I used the Kelly Criterion as an upper limit for my position sizes and in practice risked only a fraction of it, because my estimates of p and b were based on a limited number of trades. I explain this concept in detail in a separate article on the SimTrade blog.

Risk-adjusted performance measures

A return figure alone says nothing about the risk taken to obtain it. The Sharpe ratio (Sharpe, 1966) divides the excess return over the risk-free rate by the volatility of returns. The Sortino ratio (Sortino and Price, 1994) only penalizes downside volatility, which is more relevant for strategies with asymmetric returns such as options strategies. The Calmar ratio compares the annual return to the maximum drawdown, the largest fall from a peak to a trough. I tracked all three measures in my journal because they tell different stories: my drawdown in March-April 2026 hurt my Calmar ratio much more than my Sharpe ratio, which reminded me that volatility is not the only dimension of risk.

Why should I be interested in this post?

If you are a student interested in asset management, trading or derivatives, managing a real portfolio, even a small one, is one of the best ways to understand how theory meets practice. Concepts such as the Greeks, position sizing and drawdowns become very concrete when your own money, or your family’s, is at stake. This experience also shows that a good trading process is mostly about risk management, record-keeping and honest evaluation of performance, and that most individual derivatives traders lose money if they ignore these principles.

Related posts on the SimTrade blog

Professional experiences

   ▶ All posts about Professional experiences

   ▶ Youssef LOURAOUI My experience as a portfolio manager in a central bank

   ▶ William ARRATA My experiences as Fixed Income portfolio manager then Asset Liability Manager at Banque de France

   ▶ Adam MERALLI BALLOU My internship experience in Portfolio Management at Mirabaud

   ▶ Tanguy TONEL My experience as an Investment Specialist at Amundi Asset Management

   ▶ Alberto BORGIA My Experience as a Wealth Management Intern at Nextam Partners

Financial techniques

   ▶ Jayati WALIA Black-Scholes-Merton option pricing model

   ▶ Akshit GUPTA Option Greeks – Gamma

   ▶ Abel ARAYA Delta Hedging Explained: How Traders Stay Market Neutral

   ▶ Akshit GUPTA Straddle and strangle strategy

   ▶ Akshit GUPTA Protective Put

   ▶ Raphael TRAEN Understanding Correlation in the Financial Landscape: How It Drives Portfolio Diversification

Indian financial markets

   ▶ Nithisha CHALLA The Nifty 50 index

   ▶ Nithisha CHALLA Securities and Exchange Board of India (SEBI)

   ▶ Nithisha CHALLA Top 5 companies by market capitalization in India

Useful resources

Academic research

Bakshi, G., Kapadia, N. (2003) Delta-Hedged Gains and the Negative Market Volatility Risk Premium, Review of Financial Studies, 16(2), 527–566.

Black, F., Scholes, M. (1973) The Pricing of Options and Corporate Liabilities, Journal of Political Economy, 81(3), 637–654.

Gatev, E., Goetzmann, W. N., Rouwenhorst, K. G. (2006) Pairs Trading: Performance of a Relative-Value Arbitrage Rule, Review of Financial Studies, 19(3), 797–827.

Hull, J. C. (2021) Options, Futures, and Other Derivatives, Eleventh Edition, Harlow, Pearson.

Kahneman, D. (2011) Thinking, Fast and Slow, New York, Farrar, Straus and Giroux.

Kahneman, D., Tversky, A. (1979) Prospect Theory: An Analysis of Decision under Risk, Econometrica, 47(2), 263–291.

Kelly, J. L. (1956) A New Interpretation of Information Rate, Bell System Technical Journal, 35(4), 917–926.

Merton, R. C. (1973) Theory of Rational Option Pricing, Bell Journal of Economics and Management Science, 4(1), 141–183.

Sharpe, W. F. (1966) Mutual Fund Performance, Journal of Business, 39(1), 119–138.

Sortino, F. A., Price, L. N. (1994) Performance Measurement in a Downside Risk Framework, Journal of Investing, 3(3), 59–64.

Business resources

National Stock Exchange of India (NSE)

SEBI (2024) Updated SEBI study reveals 93% of individual traders incurred losses in equity F&O between FY22 and FY24

SEBI (2024) Circular of October 1, 2024: Measures to strengthen Equity Index Derivatives framework for increased investor protection and market stability.

Futures Industry Association (FIA)

CFA Institute

Sensibull

About the author

The article was written in October 2026 and revised in November 2026 by Romil SOJITRA (Indian Institute of Technology Kanpur, BS in Economics, 2024-2028).

   ▶ Discover all posts by Romil SOJITRA.
VIX Futures and Options

Saral BINDAL

In this article, Saral BINDAL (Indian Institute of Technology Kharagpur, Metallurgical and Materials Engineering, 2024–2028; Research Assistant at ESSEC Business School) examines the characteristics, pricing, and settlement of VIX futures and options, along with their term structure and market microstructure.

Introduction

The Cboe Volatility Index (VIX) is a real-time measure of the market’s expectation of S&P 500 volatility over the next 30 days. It is calculated from the prices of S&P 500 Index (SPX) options and is expressed as an annualized percentage. The VIX is widely used as a measure of expected market volatility. For more details, see the previous posts on Implied Volatility and Option Prices and Cboe Volatility Index.

The VIX itself is an index and cannot be directly bought or sold. To allow market participants to trade volatility, Cboe introduced VIX derivatives such as futures and options. VIX futures were introduced in 2004, followed by VIX options in 2006. VIX futures provide linear exposure to changes in the market’s pricing of the future level of the VIX Index, while VIX options provide nonlinear exposure, allowing investors to take positions on changes in the VIX through a range of strike prices and maturities.

VIX Futures

A VIX futures contract is a standardized agreement whose value is linked to the VIX Index at a specified future date (expiration date of the contract). A VIX futures contract reflects the market’s pricing of the VIX Index at a specified future expiration date. Its price incorporates expectations about future volatility as well as risk premia and therefore should not necessarily be interpreted as an unbiased forecast of the future VIX level. VIX futures are traded on the Cboe Futures Exchange (CFE) under the symbol VX.

The pricing of VIX futures differs from that of conventional futures on a tradable stock or stock index. For a stock, the futures price can be related to the current spot price through a cash-and-carry arbitrage relationship, typically expressed as F0 = S0e(r-q)T, where r is the interest rate and q is the dividend yield. This relationship relies on the ability to buy and hold the underlying asset. In contrast, the VIX is an index and cannot itself be directly bought or held. Therefore, the VIX futures contract does not simply represent the current VIX value carried forward to a future date. Instead, it is a market price determined by participants’ expectations about future volatility (the expected value of VIX at maturity), together with the supply and demand for volatility exposure and the risk associated with holding the contract.

VIX futures have a $1,000 contract multiplier. Therefore, a one-point change in the price of a VIX futures contract corresponds to a $1,000 change in the value of one contract.

For example, if an investor buys one VIX futures contract at 20 and its price subsequently rises to 23, the change of 3 VIX points corresponds to a gain of:

VIX Futures Calculation Example

before transaction costs and any financing or opportunity costs associated with margin requirements.

Transaction Costs

Trading VIX derivatives involves both explicit (commissions and fees) and implicit (price impact) transaction costs. These affect the cost of entering and exiting positions and, ultimately, strategy performance. These costs can be broken down into the following components:

Brokerage commissions: Fees charged by brokers for executing trades.

Exchange transaction fees: Fees levied by the exchange on executed contracts.

Clearing and regulatory fees: Charges associated with clearing trades and applicable regulatory requirements.

Bid-ask spread: The difference between the best available ask and bid prices. Crossing the spread creates an immediate execution cost, which varies with market liquidity and volatility.

Slippage: The difference between the expected and actual execution prices. It can arise from market movements, order size and limited liquidity, particularly during periods of elevated volatility.

Margin Requirements and Costs

Unlike transaction costs, margin is not a fee paid to execute a trade. It is the collateral required to maintain a derivatives position, tying up capital that could otherwise be deployed elsewhere.

When opening a position, a trader must meet the initial margin requirement. As the position is marked to market, gains and losses affect the account balance. If losses reduce the balance below the maintenance margin requirement, additional funds may be needed to keep the position open.

The cost of margin therefore lies primarily in the capital committed to the trade and its associated opportunity cost. Traders may also incur financing costs if they borrow funds to meet margin requirements. These considerations become particularly important in VIX derivatives, where margin requirements can change with market conditions and increase during periods of elevated volatility.

Settlement of VIX Futures

VIX futures are cash-settled. Unlike futures on physical commodities, there is no delivery of an underlying asset at expiration because the VIX itself is an index and not a traded asset. Instead, the final profit or loss is determined using the final settlement value of the contract.

The final settlement value is determined on the morning of the expiration date, usually a Wednesday, through a Special Opening Quotation (SOQ) of the VIX Index. The SOQ is calculated using the VIX methodology applied to the relevant SPX options and determines the final settlement value of the VIX futures contract. As expiration approaches, the futures price converges toward this settlement value, reflecting the contract’s approaching expiration.

For a long VIX futures position, the profit or loss at settlement can be represented as:

VIX Futures Payoff Formula

For example, suppose an investor purchases one VX futures contract at 20. If the final settlement value is 28, the investor receives:

VIX Futures Calculation Example 2

Thus, the cash-settlement mechanism allows investors to gain or lose based on changes in the market’s pricing of volatility without owning the underlying SPX options used in the VIX calculation.

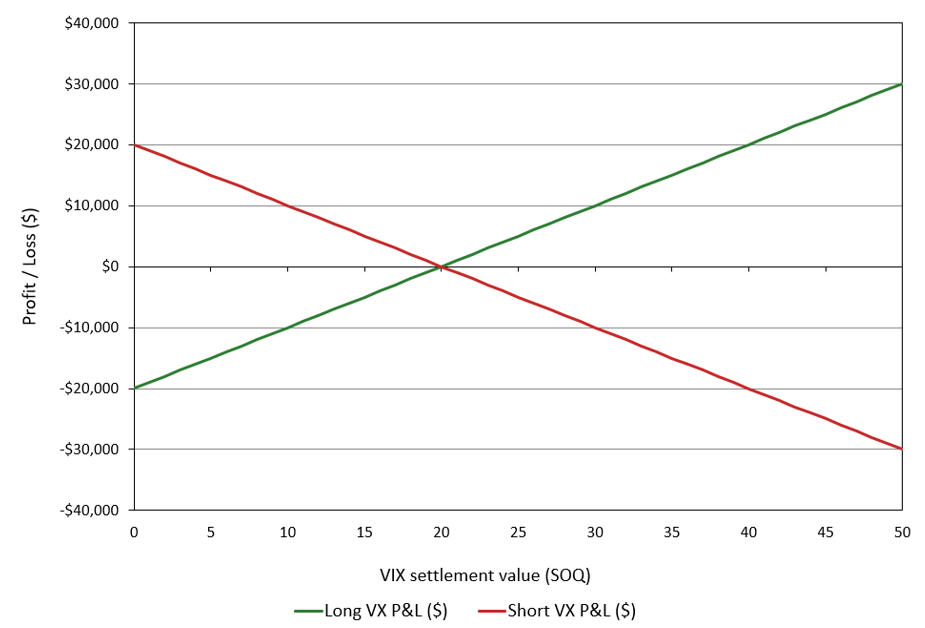
Figure 1 below illustrates the VIX Futures P&L at Settlement for both long and short positions as a function of the VIX value at maturity, for a VX futures contract bought (long) or sold (short) at a futures price of 20. The contract has a multiplier of $1,000 per index point and is cash-settled at maturity at the Special Opening Quotation (SOQ) of the VIX Index.

Figure 1. VIX Futures P&L at Settlement
VIX Futures P&L at Settlement
Source: computation by the author.

VIX Futures Term Structure

A term structure exists because VIX futures contracts have different expiration dates and therefore reflect market expectations over different future periods. As the time to expiration changes, the information, uncertainty, and expected volatility associated with that future period also change, causing futures contracts with different maturities to trade at different prices.

An upward-sloping term structure indicates that VIX futures with later expiration dates are priced at higher VIX levels than contracts with nearer expirations. This is known as contango. By contrast, a downward-sloping term structure indicates that VIX futures with later expiration dates are priced at lower VIX levels than contracts with nearer expirations. This is known as backwardation.

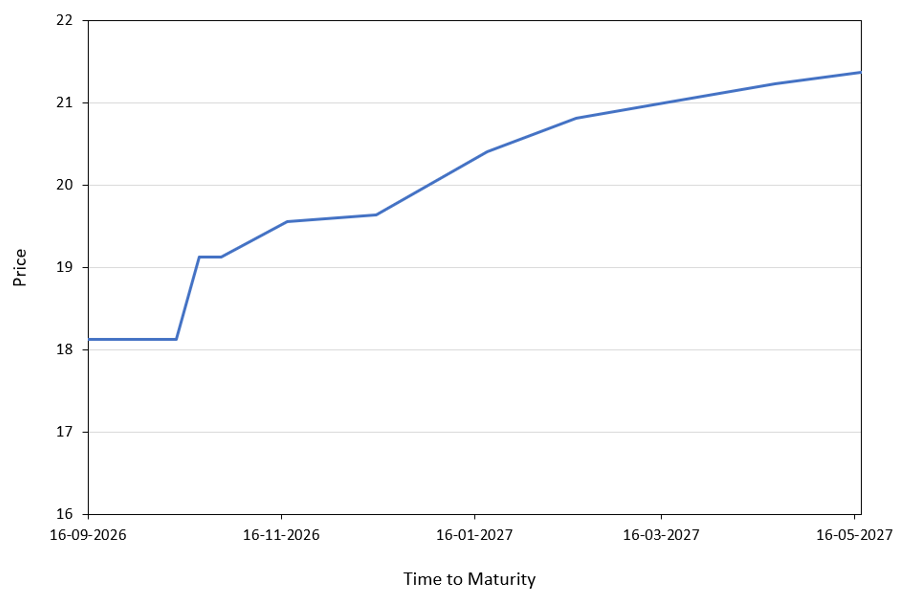
Figure 2 below illustrates the VIX Futures Term Structure using data obtained from Cboe, covering expiration dates from September 16, 2026, to May 18, 2027. The figure shows an upward-sloping curve, indicating a state of contango. This suggests that VIX futures contracts with later expiration dates are priced at higher levels than those with nearer expirations, indicating that the market assigns higher prices to longer-dated volatility exposure.

Figure 2. VIX Futures Term Structure (September 2026)
VIX Futures Term Structure
Source: computation by the author (Cboe data).

This term structure has implications for investors who maintain long positions in VIX futures. As contracts approach expiration, investors seeking to maintain their exposure must sell the expiring contracts and buy later-dated ones. In a contango market, longer-dated futures contracts trade at higher prices than nearer-dated contracts. Maintaining a long futures exposure therefore involves replacing expiring contracts with higher-priced contracts. Although contango can create a negative roll effect for long futures strategies, the realized return depends on subsequent changes in futures prices and the specific rolling strategy. For long positions, this can create a drag on returns as futures prices evolve toward settlement. However, the outcome depends on how futures prices change over time, rather than on contango alone. The relationship between trading demand, futures pricing and the term structure is discussed further in the market microstructure section below.

VIX Options

VIX options are exchange-traded derivatives that provide nonlinear exposure to the VIX settlement value at expiration. Their pricing is closely related to the corresponding VIX futures contract rather than solely to the current spot level of the VIX Index. VIX options are traded on Cboe Options Exchange and are based on the Cboe Volatility Index (VIX). Unlike individual stocks in stock options, the VIX is itself an index derived from prices of S&P 500 Index (SPX) options.

Cboe offers both monthly and weekly VIX option expirations, providing market participants with different maturities for expressing views on volatility.

Each VIX option contract has a $100 multiplier. Therefore, the dollar value of an option is obtained by multiplying its quoted premium by $100.

For example, if an investor buys one VIX call option with a strike price of 20 and the VIX settlement value is 15 at expiration, the option finishes 5 VIX points out-of-the-money. Consequently, the option expires worthless, with a payoff of zero (before accounting for the premium paid, transaction costs, and other applicable charges).

Settlement of VIX Options

VIX options are cash-settled. This means that there is no physical delivery of an underlying asset when an option is exercised. Instead, the value of an exercised option is determined using the final settlement value of the VIX.

The final settlement value is determined on the morning of the expiration date, usually a Wednesday through a Special Opening Quotation (SOQ) of the VIX Index. The SOQ is calculated using the VIX methodology applied to the relevant SPX options and is used to determine the final settlement value of the VIX option.

For a VIX call option, the settlement value is based on the amount by which the final VIX settlement value exceeds the strike price, and for a VIX put option, the settlement value is based on the amount by which the strike price exceeds the final VIX settlement value.

For a call option, this can be represented as:

VIX Call Option Payoff Formula

For a put option:

VIX Put Option Payoff Formula

For example, suppose an investor holds a VIX call option with a strike price of 20 and the final settlement value is 28. The option’s settlement value is:

VIX Options Calculation Example 2

If the final settlement value is below 20, the call expires without value.

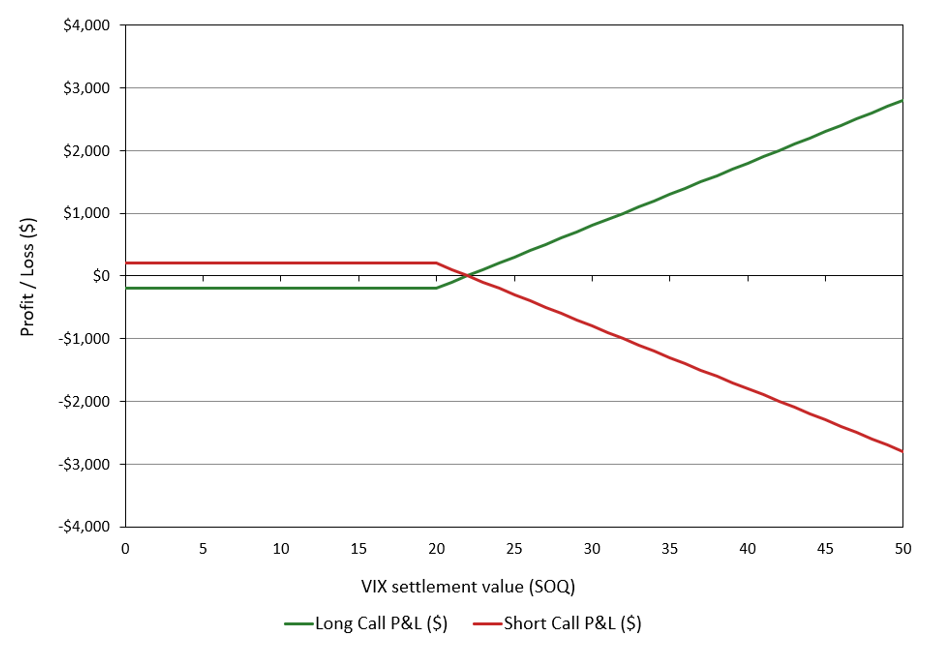
Figure 3 illustrates the P&L at expiration for long and short VIX call positions as a function of the VIX value at maturity. For a strike price of 20, a premium of 2.00 VIX points, and a $100 multiplier, the long call has a maximum loss of $200 when the VIX settles at or below 20 and unlimited gain above the breakeven level of 22. VIX options are cash-settled at expiration based on the VIX SOQ.

Figure 3. VIX Call Option P&L at Settlement
VIX Call Option P&L at Settlement
Source: computation by the author.

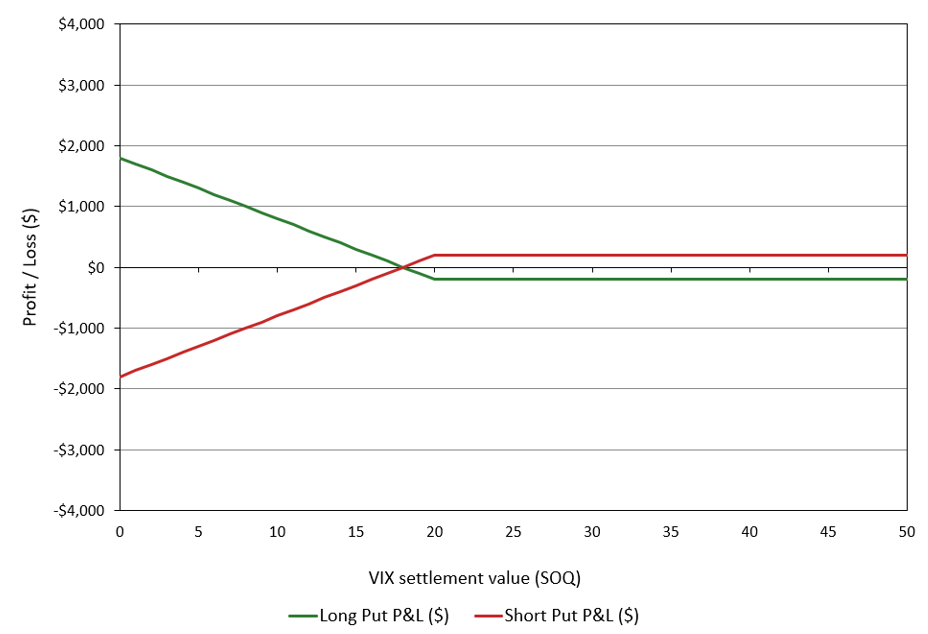
Figure 4 illustrates the P&L at expiration for long and short VIX put positions as a function of the VIX value at maturity. For a strike price of 20, a premium of 2.00 VIX points, and a $100 multiplier, the long put has a maximum loss of $200 when the VIX settles at or above 20 and becomes profitable below the breakeven level of 18. VIX options are cash-settled at expiration based on the VIX SOQ.

Figure 4. VIX Put Option P&L at Settlement
VIX Put Option P&L at Settlement
Source: computation by the author.

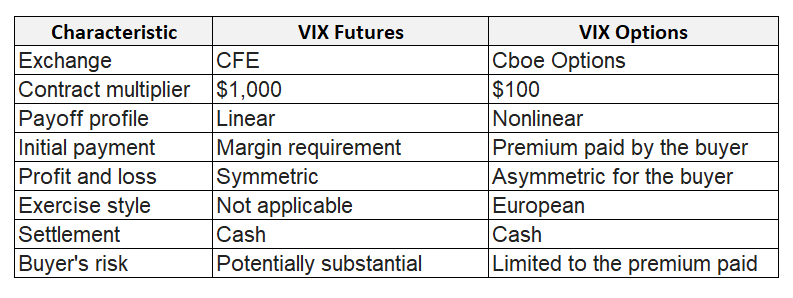
The table below summarizes the key characteristics of VIX futures and options contracts discussed above.

Figure 5. Key Characteristics of VIX Futures and VIX Options
 Key Characteristics of VIX Futures and VIX Options
Source: computation by the author.

Market Participants

VIX futures and options involve several types of market participants with different objectives.

Institutional investors and asset managers may use VIX derivatives to hedge portfolios against changes in market volatility.

Hedge funds and proprietary trading firms may use VIX futures and options to speculate on future movements in volatility or implement volatility-related strategies.

Market makers provide liquidity by quoting prices at which they are willing to buy and sell VIX derivatives, facilitating trading in these instruments.

Individual investors can also access VIX futures and options through eligible brokers, subject to account approval, margin requirements and regional availability. They may use these instruments to speculate on changes in expected market volatility or to hedge equity-market exposure. However, access to these products does not imply that they are suitable for all investors, given their leverage, complexity and potential for substantial losses.

Other market participants may combine VIX futures, VIX options, SPX options, and other volatility-related instruments to construct different trading and hedging strategies.

Market Microstructure

Prices in financial markets emerge from the interaction between buyers and sellers. In the conventional microeconomic framework, the demand curve represents the quantities buyers are willing to purchase at different prices, while the supply curve represents the quantities sellers are willing to offer. Their intersection determines the market equilibrium, where quantity demanded equals quantity supplied. In practice, trading mechanisms can take different forms like an electronic order book or block trading arrangements for large transactions. Demand and supply are influenced by market participants’ expectations of future prices (volatility for VIX futures and option markets).

VIX futures and options are traded on electronic markets where buyers and sellers submit orders. Market participants can use different order types, particularly market orders and limit orders. In the VIX futures market, limit orders are recorded in an electronic order book, which displays outstanding buy and sell orders along with their prices and quantities. Incoming orders are matched against existing orders according to the exchange’s matching rules. The highest price buyers are willing to pay is the best bid, while the lowest price sellers are willing to accept is the best ask. The difference between these two prices is the bid-ask spread, which represents an important component of transaction costs. Market depth refers to the quantities available for trading at different price levels. Together, the bid-ask spread and market depth provide useful indicators of market liquidity and the potential price impact of executing an order.

VIX options also trade electronically. Market makers provide quotes and may supply liquidity by taking the opposite side of a trade. Multi-leg strategies, such as vertical spreads, present an additional execution challenge because the trader needs to buy and sell options at a suitable combined price. Cboe’s Complex Order Book (COB) allows these orders to be matched as a combined position, while its Complex Order Auction (COA) gives eligible orders an opportunity for price improvement.

For large VIX futures positions, block trades offer an alternative to execution through the displayed order book. Eligible counterparties can negotiate a transaction privately and report it to the exchange under the applicable rules. This can help participants execute large orders without relying entirely on the liquidity available in the electronic market.

Trading prices also differ from the value used to settle contracts at expiration. VIX futures and options are cash-settled using the Special Opening Quotation (SOQ) of the VIX Index on the final settlement date. Unlike the regular VIX calculation, which uses bid-ask midpoints from SPX options across two expirations, the SOQ uses opening trade prices from a single SPX option expiration selected to provide the required 30-day measure. If a selected option has no opening trade price, its bid-ask midpoint is used instead. The resulting SOQ determines the final settlement value of the expiring derivatives.

Price Formation in VIX Futures

A VIX futures price reflects the price at which market participants are willing to trade exposure to the VIX Index at a specified future expiration. It is not necessarily an unbiased forecast of the VIX level at that date. The VIX measures expected 30-day volatility derived from S&P 500 index options, whereas a VIX futures contract provides exposure to the value of this index at its own expiration. Futures prices therefore reflect expectations about future volatility conditions, risk premia and the balance of buying and selling pressure.

The relationship between futures prices across expiration dates is described by the VIX futures term structure. In contango, longer-dated contracts trade above nearer-dated contracts; in backwardation, nearer-dated contracts trade above longer-dated ones. Contango is frequently observed in relatively calm markets, while backwardation can emerge during periods of market stress, when demand for near-term volatility exposure increases sharply. However, an upward-sloping futures curve does not necessarily imply that the market expects the spot VIX to rise. The curve also reflects risk premia and supply and demand for volatility exposure across different maturities.

Trading activity can influence both the overall level of futures prices and the relative pricing of contracts with different expiration dates. Mixon and Onur (2019) examine how non-dealer trading activity relates to VIX futures pricing. Their findings highlight the role of aggregate net demand in the overall level of futures prices and the relationship between trading activity in individual contracts and the shape of the futures curve. This is relevant to the roll effect, which describes the contribution to returns from replacing a futures contract approaching expiration with a later-dated contract. In contango, maintaining a long position typically involves selling a nearer-dated contract and buying a more expensive deferred contract. This can create a headwind for returns, although the realised outcome depends on subsequent futures-price movements and the investor’s rolling strategy.

Price Formation in VIX Options

The price of a VIX option depends on the possible VIX settlement values at expiration relative to the option’s strike price. A call option has a positive payoff when the final settlement value exceeds the strike, while a put option has a positive payoff when the settlement value falls below the strike. The option premium reflects the potential payoffs, the time remaining until expiration, interest rates and the market’s assessment of the distribution of possible settlement values.

VIX futures play an important role in standard VIX option valuation. Because the VIX Index itself is not directly tradable, VIX futures provide market-based information about volatility priced for specific future dates. The relevant futures price is an important input in option valuation, but it does not determine the option premium on its own. The strike price, time to expiration, interest rates and the distribution of possible settlement values also influence the premium.

Option prices vary across strike prices and expiration dates. Implied volatility, calculated from observed option premiums using an option-pricing model, provides a common measure for comparing these prices. The implied volatility skew describes variation in implied volatility across strike prices, while the term structure describes variation across option maturities. These patterns show how the market prices options with different payoff profiles and maturities.

Tong, Huang and Wang (2022) compare VIX option pricing models that use the VIX Index and VIX futures as state variables, meaning market variables used as model inputs. Their findings indicate that models incorporating VIX futures prices perform better empirically than models relying on the VIX Index alone and several alternative market variables. This highlights the importance of futures-market information in modelling and valuing standard VIX options.

Trading Activity and Market Liquidity

In this section, we examine the trading activity and relative scale of the S&P 500 and VIX derivatives markets by comparing the average daily volumes of their futures and options contracts. The data are sourced from CME Group and Cboe.

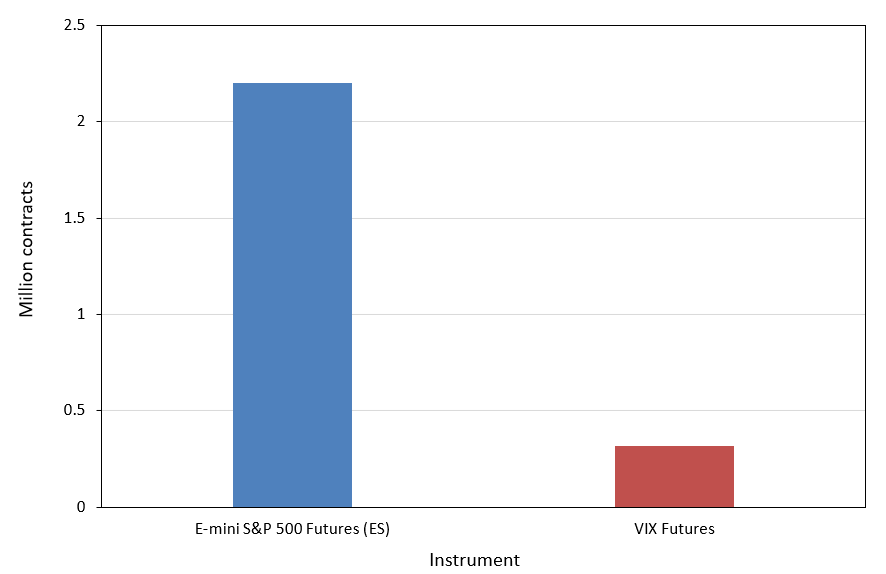
Figure 6 below compares the average daily trading volume of E-mini S&P 500 futures and VIX futures in March 2026. E-mini S&P 500 futures (ES) are standardized futures contracts on the S&P 500 Index, with a contract multiplier of $50 per index point. ES recorded an average daily volume of 2.2 million contracts (CME Group), compared with 0.318 million contracts for VIX futures (Cboe).

Figure 6. Average daily number of contracts of S&P 500 and VIX futures (March 2026)
Average Daily Number of Contracts of S&P 500 and VIX Futures, March 2026
Source: computation by the author (CME Group and Cboe data).

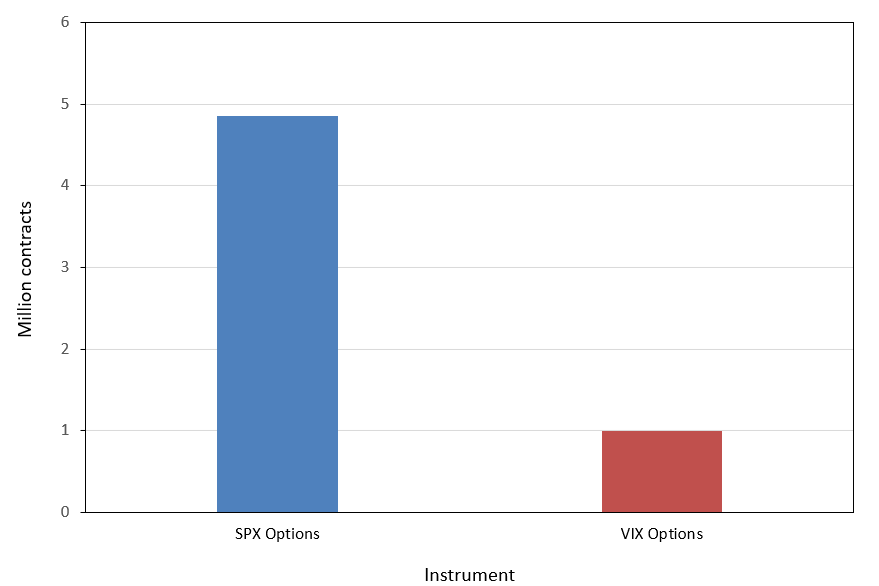
Figure 7 below compares the average daily number of contracts (a proxy for trading activity) of S&P 500 Index (SPX) options and VIX options during Q1 2026. SPX options recorded an average daily volume of 4.855 million contracts (Cboe), while VIX options recorded 0.994 million contracts (Cboe). The figures represent average daily volume across January, February, and March 2026.

Figure 7. Average daily number of contracts of S&P 500 and VIX options (Q1 2026)
Average Daily Number of Contracts of S&P 500 and VIX Options (Q1 2026)
Source: computation by the author (Cboe data).

The figures provide an indication of the relative trading activity in S&P 500 and VIX derivatives, but they should be interpreted with caution. Average daily trading volume, measured in contracts, differs from the monetary or notional value of transactions. A higher contract volume does not necessarily imply a proportionally larger market in terms of economic exposure or liquidity. Furthermore, trading volume alone does not fully capture liquidity, which also depends on bid-ask spreads, market depth (number of contracts available in the market at a given price), and execution costs (bid-ask spreads, commissions, and the price impact of a trade). Therefore, the figures are best interpreted as a comparison of trading activity rather than a direct measure of market size or relative liquidity.

Why should I be interested in this post?

VIX futures and options are important instruments for market participants to take positions on future volatility, hedge portfolios against changes in volatility, and manage exposure to market risk. Understanding these instruments therefore provides a practical perspective on the management of volatility risk in financial markets.

Related posts on the SimTrade blog

Futures

   ▶ Akshit GUPTA Futures Contract

   ▶ Alexandre VERLET Understanding financial derivatives: futures

Options

   ▶ Akshit GUPTA Options

   ▶ Jayati WALIA Black-Scholes-Merton Option Pricing Model

   ▶ Jayati WALIA Implied Volatility

   ▶ Saral BINDAL Implied Volatility and Option Prices

VIX

   ▶ Youssef LOURAOUI VIX index

   ▶ Saral BINDAL Cboe Volatility Index

   ▶ Saral BINDAL VIX Data and Statistical Properties

Useful resources

Business resources

CME Group (2026) March 2026 Trading Volume.

Cboe Global Markets (2026) March 2026 Monthly Volume Statistics.

Cboe Global Markets (2026) VIX Futures.

Cboe Global Markets (2026) VIX Options.

Academic references

Black F. (1976) The pricing of commodity contracts, Journal of Financial Economics, 3, 167-179.

Carr P. and L. Wu (2006) A tale of two indices. The Journal of Derivatives, 13(3), 13-29.

Mixon S. and Onur E. (2019) Derivatives Pricing When Supply and Demand Matter: Evidence from the Term Structure of VIX Futures. The Journal of Futures Markets, 39(9), 1035-1055.

Tong C., Huang Z. and Wang T. (2022) Do VIX Futures Contribute to the Valuation of VIX Options? The Journal of Futures Markets, 42(9), 1644-1664.

Whaley R. E. (2009) Understanding the VIX. The Journal of Portfolio Management, 35(3), 98-105.

Zhang J. E. and Y. Zhu (2006) VIX futures. Journal of Futures Markets, 26(6), 521-531.

About the author

The article was written in October 2026 by Saral BINDAL (Indian Institute of Technology Kharagpur, Metallurgical and Materials Engineering, 2024-2028 & Research assistant at ESSEC Business School). His interests include tracking geopolitical developments and analyzing their direct impact on macroeconomic factors such as inflation, trade balances, and currency volatility, with a focus on using data to quantify these global economic ripple effects.

Discover all posts by Saral BINDAL

Measures and statistics of business activity in global derivative markets

Saral BINDAL

In this article, Saral BINDAL (Indian Institute of Technology Kharagpur, Metallurgical and Materials Engineering, 2024-2028 & Research assistant at ESSEC Business School) explains how the business of derivatives markets has evolved over time and the pivotal role of the Black–Scholes–Merton option pricing model in their development.

Introduction

The derivatives market is among the most dynamic segments of global finance, serving as a tool for risk management, speculation, and price discovery across diverse asset classes. Spanning from bespoke over-the-counter contracts to standardized exchange-traded instruments, derivatives have become indispensable for investors, institutions, and corporations alike.

This post explores the derivatives landscape, examining market structures, contract types, underlying assets, and key statistics of business activity. It also highlights the pivotal role of the Black–Scholes–Merton model, which provided a theoretical framework for options pricing and catalysed the growth of derivatives markets.

Types of derivatives markets

The derivatives market can be categorized according to their market structure (over-the-counter derivatives and exchange-traded derivatives), the types of derivatives contracts traded (futures/forward, options, swaps), and the underlying asset classes involved (equities, interest rates, foreign exchange, commodities, and credit), as outlined below.

Market structure: over-the-counter derivatives and exchange-traded derivatives

Over-the-counter derivatives are privately negotiated, customized contracts between counterparties like banks, corporates, and hedge funds, traded via phone or electronic networks. OTC derivatives offer high flexibility in terms (price, maturity, quantity, delivery) but are less regulated, with decentralized credit risk management, no central clearing, low price transparency, and higher counterparty risk. They suit specialized or low-volume trades and often incubate new products.

Exchange-traded derivatives are standardized contracts traded on organized exchanges with publicly reported prices. Trades are cleared through a central clearing house that guarantees settlement, with daily marking-to-market and margining to reduce counterparty risk. ETDs are more regulated, transparent, and liquid, making them ideal for high-volume, widely traded instruments, though less flexible than OTC contracts.

Types of derivatives contracts

A derivative contract is a financial instrument that derives its values from an underlying asset. The four major types of such instruments are explained below.

A forward contract is a private agreement to buy or sell an asset at a fixed future date and price. It is traded over the counter between two counterparties (e.g., banks or clients). One party takes a long position (agrees to buy), the other a short position (agrees to sell). Settlement happens only at maturity, and contracts are customized, unregulated, and expose parties to direct counterparty risk.

A futures contract has the same economic purpose as a forward, future delivery at a fixed price, but is traded on an exchange with standardized terms. A clearing house stands between buyers and sellers and guarantees performance. Futures are marked to market daily so gains and losses are realized continuously. They are regulated, more transparent, and carry lower counterparty risk than forwards.

Options are contracts that give the holder the right but not the obligation to buy (call) or sell (put) an asset at a fixed strike price by a given expiration date. The buyer pays an upfront premium to the writer. If the option expires unexercised, the buyer loses only the premium. If exercised, the writer bears the payoff. Options can be American (exercise anytime) or European (exercise only at expiry) and are traded both on exchanges (standardized) and OTC (customized).

Swaps are bilateral contracts to exchange streams of cash flows over time, typically based on fixed versus floating interest rates or other reference indices. Payments are calculated on a notional principal that is not exchanged. Swaps are core OTC instruments for managing interest rate and financial risk.

Types of underlying asset classes

Underlying assets are the products on which a derivative instrument or contract derives its value. The most commonly traded underlying assets are explained below.

Equity derivatives include futures and options on stock indices, such as the S&P 500 Index. These instruments offer capital-efficient ways to manage market risk and enhance returns. Through index futures, institutional investors can achieve cost-effective hedging by locking in prices, while index options provide a non-linear, asymmetric payoff structure that protects against tail risk. Furthermore, equity swaps allow for the seamless exchange of total stock returns for floating interest rates, providing exposure to specific market segments without the capital requirements of direct physical ownership.

Interest rate derivatives include swaps and futures that help manage interest rate risk. Interest rate swaps involve exchanging fixed and floating payments, protecting banks against mismatches between loan income and deposit costs. Interest rate futures allow investors to lock in future borrowing or investment rates and provide insight into market expectations of monetary policy.

Commodity derivatives hedge price risk arising from storage, delivery, and seasonal supply-demand fluctuations. Forwards and futures on crude oil, natural gas, and power are widely used.

Foreign exchange derivatives include forward contracts and cross-currency swaps, allowing firms to hedge currency risk. Cross-currency swaps also support local currency bond markets by enabling hedging of interest and exchange rate risk.

Credit derivatives transfer the risk of default between counterparties. The most widely used is the credit default swap (CDS), which acts like insurance: the buyer pays a premium to receive compensation if a reference entity default.

Quantitative measures of derivatives market activity and size

This section presents the principal measures or statistics used to evaluate the size of the derivatives markets, covering both over-the-counter and exchange-traded instruments, the different derivatives products, and asset classes.

Notional outstanding and gross market value are the primary measures used to assess the size and economic exposure of OTC derivatives markets, while ETDs are typically evaluated using indicators such as open interest and trading volume.

Notional amount

Notional amount, or notional outstanding, is the total principal or reference value of all outstanding derivatives contracts. It captures the overall scale of positions in the derivatives market without reflecting actual market risk or cash exchanged.

For example let us consider a FX forward contract in which two parties agree to exchange $50 for euros in three months at a predetermined exchange rate. The notional amount is $50, because all cash flows (and gains or losses) from the contract are calculated with reference to this amount. No money is exchanged when the contract is initiated, and at maturity only the difference between the agreed exchange rate and the prevailing market rate determines the gain or loss computed on the $50 notional.

Now consider a call option on a stock with a strike price of $50. The notional amount is $50. The option buyer pays only an upfront premium, which is much smaller than $50, but the payoff of the option at maturity depends on how the market price of the stock compares to this $50 reference value.

When measuring notional outstanding in the derivatives market, the notional amounts of all individual contracts are simply added together. For example, one FX forward with a notional of $50 and two option contracts each with a notional of $50 result in a total notional outstanding of $150. This aggregated figure indicates the overall scale of derivatives activity, but it typically overstates actual economic risk because contracts may offset each other and only a fraction of the notional is ever exchanged.

Gross market value

Gross market value is the sum of the absolute values of all outstanding derivatives contracts with either positive or negative replacement (mark-to-market) values, evaluated at market prices prevailing on the reporting date. It reflects the potential scale of market risk and financial risk transfer, showing the economic exposure of a dealer’s derivatives positions in a way that is comparable across markets and products.

To continue the previous FX forward example, suppose a dealer has two outstanding FX forward contracts, each with a notional amount of $50. Due to movements in exchange rates, the first contract has a positive replacement value of $0.50 (the dealer would gain $0.50 if the contract were replaced at current market prices), while the second contract has a negative replacement value of –$0.40. The gross market value is calculated as the sum of the absolute values of these replacement values: |0.50| + |−0.40| = $0.90. Although the total notional outstanding of the two contracts is $100, the gross market value is only $0.90. This measure therefore reflects the dealer’s actual economic exposure to market movements at current prices, rather than the contractual size of the positions.

When this concept is extended to the entire derivatives market, the same distinction becomes apparent at a global scale. While the global derivatives market is often described as having hundreds of trillions of dollars in notional outstanding (approximately USD 850 trillion for OTC derivatives), the economically meaningful exposure is an order of magnitude smaller when measured using gross market value. Unlike notional amounts, gross market value aggregates current mark-to-market exposures, making it a more meaningful and comparable indicator of market risk and financial risk transfer across products and markets.

Open Interest

Open interest refers to the total number of outstanding derivative contracts that have not been closed, expired, or settled. It is calculated by adding the contracts from newly opened trades and subtracting those from closed trades. Open interest serves as an important indicator of market activity and liquidity, particularly in exchange-traded derivatives, as it reflects the level of active positions in the market. Measured at the end of each trading day, open interest is widely used as an indicator of market sentiment and the strength behind price trends.

For example on an exchange, a total of 100 futures contracts on crude oil are opened today. Meanwhile, 30 existing contracts are closed. The open interest at the end of the day would be: 100 (new contracts) − 30 (closed contracts) = 70 contracts. This indicates that 70 contracts remain active in the market, representing the total number of positions that traders are holding.

Trading Volume

Trading volume measures the total number of contracts traded over a specific period, such as daily, monthly, or annually. It provides insight into market liquidity and activity, reflecting how actively derivatives contracts are bought and sold. For OTC markets, trading volume is often estimated through surveys, while for exchange-traded derivatives, it is directly reported.

Consider the same crude oil futures market. If during a single trading day, 50 contracts are bought and 50 contracts are sold (including both new and existing positions), the trading volume for the day would be: 50 + 50 = 100 contracts

Here, trading volume shows how active the market is on that day (flow), while open interest shows how many contracts remain open at the end of the day (stock). High trading volume with low open interest may indicate rapid turnover, whereas high open interest with rising prices can signal strong bullish sentiment.

Key sources of statistics on global derivatives markets

Bank for International Settlements (BIS)

The Bank for International Settlements (BIS) provides quarterly statistics on exchange-traded derivatives (open interest and turnover in contracts, and notional amounts) and semiannual data on OTC derivatives outstanding (notional amounts and gross market values across risk categories like interest rates, FX, equity, commodities, and credit). All the data used in this post has been sourced from the BIS database.

Data are collected from over 80 exchanges for ETDs and via surveys of major dealers in 12 financial centers for OTC derivatives. BIS ensures comparability by standardizing definitions, consolidating country-level data, halving inter-dealer positions to avoid double counting, and converting figures into USD. Interpolations are used to fill gaps between triennial surveys, ensuring consistent time series for analysis.

International Swaps and Derivatives Association (ISDA)

ISDA develops and maintains standardized reference data and contractual frameworks that underpin global OTC derivatives markets. This includes machine-readable definitions and value lists for core market terms such as benchmark rates, floating rate options, currencies, business centers, and calendars, primarily derived from ISDA documentation (notably the ISDA Interest Rate Derivatives Definitions). The data are distributed via the ISDA Library and increasingly designed for automated, straight-through processing.

ISDA’s standards are created and updated through industry working groups and are widely used to support trade documentation, confirmation, clearing, and regulatory reporting. Initiatives such as the Common Domain Model (CDM) and Digital Regulatory Reporting (DRR) translate market conventions and regulatory requirements across multiple jurisdictions into consistent, machine-executable logic. While ISDA does not publish comprehensive market volume statistics, its frameworks play a central role in harmonizing OTC derivatives markets and enabling reliable post-trade transparency.

Futures Industry Association (FIA)

Futures Industry Association (FIA), via FIA Tech, provides comprehensive derivatives data including position limits, exchange fees, contract specifications, and trading volumes for futures/options across global products.

Sources aggregate from exchanges, indices (1,800+ products, 100,000+ constituents), and regulators for reference data like symbologist and corporate actions. The process involves standardizing data into consolidated formats with 500+ attributes, automating regulatory reporting (e.g., CFTC ownership/control), and ensuring compliance via databanks.

How to get the data

The data discussed in this article is drawn from the BIS, FIA and Visual Capitalist. For comprehensive statistics on global derivatives markets (both over-the-counter (OTC) and exchange-traded derivatives (ETDs)), the data are available at https://data.bis.org/ and for exchange-traded derivatives specifically, detailed data are provided by the Futures Industry Association (FIA) through its ETD volume reports, accessible at https://www.fia.org/etd-volume-reports. Data on equity spot market and real economy sectors are sourced from Visual Capitalist.

Derivatives market business statistics

Global derivatives market

In this section, we focus on two core measures of derivatives market activity and size: the notional amount outstanding and the gross market value, which together provide complementary perspectives on the scale of contracts and the associated economic exposure.

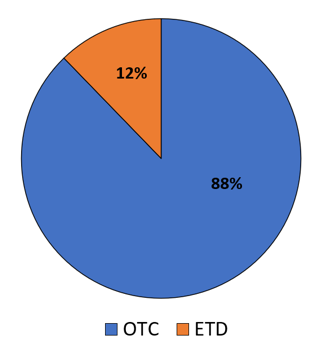
As of 30th July 2025, the global derivatives market is estimated to have an outstanding notional value of approximately USD 964 trillion, according to the Bank for International Settlements (BIS). As illustrated in the figure below, the market is largely dominated by over-the-counter (OTC) derivatives, which account for nearly 88% of total notional amounts, whereas exchange-traded derivatives (ETDs) represent a comparatively smaller share of about USD 118 trillion.

Figure 1. Derivatives Markets: OTC versus ETD (2025)
Derivatives Markets: OTC and ETD (2025)
Source: computation by the author (BIS data of 2025).

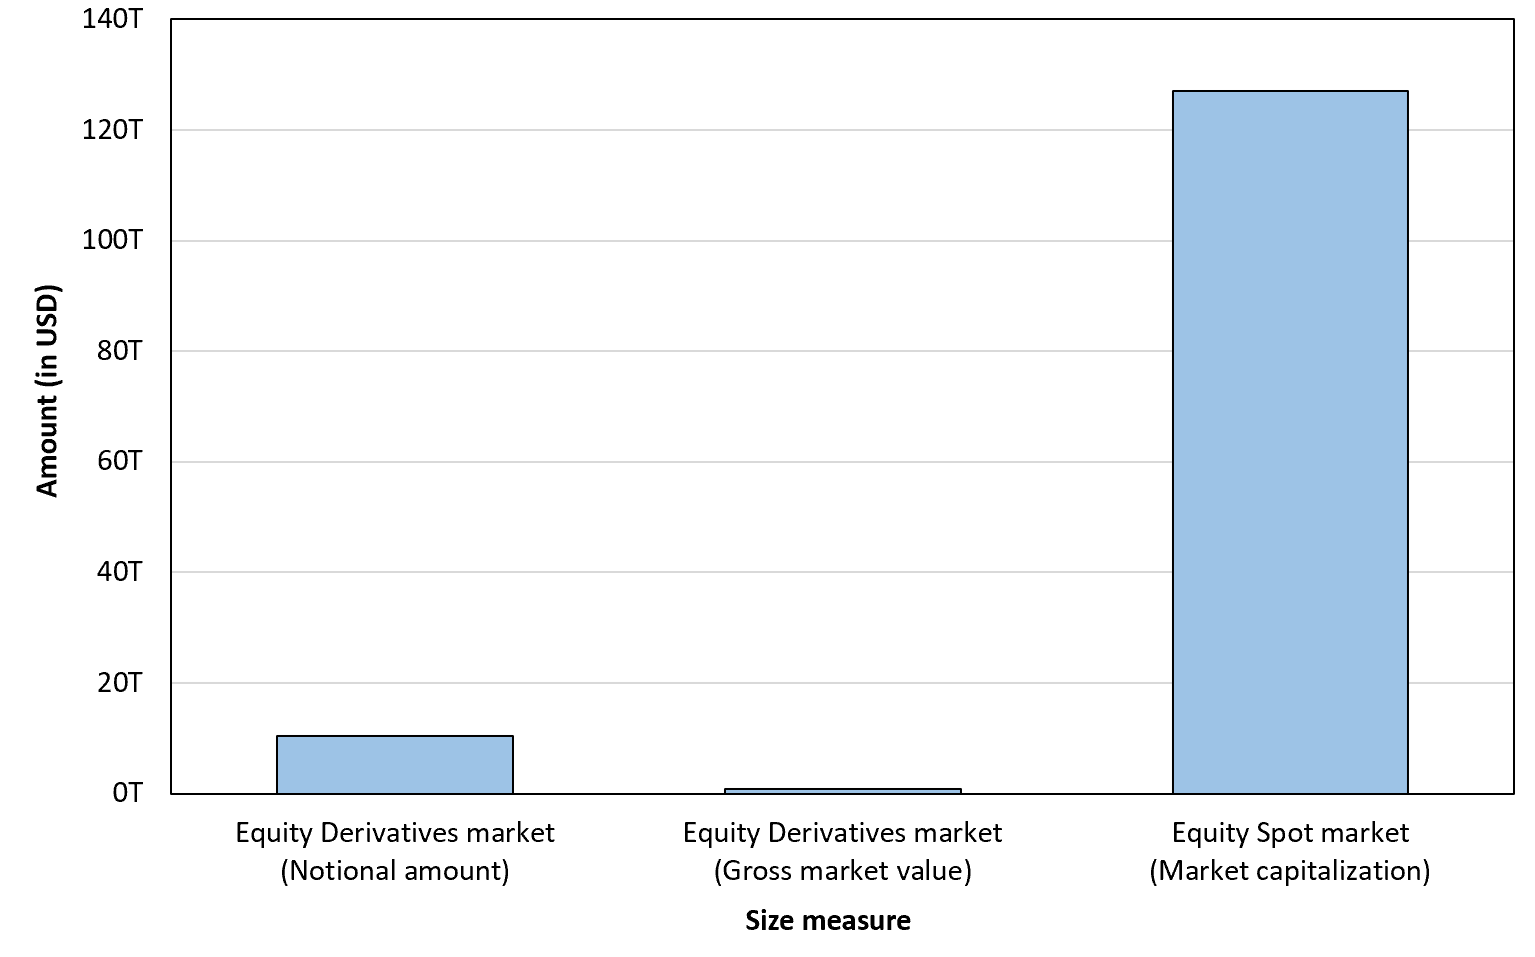
Figure 2 below compares the scale of the global equity derivatives market with that of the underlying equity spot market as of mid-2025. The figure shows that, although equity derivatives represent a sizeable market in notional terms, they are still much smaller than the equity spot market measured by market capitalization. This suggests that the primary locus of economic value in equities remains in the spot market, while the derivatives market mainly represents contingent claims written on that underlying value rather than a comparable pool of market wealth. The relatively small gross market value of equity derivatives further indicates that only a limited portion of derivative notional translates into actual market exposure.

Figure 2. Equity Markets: Spot versus Derivatives (2025)
Equity Markets: Spot versus Derivatives (2025)
Source: computation by the author (BIS and Visual Capitalist data of 2025).

Data sources: global derivatives notional outstanding as of mid-2025 BIS OTC and exchange traded data; global equity spot market capitalization as of 2025 (Visual Capitalist).

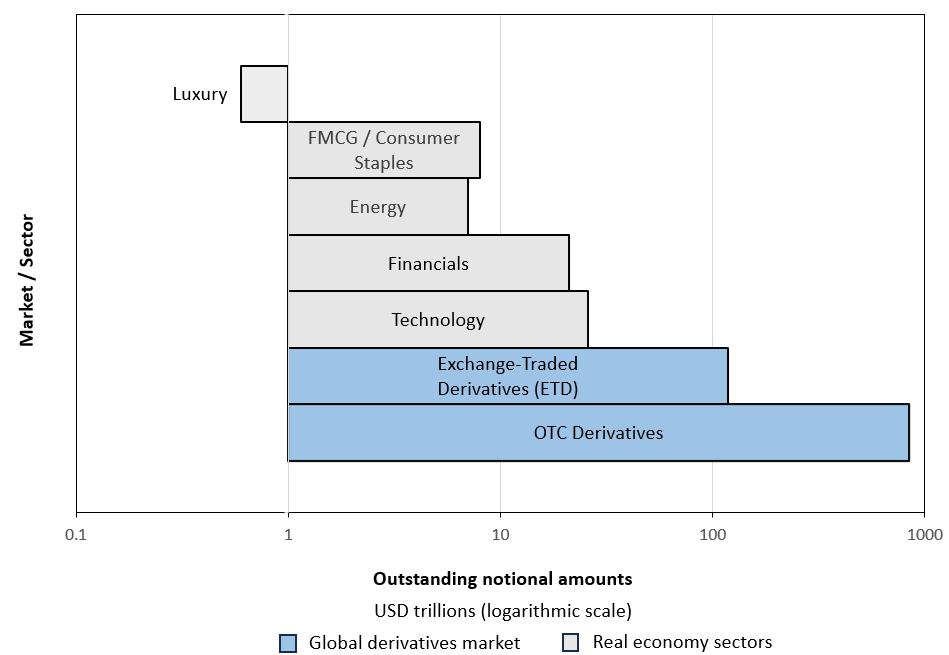
Figure 3 below juxtaposes the global derivatives market with selected real-economy sectors to provide an intuitive comparison of scale. Values are reported in USD trillions and plotted on a logarithmic axis, such that equal distances along the horizontal scale correspond to ten-fold (×10) changes in magnitude rather than linear increments. This representation allows quantities that differ by several orders of magnitude to be meaningfully displayed within a single chart.

Interpreted in this manner, the figure illustrates that the notional size of derivatives markets far exceeds the market capitalization of major real-economy sectors, including technology, financials, energy, fast moving consumer goods (FMCG), and luxury. The comparison is illustrative rather than like-for-like, and is intended to contextualize the scale of financial contract exposure rather than to imply equivalent economic value or direct risk.

Figure 3. Scale of Global Derivatives Relative to Major Real-Economy Sectors (2025)
Scale of Global Derivatives Relative to Major Real-Economy Sectors (2025)
Source: computation by the author (BIS and Visual Capitalist data).

Data sources: BIS OTC derivatives statistics (June 2025) for notional outstanding; Visual Capitalist global stock market sector data (2025) for sector market capitalizations; companies market cap / Visual Capitalist for luxury company market caps.

OTC derivatives market

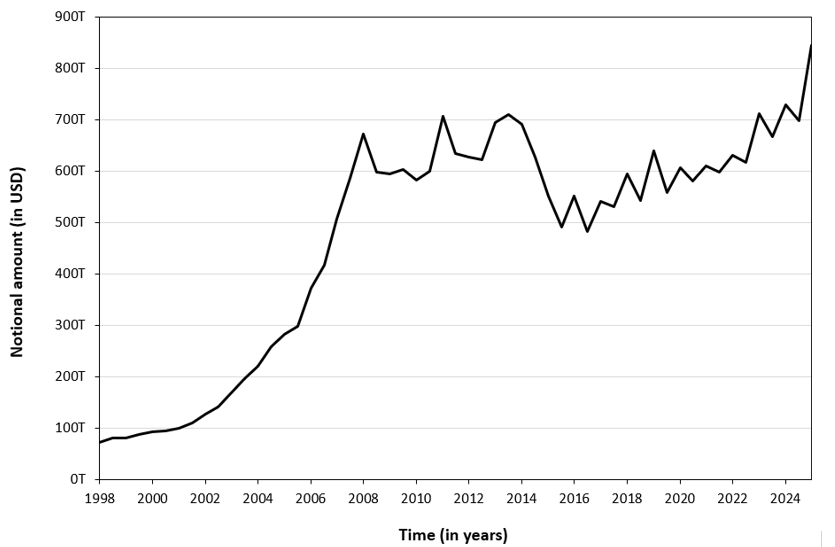
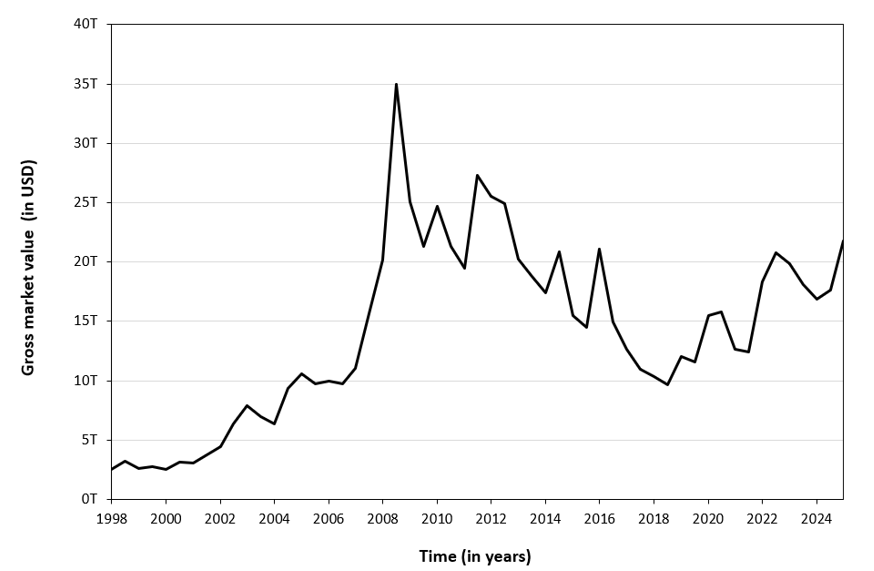
Figures 4 and 5 below illustrate the evolution of the OTC derivatives market from 1998 to 2025 using the two measures discussed above: outstanding notional amounts (Figure 4) and gross market value (Figure 5). As the data show, notional outstanding tends to overstate the effective economic size of the market, as it reflects contractual face values rather than actual risk exposure. By contrast, gross market value provides a more economically meaningful measure by capturing the current cost of replacing outstanding contracts at prevailing market prices.

Figure 4. Size of the OTC Derivatives Market (Notional amount)
Size of the OTC derivative market (Notional amount)
Source: computation by the author (BIS data).

Figure 5. Size of the OTC Derivatives Market (Gross market value)
Size of the OTC derivative market (Gross market value)
Source: computation by the author (BIS data).

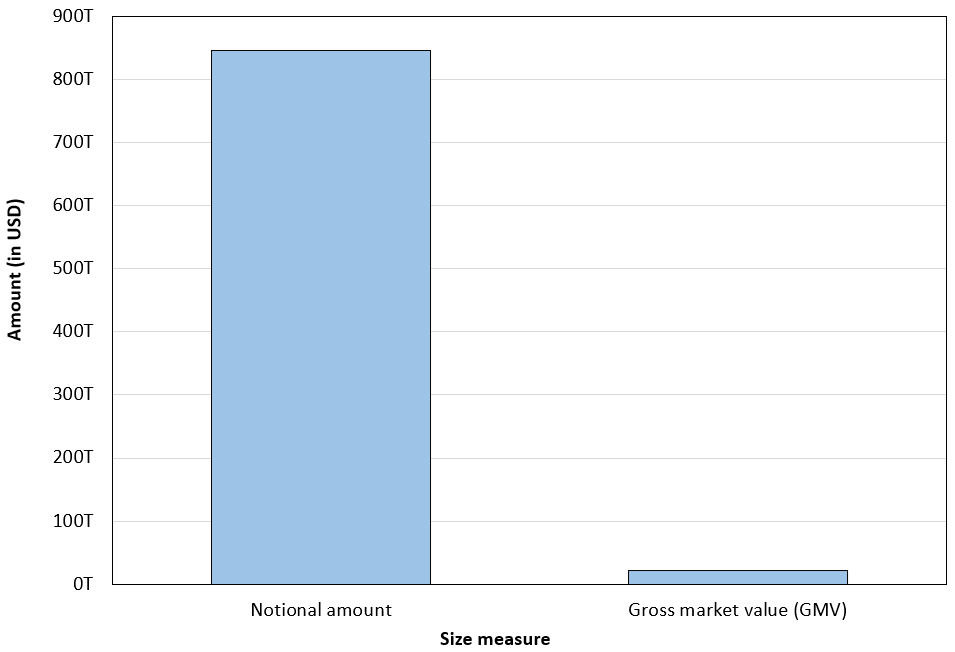
The figure below illustrates the OTC derivatives market data as of 30th July 2025 based on the two metrics discussed above: outstanding notional amounts and gross market value. As the data show, Gross market value (GMV) represents only about 2.6% of total notional outstanding, highlighting the large gap between contractual face values and economically meaningful exposure.

Figure 6. Size measure of the OTC derivatives market (2025)
Size of the OTC derivative market (2025)
Source: computation by the author (BIS data).

Exchange-traded derivatives market

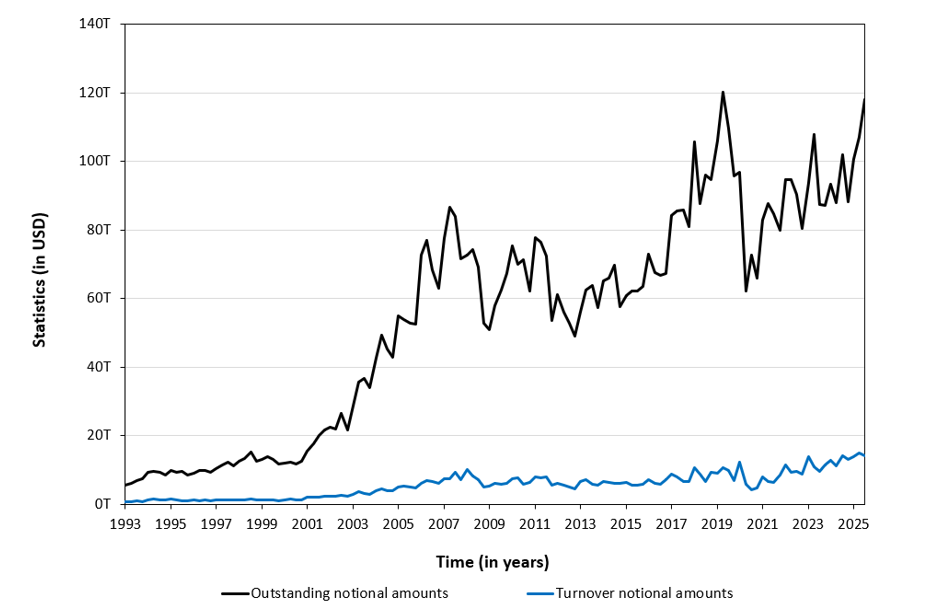
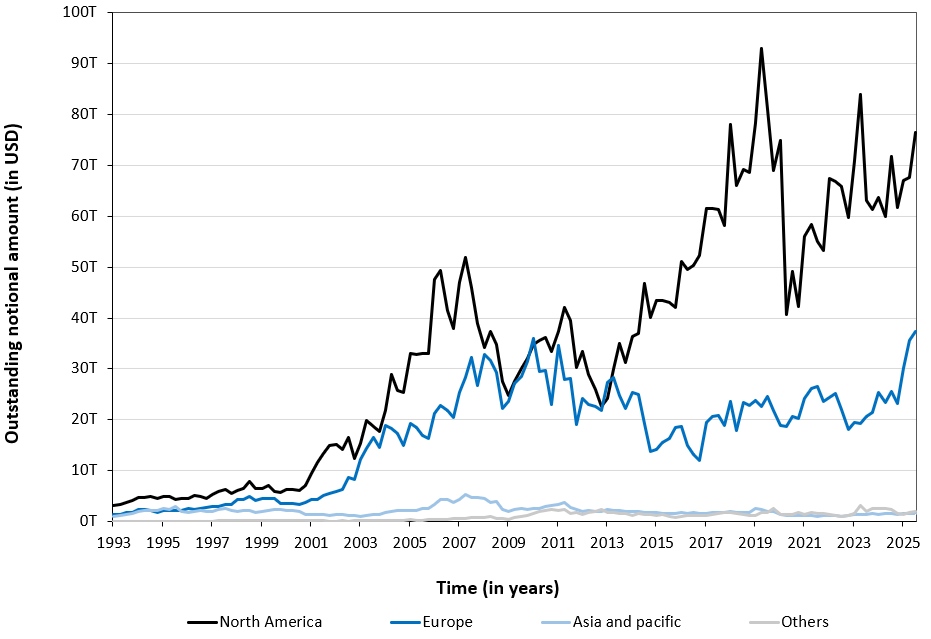
Figure 7 below illustrates the growth of the exchange-traded derivatives market from 1993 to 2025, based on outstanding notional amounts (open interest) and turnover notional amounts (trading volume). For comparability across contracts and exchanges, open interest is expressed in notional terms by multiplying the number of open contracts by their contract size, yielding US dollar equivalents. Turnover is defined as the notional value of all futures and options traded during the period, with each trade counted once.

Figure 7. Size of the Exchange-Traded Derivatives Market
Size of the exchange traded derivatives market
Source: computation by the author (BIS data).

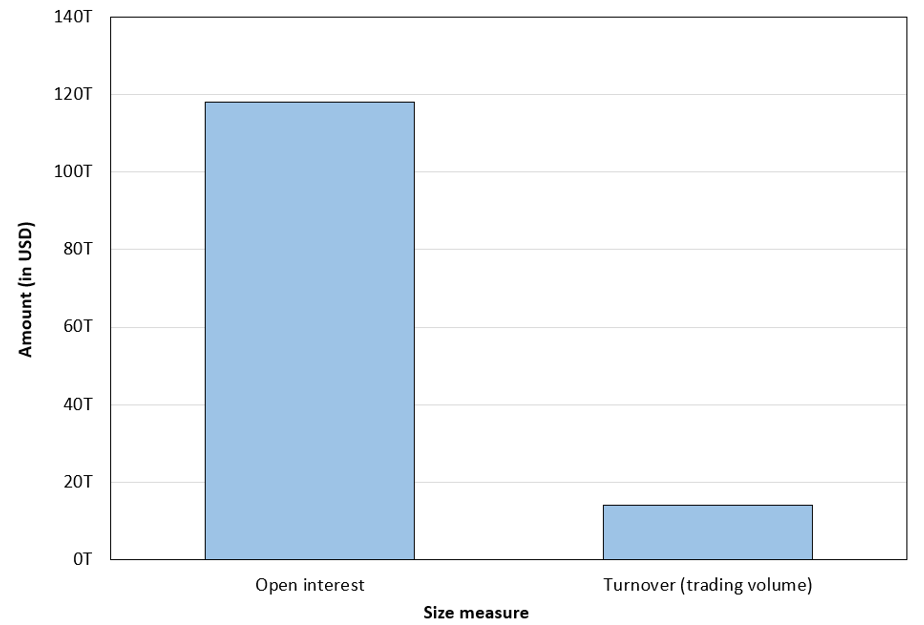
The figure below illustrates the exchange-traded derivatives market data as of 30th July 2025 based on the two metrics discussed above: open interest and turnover (trading volume). The chart shows that only about 12%, of the open positions is actively traded, highlighting the difference between market size and the trading activity.

Figure 8. Size of the Exchange traded derivatives market (2025)
Size of the exchange traded derivatives market (2025)
Source: computation by the author (BIS data).

Figure 9 below illustrates the evolution of the global exchange-traded derivatives market from 1993 to 2025, measured by outstanding notional amounts across major regions. The figure reveals a pronounced concentration of activity in North America and Europe, which drives most of the market’s expansion over time, while Asia-Pacific and other regions play a more modest role. Despite cyclical fluctuations, the overall trajectory is one of sustained long-run growth, underscoring the increasing importance of exchange-traded derivatives in global risk management and price discovery.

Figure 9. Size of the Exchange-Traded Derivatives Market by geographical locations
Size of the exchange traded derivatives market by geographic location
Source: computation by the author (BIS data).

Underlying asset classes

This section analyzes underlying asset-class statistics for derivatives traded in exchange-traded (ETD) and over-the-counter (OTC) markets.

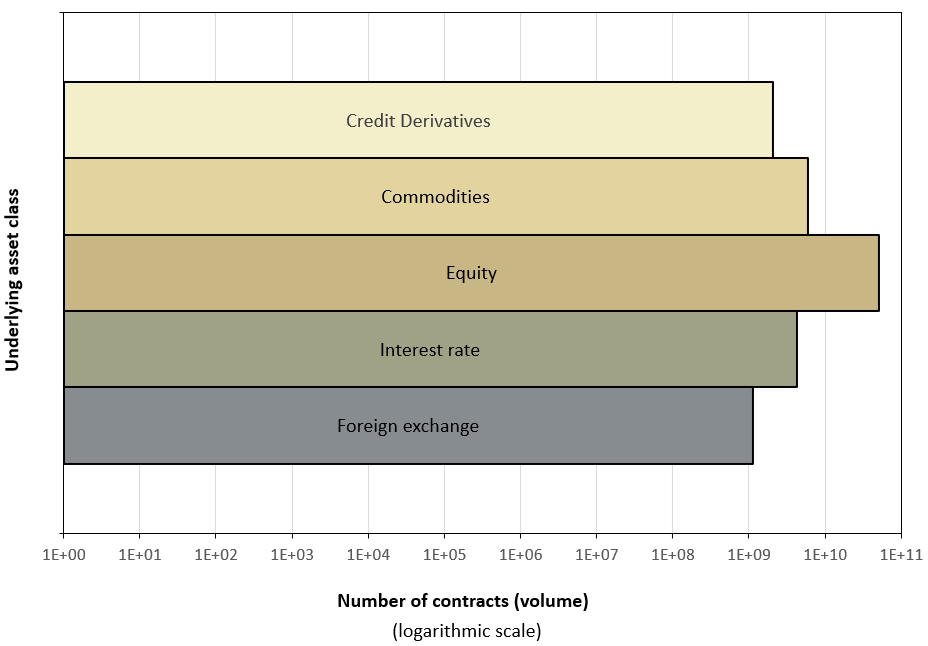
Figure 10 below presents the distribution of exchange-traded derivatives (ETDs) activity across major underlying asset classes. When measured by the number of contracts traded (volume), the market is highly concentrated, with Equity derivatives dominating and accounting for the vast majority of activity. This is followed at a significant distance by Interest Rate and Commodity derivatives. However, this distribution reverses when measured by the notional value of outstanding contracts, where Interest Rate derivatives represent the largest share of the market due to the high underlying value of each contract.

Figure 10. Size of the exchange-traded derivatives market by asset classes
Size of the exchange traded derivatives market
Source: computation by the author (FIA data).

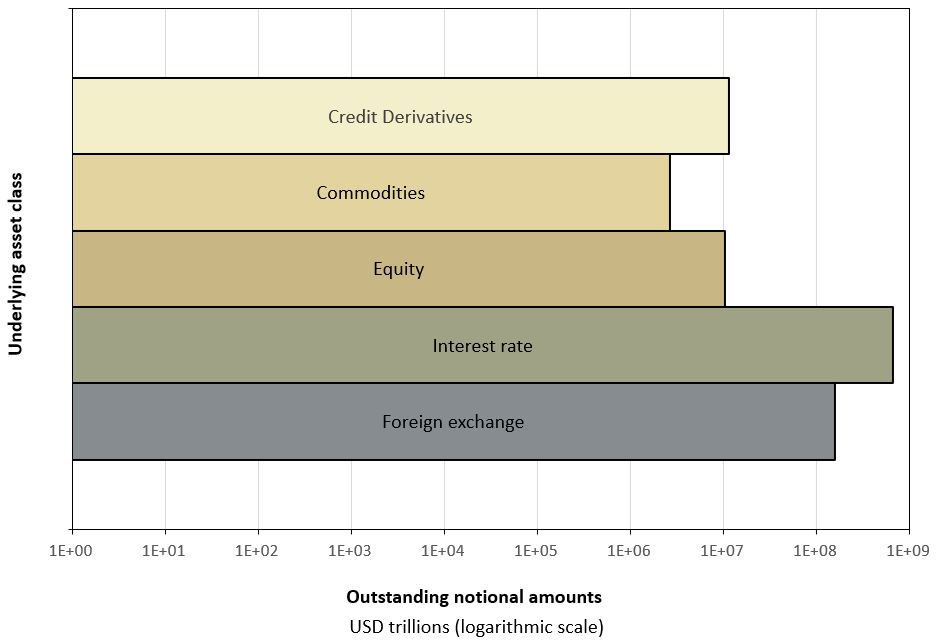
Figure 11 below presents the distribution of OTC derivatives activity across major underlying asset classes, measured by the outstanding notional amounts and displayed on a logarithmic scale. Read in this way, the chart shows that OTC activity is broadly diversified across interest rates, equity indices, commodities, foreign exchange, and credit, with interest rate and foreign exchange derivatives accounting for the largest contract volumes.

Figure 11. Size of the OTC derivatives market by asset classes
Size of the exchange traded derivatives market
Source: computation by the author (BIS data).

Role of the Black–Scholes–Merton (BSM) model

The Black–Scholes–Merton (BSM) model played a role in financial markets that extended well beyond option pricing. As argued by MacKenzie and Millo (2003), once adopted by traders and exchanges, it actively shaped how options markets were organized, priced, and operated rather than merely describing pre-existing price behaviour. Its use at the Chicago Board Options Exchange (CBOE) helped standardize quoting practices, enabled model-based hedging, and supported the rapid growth of liquidity in listed options markets.

At a broader level, MacKenzie (2006) shows that BSM contributed to a transformation in financial culture by embedding theoretical assumptions about risk, volatility, and rational pricing into everyday market practice. In this sense, BSM acted as an “engine” that reshaped markets and economic behaviour, not simply a “camera” recording them.

Beyond markets and firms, the diffusion of the BSM model also had wider societal implications. By formalizing risk as something that could be quantified, priced, and hedged, BSM contributed to a broader cultural shift in how uncertainty was perceived and managed in modern economies (MacKenzie, 2006). This reframing reinforced the view that complex economic risks could be controlled through mathematical models, with public perceptions of financial stability.

Why should you be interested in this post?

For anyone aiming for a career in finance, understanding the derivatives market is essential, as it is currently one of the most actively traded markets and is expected to grow further. Studying the statistics and business impact of derivatives provides valuable context on past challenges and the solutions developed to manage risks, offering a solid foundation for analyzing and navigating modern financial markets.

Related posts on the SimTrade blog

   ▶ Jayati WALIA Derivatives Market

   ▶ Alexandre VERLET Understanding financial derivatives: options

   ▶ Alexandre VERLET Understanding financial derivatives: forwards

   ▶ Alexandre VERLET Understanding financial derivatives: futures

   ▶ Akshit GUPTA Understanding financial derivatives: swaps

   ▶ Akshit GUPTA The Black Scholes Merton model

   ▶ Luis RAMIREZ Understanding Options and Options Trading Strategies

Useful resources

Academic research on option pricing

Black F. and M. Scholes (1973) The pricing of options and corporate liabilities. Journal of Political Economy, 81(3), 637–654.

Merton R.C. (1973) Theory of rational option pricing. The Bell Journal of Economics and Management Science, 4(1), 141–183.

Hull J.C. (2022) Options, Futures, and Other Derivatives, 11th Global Edition, Chapter 15 – The Black–Scholes–Merton model, 338–365.

Academic research on the role of models

MacKenzie, D., & Millo, Y. (2003). Constructing a Market, Performing Theory: The Historical Sociology of a Financial Derivatives Exchange. American Journal of Sociology, 109(1), 107–145.

MacKenzie, D. (2006). An Engine, not a Camera: How Financial Models Shape Markets. MIT Press.

Data

Bank for International Settlements (BIS). Retrieved from BIS Statistics Explorer.

Futures Industry Association (FIA). Retrieved from ETD Volume Reports.

Visual Capitalist. Retrieved from The Global Stock Market by Sector.

Visual Capitalist. Retrieved from Piecing Together the $127 Trillion Global Stock Market.

About the author

The article was written in February 2026 by Saral BINDAL (Indian Institute of Technology Kharagpur, Metallurgical and Materials Engineering, 2024-2028 & Research assistant at ESSEC Business School).

   ▶ Discover all articles written by Saral BINDAL

Coffee Futures: The Economic and Environmental Drivers Behind Rising Prices

Camille Keller

In this article, Camille Keller (ESSEC Business School, Bachelor in Business Administration (BBA), 2020-2024) explores the economic and environmental factors influencing rising coffee prices, shedding light on global futures markets and sustainability efforts.

Environmental Factors: Climate Change and Coffee Production

It’s no secret that coffee is deeply tied to the environment. Arabica coffee, cherished for its smooth flavor, accounts for about 60% of global coffee production—but it’s also notoriously sensitive to climate change. Reardon-Smith et al. (2019) highlight how rising temperatures and unpredictable weather patterns are shrinking suitable growing areas and reducing yields. The regions best known for coffee cultivation, including Brazil and Vietnam, are among the hardest hit.

A study by Tavares et al. (2018) paints a stark picture for Southeast Brazil, a vital hub for Arabica production. Projections indicate that suitable cultivation areas could drop by as much as 60% by the end of the century, with yields potentially falling by 25% under high greenhouse gas scenarios. These environmental hurdles are compounded by deforestation and soil degradation, leaving farmers with limited options to sustain production.

Adding to the pressure, Trading Economics (2025) reports that persistent below-normal rainfall in key Brazilian regions has exacerbated supply constraints. Brazil’s 2024 coffee harvest was estimated at 54.2 million 60-kg bags, down 1.6% from the previous year. Such trends not only strain global supply but also drive prices higher as demand outpaces production.

The ICO Composite Indicator Price (I-CIP)
Source: ICO Report 2024.

Economic Factors: Supply Chain Disruptions and Consumer Trends

Beyond environmental woes, economic forces play a crucial role in the coffee market. In recent years, global supply chain disruptions have caused delays and driven up transportation costs, creating additional upward pressure on coffee prices. The COVID-19 pandemic underscored the fragility of global logistics, making it harder to get coffee beans from farms to consumers.

Consumer behavior also holds significant sway. According to Capps et al. (2023), coffee demand in the United States is highly price-sensitive, with a price elasticity of -1.93. This means that as prices rise, many consumers cut back on their purchases. Yet, wealthier households tend to continue buying coffee regardless of price increases, reflecting the complex dynamics of socioeconomic factors in shaping demand.

Meanwhile, the International Coffee Organization (ICO, 2024) notes that global coffee prices rose by 40% in 2024, with the ICO Composite Indicator Price averaging 299.61 US cents/lb in December. This surge has been driven by a combination of tight supply and robust demand, particularly for Arabica coffee. Additionally, logistical challenges, such as container shortages and prolonged shipping times to European markets, have amplified cost pressures throughout the supply chain.

Certified Stocks of Arabica and Robusta Coffee
Source: ICO Report 2024.

EU Regulations and Market Dynamics

Adding to these challenges are new European Union regulations aimed at combating deforestation. Savage (2024) reports that coffee futures hit a 47-year high in November 2024, partly due to fears surrounding these laws. The regulations require companies to ensure their supply chains are free of deforestation, significantly increasing compliance costs for producers. While these measures promote sustainability, they have also added uncertainty and volatility to the market, pushing prices further upward.

Moreover, the ICO (2024) highlights the volatility of coffee prices, with Arabica and Robusta exhibiting sharp fluctuations. Certified stocks of Robusta coffee increased by 13.3% from November to December 2024, while Arabica stocks grew by 7.8%. Despite these increases, the imbalance between supply and demand continues to fuel price volatility, as traders and roasters navigate a challenging market landscape.

Conclusion: Future Outlook of a Volatile Market

The interplay of environmental and economic factors makes it clear: coffee prices are unlikely to stabilize anytime soon. Climate change will continue to constrain supply, while evolving consumer preferences and regulatory changes shape demand. This complex web of factors requires innovative solutions from policymakers, industry leaders, and consumers alike.

For consumers, this may mean accepting higher prices as the new norm. However, increased awareness of the environmental and social costs of coffee production could drive more sustainable consumption patterns. Initiatives such as fair trade certification and carbon-neutral labeling are gaining momentum, offering a pathway to a more equitable and resilient coffee industry.

Why Should I Be Interested in This Post?

This post provides ESSEC students and global business enthusiasts with valuable insights into how environmental changes, economic challenges, and regulatory dynamics are shaping one of the world’s most consumed commodities.

Related Posts on the SimTrade Blog

   ▶ Camille KELLER Global Coffee Habits: Understanding Consumption Trends Across the World

   ▶ Camille KELLER From bean to brew: understanding coffee as a global commodity

   ▶ Anant JAIN Understanding Price Elasticity Of Demand

   ▶ Akshit GUPTA Futures Contract

Useful Resources

International Coffee Organization (ICO) Coffee Market Report 2024

Trading Economics Arabica Coffee Futures

Financial Times Coffee Futures Hit 47-Year High

Yen Pham, Kathryn Reardon-Smith, Shahbaz Mushtaq & Geoff Cockfield (2019) The impact of climate change and variability on coffee production: a systematic review Climatic Change Journal, 156, 609-630

About the Author

The article was written in January 2025 by Camille Keller (ESSEC Business School, Bachelor in Business Administration (BBA), 2020-2024).

Forex exchange markets

Forex exchange markets

Nakul PANJABI

In this article, Nakul PANJABI (ESSEC Business School, Grande Ecole Program – Master in Management, 2021-2024) explains how the foreign exchange markets work.

Forex Market

Forex trading can be simply defined as exchange of a unit of one currency for a certain unit of another currency. It is the act of buying one currency while simultaneously selling another.

Foreign exchange markets (or Forex) are markets where currencies of different countries are traded. Forex market is a decentralised market in which all trades take place online in an over the counter (OTC) format. By trading volume, the forex market is the largest financial market in the world with a daily turnover of 6.6 trillion dollars in 2019. At present, it is worth 2,409 quadrillion dollars. Major currencies traded are USD, EUR, GBP, JPY, and CHF.

Players

The main players in the market are Central Banks, Commercial banks, Brokers, Traders, Exporters and Importers, Immigrants, Investors and Tourists.

Central banks

Central banks are the most important players in the Forex Markets. They have the monopoly in the supply of currencies and therefore, tremendous influence on the prices. Central Banks’ policies tend to protect aggressive fluctuations in the Forex Markets against the domestic currency.

Commercial banks

The second most important players of the Forex market are the Commercial Banks. By quoting, on a daily basis, the foreign exchange rates for buying and selling they “Make the Market”. They also function as Clearing Houses for the Market.

Brokers

Another important group is that of Brokers. Brokers do not participate in the market but acts as a link between Sellers and Buyers for a commission.

Types of Transactions in Forex Markets

Some of the transactions possible in the Forex Markets are as follows:

Spot transaction

As spot transaction uses the spot rate and the goods (currencies) are exchanges over a two-day period.

Forward transaction

A forward transaction is a future transaction where the currencies are exchanged after 90 days of the deal a fixed exchange rate on a defined date. The exchange rate used is called the Forward rate.

Future transaction

Futures are standardized Forward contracts. They are traded on Exchanges and are settled daily. The parties enter a contract with the exchange rather than with each other.

Swap transaction

The Swap transactions involve a simultaneous Borrowing and Lending of two different currencies between two investors. One investor borrows the currency and lends another currency to the second investor. The obligation to repay the currencies is used as collateral, and the amount is repaid at forward rate.

Option transaction

The Forex Option gives an investor the right, but not the obligation to exchange currencies at an agreed rate and on a pre-defined date.

Peculiarities of Forex Markets

Trading of Forex is not much different from trading of any other asset such as stocks or bonds. However, it might not be as intuitive as trading of stocks or bonds because of its peculiarities. Some peculiarities of the Forex market are as follows:

Going long and short simultaneously

Since the goods traded in the market are currencies themselves, a trade in the Forex market can be considered both long and short position. Buying dollars for euros can be profitable in cases of both dollar appreciation and euro depreciation.

High liquidity and 24-hour market

As mentioned above, the Forex market has the largest daily trading volume. This large volume of trading implies the highly liquid feature of Forex Assets. Moreover, Forex market is open 24 hours 5 days a week for retail traders. This is due to the fact that Forex is exchanged electronically over the world and anyone with an internet connection can exchange currencies in any Forex market of the world. In fact for Central banks and related organisations can trade over the weekends as well. This can cause a change in the price of currencies when the market opens to retail traders again after a gap of 2 days. This risk is known as Gapping risk.

High leverage and high volatility

Extremely high leverage is a common feature of Forex trades. Using high leverage can result in multiple fold returns in favourable conditions. However, because of high trading volume, Forex is very volatile and can go in either upward or downward spiral in a very short time. Since every position in the Forex market is a short and long position, the exposure from one currency to another is very high.

Hedging

Hedging is one of the main reasons for a lot of companies and corporates to enter into a Forex Market. Forex hedging is a strategy to reduce or eliminate risk arising from negative movement in the Exchange rate of a particular currency. If a French wine seller is about to receive 1 million USD for his wine sales then he can enter into a Forex futures contract to receive 900,000 EUR for that 1 million USD. If, at the date of payment, the rate of 1 million USD is 800,000 EUR the French wine seller will still get 900,000 EUR because he hedged his forex risk. However, in doing so, he also gave up any gain on any positive movement in the EUR-USD exchange rate.

Related posts on the SimTrade blog

   ▶ Jayati WALIA Currency overlay

   ▶ Louis DETALLE What are the different financial products traded in financial markets?

   ▶ Akshit GUPTA Futures Contract

   ▶ Akshit GUPTA Forward Contracts

   ▶ Akshit GUPTA Currency swaps

   ▶ Luis RAMIREZ Understanding Options and Options Trading Strategies

Useful resources

Academic resources

Solnik B. (1996) International Investments Addison-Wesley.

Business resources

DailyFX / IG The History of Forex

DailyFX / IG Benefits of forex trading

DailyFX / IG Foreign Exchange Market: Nature, Structure, Types of Transactions

About the author

The article was written in December 2022 by Nakul PANJABI (ESSEC Business School, Grande Ecole Program – Master in Management, 2021-2024).

Initial and maintenance margins in futures contracts

Akshit Gupta

This article written by Akshit GUPTA (ESSEC Business School, Grande Ecole Program – Master in Management, 2019-2022) explains the mechanisms of initial and maintenance margin used in futures contracts.

Introduction

In financial markets, margin requirements are present in leveraged positions in derivative products. They refer to a percentage of assets that an investor must pay for with his or her own cash or assets (collateral) as a means of protection against the risk exposure to its potential default for the other counterpart.

Margin requirements serve as a guarantee that the investor providing the margins will fulfil its trade obligations. Many exchanges across the world provide leverage facilities to investors for trading in different derivative assets. For example, an investor can use leverage facilities for trading in futures contracts across different asset classes like equities, bonds, currencies, interest rates, etc.

Margin requirements can be categorized as initial and maintenance margin requirements.

Initial margin

Initial margin (or IM) refers to the initial deposit required when an investor opens a position in a derivative product and amounts to a percentage of the nominal contract value. The amount for initial margin requirement is calculated in accordance with approved margin models that are based on the market’s regulatory rules. The determination of the initial margin requirement is essentially based on the volatility of the underlying asset of the derivative product being covered. The more volatile the underlying asset, the higher the initial margin requirement.

You can download below the file to learn about the different Euronext Clearing margin requirements used in derivatives trading.

Maintenance margin

When an investor holds an underlying asset on margin, she is required to maintain a minimum margin amount of that asset position in her portfolio to keep her position open and this is known as the maintenance margin. Maintenance margin requirements aim to protect against excess losses and ensures the broker has enough capital to cover any losses the investor may incur. Maintenance margin is generally calculated on a daily mark-to-market basis between the period starting from the trading date to the contract expiration date.

In case the investor is unable to fulfil the maintenance margin requirements, she receives a margin call initiated from the broker to deposit further amount in order to keep her position open. If she fails to provide adequate maintenance margins, the broker has the power to close her positions.

Mechanism of initial and maintenance margins

Now, we will see how initial and maintenance margins work in the financial markets using S&P 500 mini futures contract. Since the investor has bought the futures contract, he/she is required by its broker to post an initial margin at the time the trade is initiated. For instance, this initial margin is set to 40% of the nominal value of the contract. This money is essentially the collateral on the purchase to protect the seller of the contract in the future against the default of the buyer (the investor).

Followed by this, a maintenance margin is required at any point of time after the trade is initiated. The maintenance margin call is triggered when the value of the initial margin falls below the 30% threshold (i.e. 70% of the initial margin). The buyer has to ensure that any time the position falls below this maintenance margin requirements, he will get a margin call and has to increase funds into the margin account.

Example with initial margin

Here is an example of a typical case of buying a futures contract and its margin mechanism:

The characteristics of the contract and market data include:

 Margin call on futures

 Margin call on long futures

The final value of the investor’s brokerage account is equal to $253,000. At the end of the contract, the investor can get back its initial margin of $158,000 leaving $95,000 on its account. The gain is equal to $10,000 which is the amount left on the account ($95,000) minus the sum of the margin calls ($85,000).

Here is an example of a typical case of selling a futures contract and its margin mechanism using the same characteristics and market data:

 Margin call on short futures

The final value of the investor’s brokerage account is equal to $178,000. At the end of the contract, the investor can get back its initial margin of $158,000 leaving $20,000 on its account. The loss is equal to $10,000 which is the amount left on the account ($20,000) minus the sum of the margin calls ($30,000).

You can download below the Excel file for the computation of the Intial and Maintenance Margins for the futures contracts.

Download the Excel file to compute the initial margins for futures

Related posts in the SimTrade blog

▶ Akshit GUPTA Initial and Maintenance margin in stocks

▶ Akshit GUPTA Analysis of the Big Short movie

▶ Akshit GUPTA Analysis of the Margin call movie

▶ Akshit GUPTA Analysis of the Trading places movie

Useful resources

Maintenance margin

Initial Margin

Financial Industry Regulatory Authority (FINRA)

Prof. Longin’s website Margin Call mechanism for a futures contract (in French).

About the author

Article written in August 2022 by Akshit GUPTA (ESSEC Business School, Grande Ecole Program – Master in Management, 2019-2022).

▶ Discover all posts by Akshit GUPTA

Forward Contracts

Akshit Gupta

This article written by Akshit GUPTA (ESSEC Business School, Grande Ecole Program – Master in Management, 2019-2022) introduces Forward contracts.

Introduction

Forward contracts form an essential part of the derivatives world and can be a useful tool in hedging against price fluctuations. A forward contract (or simply a ‘forward’) is an agreement between two parties to buy or sell an underlying asset at a specified price on a given future date (or the expiration date). The party that will buy the underlying is said to be taking a long position while the party that will sell the asset takes a short position.

The underlying assets for forwards can range from commodities and currencies to various stocks.

Forwards are customized contracts i.e., they can be tailored according to the underlying asset, the quantity and the expiry date of the contract. Forwards are traded over-the-counter (OTC) unlike futures which are traded on centralized exchanges. The contracts are settled on the expiration date with the buyer paying the delivery price (the price agreed upon in the forward contract for the transaction by the parties involved) and the seller delivering the agreed upon quantity of underlying assets in the contract. Unlike option contracts, the parties in forwards are obligated to buy or sell the underlying asset upon the maturity date depending on the position they hold. Generally, there is no upfront cost or premium to be paid when a party enters a forward contract as the payoff is symmetric between the buyer and the seller.

Terminology used for forward contracts

A forward contract includes the following terms:

Underlying asset

A forward contract is a type of a derivative contract. It includes an underlying asset which can be an equity, index, commodity or a foreign currency.

Spot price

A spot price is the market price of the asset when the contract is entered into.

Forward price

A forward price is the agreed upon forward price of the underlying asset when the contract matures.

Maturity date

The maturity date is the date on which the counterparties settle the terms of the contract and the contract essentially expires.

Forward Price vs Spot Price

Forward and spot prices are two essential jargons in the forward market. While the strict definitions of both terms differ in different markets, the basic reference is the same: the spot price (or rate according to the underlying) is the current price of any financial instrument being traded immediately or ‘on the spot’ while the forward price is the price of the instrument at some time in the future, essentially the settlement price if it is traded at a predetermined date in the future. For example, in currency markets, the spot rate would refer to the immediate exchange rate for any currency pair while the forward rate would refer to a future exchange rate agreed upon in forward contracts.

Payoff of a forward contract

The payoff of a forward contract depends on the forward price (F0) and the spot price (ST) at the time of maturity.

Pay-off for a long position

Long Position

Pay-off for a short position

Short Position

With the following notations:
N: Quantity of the underlying assets
ST = Price of the underlying asset at time T
F0 = Forward price at time 0

For example, an investor can enter a forward contract to buy an Apple stock at a forward price of $110 with a maturity date in one month.

If at the maturity date, the spot price of Apple stock is $120, the investor with a long position will gain $10 from the forward contract by buying Apple stock for $110 with a market price of $120. The investor with a short position will lose $10 from the forward contract by selling the apple stock at $110 while the market price of $120.

Figure 1. Payoff for a long position in a forward contract
long forward

Payoff for a short position in a forward contract
Short forward

Use of forward contracts

Forward contracts can be used as a means of hedging or speculation.

Hedging

Traders can be certain of the price at which they will buy or sell the asset. This locked price can prove to be significant especially in industries that frequently experience volatility in prices. Forwards are very commonly used to hedge against exchange rates risk with most banks employing both spot and forward foreign exchange-traders. In a forward currency contract, the buyer hopes the currency to appreciate, while the seller expects the currency to depreciate in the future.

Speculation

Forward contracts can also be used for speculative purposes though it is less common than as forwards are created by two parties and not available for trading on centralized exchanges. If a speculator believes that the future spot price of an asset will be greater than the forward price today, she/he may enter into a long forward position and thus if the viewpoint is correct and the future spot price is greater than the agreed-upon contract price, she/he will gain profits.

Risks Involved

Liquidity Risk

A forward contract cannot be cancelled without the agreement of both counterparties nor can it be transferred to a third party. Thus, the forward contract is neither very liquid nor very marketable.

Counterparty risk

Since forward contracts are not traded on exchanges, they involve high counterparty risk. In these contracts, either of the counterparties can fail to meet their obligation resulting in a default.

Regulatory risk

A forward contract is traded over the counter due to which they are not regulated by any authority. This leads to high regulatory risk since it is entered with mutual consent between two or more counterparties.

Related posts in the SimTrade blog

▶ Akshit GUPTA Futures contract

Useful Resources

Hull J.C. (2015) Options, Futures, and Other Derivatives, Ninth Edition, Chapter 1 – Introduction, 23-43.

Hull J.C. (2015) Options, Futures, and Other Derivatives, Ninth Edition, Chapter 5 – Determination of forward and futures prices, 126-152.

About the author

Article written in June 2021 by Akshit GUPTA (ESSEC Business School, Grande Ecole Program – Master in Management, 2019-2022).

▶ Discover all posts by Akshit GUPTA

Film analysis: Rogue Trader (1999)

Akshit Gupta

This article written by Akshit GUPTA (ESSEC Business School, Grande Ecole Program – Master in Management, 2019-2022) analyzes The Rogue Trader movie and explains the related financial concepts.

Rogue Trader (1999) is a British drama film depicting the life of Nick Leeson, a former derivate broker based out in Singapore. The story is inspired by real-life events that shook the global financial system and led to the collapse of the world’s second-oldest merchant bank named Barings Bank based out in England. The movie is based on a book by Nick Leeson named Rogue Trader: How I brought down Barings Bank and shook the financial world and is one of the greatest examples of why a trader shouldn’t try to fight the market.

Summary of the movie

The Rogue Trader movie

The movie starts by introducing Nick Leeson, a person who starts his career by working for Barings Bank in Indonesia and is later promoted to work as a derivatives trader at the trading seat of the bank at Singapore International Monetary Exchange (SIMEX), Singapore. He was made to look after the trades as well as the back office work of and entering and settling those trades by the end of the day. His job is to trade futures contracts based on Nikkei 225, a stock index at Japan Stock Exchange, on behalf of Baring’s clients, and generate profits by arbitraging the small price difference between SIMEX and Japan Stock Exchange. He hires a team of people to be the floor traders for him and imparts them requisite training for executing the orders. Everything seemed fine until, owing to a trader’s error, Nick accrues a small loss. To cover the losses made by the trader, Nick starts trading futures under a newly formed account numbered 88888, an unauthorized account, which is prohibited under the bank laws. Soon, his trades start falling apart and he starts incurring losses amounting to millions of pounds. To conceal the facts from his seniors, Nick lands up a big client and makes enough commission on his trades to make up for the losses. But since he wanted to play big, instead of making profits by arbitraging his positions, Nick starts to hold on to his positions in expectations of higher future prices.

However, his unhedged positions start pouring in heavy losses when a major earthquake hits Japan in 1995 and the stock market starts dwindling. Still determined to cover his losses, Nick starts buying Nikkei futures in large quantities and tries to move the market in his favor. To meet the margin calls, Nick asks the head office in London to wire him more money to enter bigger deals.  But as the market keeps on falling, the losses start amounting to hundreds of millions of pounds. The management of the bank remains oblivious of the losses that are accumulating in the account number 88888, which is an account operated under a client’s name. Barings back had a poor compliance system and regular audits weren’t carried out in a proper manner giving rise to losses amounting to 800 million pounds, almost double the amount of capital Barings had.

As the market keeps going against him, Nick realizes that his game is coming to an end. Nick and his wife plan to leave Singapore to save him from judicial actions. But eventually, Nick is caught at Frankfurt airport and deported to Singapore where he is sentenced to 6 years’ imprisonment.

Relevance to the SimTrade course

The lessons learnt from the movie Rogue Trader are correlated to courses taught in the SimTrade course. The importance of market news has correctly been reflected in the movie by the amount Nick had to pay, trying to fight the trend. The strategy used by Nick to cover his losses known as Martingale’s strategy, or doubling the bets, is a very common mistake traders make in order to cover their past losses, but most of the time it results in even higher losses. A trader should never try to fight the market since it is rightly said that markets are always right, even when they are wrong.

The courses taught on SimTrade teach traders to cover their positions by using different types of orders to protect them from any unexpected market movements. If a stop loss/stop limit strategy would have been entered in by Nick, the losses could have been cut down. A proper investment plan with adequate use of margins and a stop-loss strategy should be put in place by every trader before entering trades. Also, a good trader should never let emotions, such as fear or greed, dictate her judgment.

Most famous quotes from the movie

“I just have to keep buying futures to support the market. If it sticks at 18,000 my options are still in the money. I could get the position back. I may even out ahead.” – Nick Leeson

“Listen to me now. You don’t fight the market!” – Another trader

“The way the market’s going, your losses could be catastrophic.” – Another trader

Trailer of the movie


Related Posts

▶ Marie POFF Film analysis: Rogue Trader

▶ Jayati WALIA Quantitative risk management

▶ Alexandre VERLET Understanding financial derivatives: futures

▶ Akshit GUPTA Futures Contract

About the author

Article written in October 2020 by Akshit GUPTA (ESSEC Business School, Grande Ecole Program – Master in Management, 2019-2022).

▶ Discover all posts by Akshit GUPTA